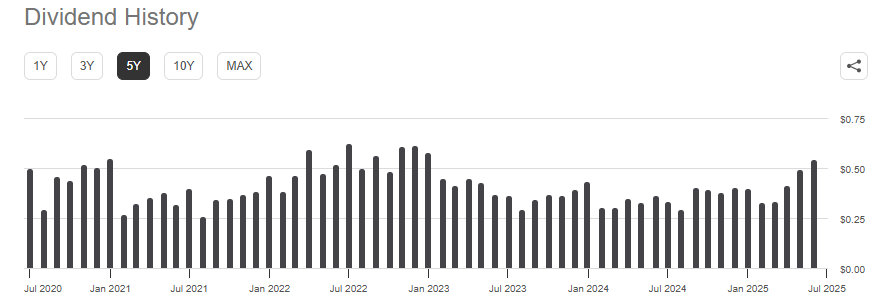Getting Historical Yield Data Out of JEPI
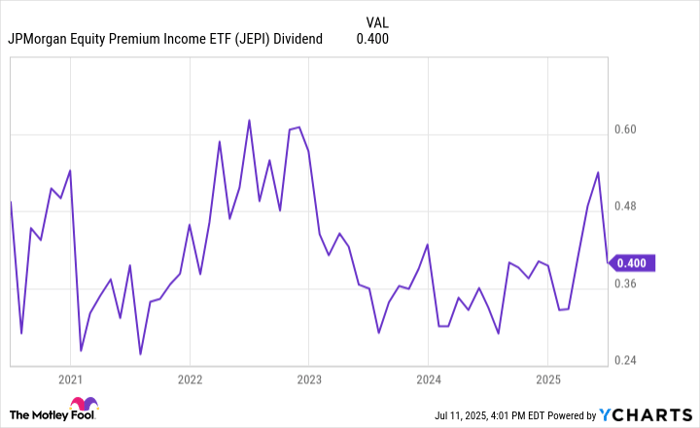
JEPI is the Jupiter Equity Premium Income ETF. It distributes monthly and its yield profile looks stable on the surface until you actually dig into the numbers. The fund sells covered calls on an S&P 500 portfolio, which creates a recurring income stream that most people casually call a "dividend" even though technically it is a combination of ordinary dividends, capital gains, and return of capital. That distinction matters more than people realize when you are trying to build a spreadsheet or compare it to other income funds. The yield history for this fund sits scattered across a few different sources. The primary source is the JPMorgan Asset Management website, where they publish monthly distribution histories. You can find a table that shows the amount per share broken down into ordinary income, qualified dividends, short-term capital gains, long-term capital gains, and return of capital for each month going back to when the fund launched in October 2020. The secondary source is the SEC filings, specifically the monthly N-PORT filings, which contain the exact same breakdown but in raw format. Most retail investors never look there because it is boring, but it is the cleanest data if you want to scrape it programmatically. I have personally hit a wall when trying to reconcile the stated yield with what actually showed up on a 1099-DIV. The published monthly distribution amounts don't always match the tax classification on your actual tax documents. The fund sometimes reclassifies amounts between ordinary income and capital gains after the fact, and they do it in February or March of the following year when they issue the final corrected 1099. I spent about two days cross-referencing the monthly tables against my actual 1099s for the 2022 tax year before realizing the discrepancy was purely a timing issue with the reclassification, not an error in the fund itself. The workaround I use now is to download the final corrected 1099 once it arrives and treat the monthly tables as estimates only until the IRS documents come through. If you are building a historical yield model, add a note that the first quarter of each calendar year will usually require an update once the corrections land.
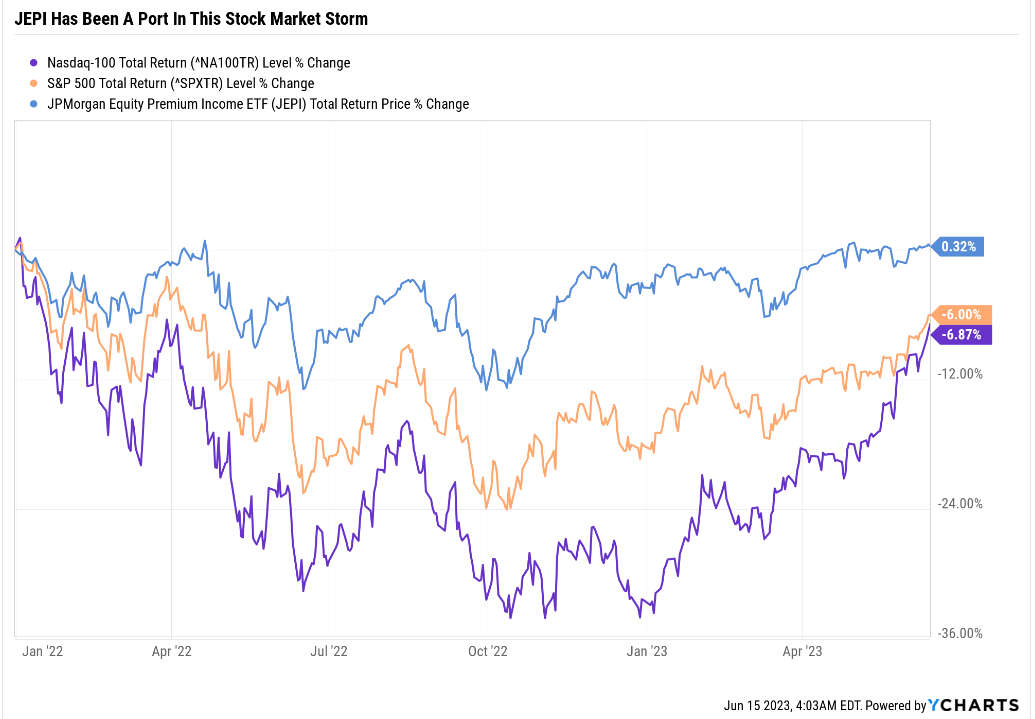
Another thing that trips people up is how yield is calculated and presented. Most financial websites show JEPI's yield as a trailing twelve-month distribution divided by the current share price. That number tends to hover in the high single digits to low double digits depending on the pricing environment, but it is a moving target because the distribution amount changes every month and the price changes daily. A trailing twelve-month yield based on January prices and December distributions will look very different from one calculated with July prices and July distributions. The fund itself publishes an SEC-standard yield figure monthly, which is the net asset value weighted distribution rate, and that number is usually lower than the market-style trailing yield you see on finance websites. Both are technically correct, but they answer different questions. The counter-intuitive part that nobody warns you about is that JEPI's distribution yield does not reliably track the S&P 500's option premium environment in a straightforward way. When volatility spikes, the covered call writing generates more premium, which pushes distributions up. But when the market drops sharply, the fund's underlying equity position loses value, which can compress the distribution amount in subsequent months even if option premiums are elevated. I have seen months where the distribution held steady despite a significant market drawdown because the call premium income offset the equity drag, and then the following month the distribution dropped because the fund's net asset value had fallen enough to reduce the pool of shares it could write calls against. Yield alone is a misleading metric here because it does not account for total return erosion from capital appreciation forgone. The fund intentionally sacrifices upside participation for income, and over long periods the total return usually lags the S&P 500 by a material margin, sometimes a wide one during strong bull markets. If you need the raw data without navigating the JPMorgan site, the JEPI investor relations page has a distribution history PDF that you can download. It covers every distribution since inception with the full tax breakdown. There is also a third-party site called ETFdb.com that maintains a decent historical table with monthly distribution amounts going back to launch, though the tax classification detail is thinner than the official source. For someone doing serious analysis, I would recommend pulling directly from the JPMorgan site and building your own table. A spreadsheet tracking monthly distributions, NAV, price, and the trailing yield calculation typically takes about twenty minutes to set up once you have the PDF open, and it saves you from relying on third-party sites that may lag behind the latest distributions or drop data mid-history during a restructuring.
The biggest limitation you should be aware of before using JEPI's dividend yield history as a planning tool is that the distribution amounts are inherently volatile. They are driven by option pricing, which depends on implied volatility, interest rates, and market direction. There is no guarantee that a nine percent trailing yield today will persist if the VIX drops to fifteen for an extended period. I have seen similar covered call ETFs where the distribution yield compressed from the high tens to the single digits within a year as the volatility environment shifted. JEPI has been more consistent than many of its peers because it uses a broader basket of S&P 500 names and writes calls across a wider range of expirations, but consistency does not mean stability. The yield will fluctuate, and any projection you make based on the last twenty-four months of history is almost certainly wrong for the next twenty-four months. For tax planning purposes, the return of capital component of the distribution is worth watching closely. A higher return of capital portion does not reduce your current tax bill, but it does lower your cost basis in the shares, which means more taxable gain when you eventually sell. I track the return of capital accumulation in a separate column in my spreadsheet because it compounds over time and can quietly turn a tax-deferred position into a sizable capital gains event years down the line. The fund has periodically returned a meaningful chunk of the distribution as return of capital, especially in lower volatility periods, so ignoring that line item is an easy mistake that catches people off guard at tax time.
Get the Full Details