Working Through Mini Practice Set 3 in Accounting
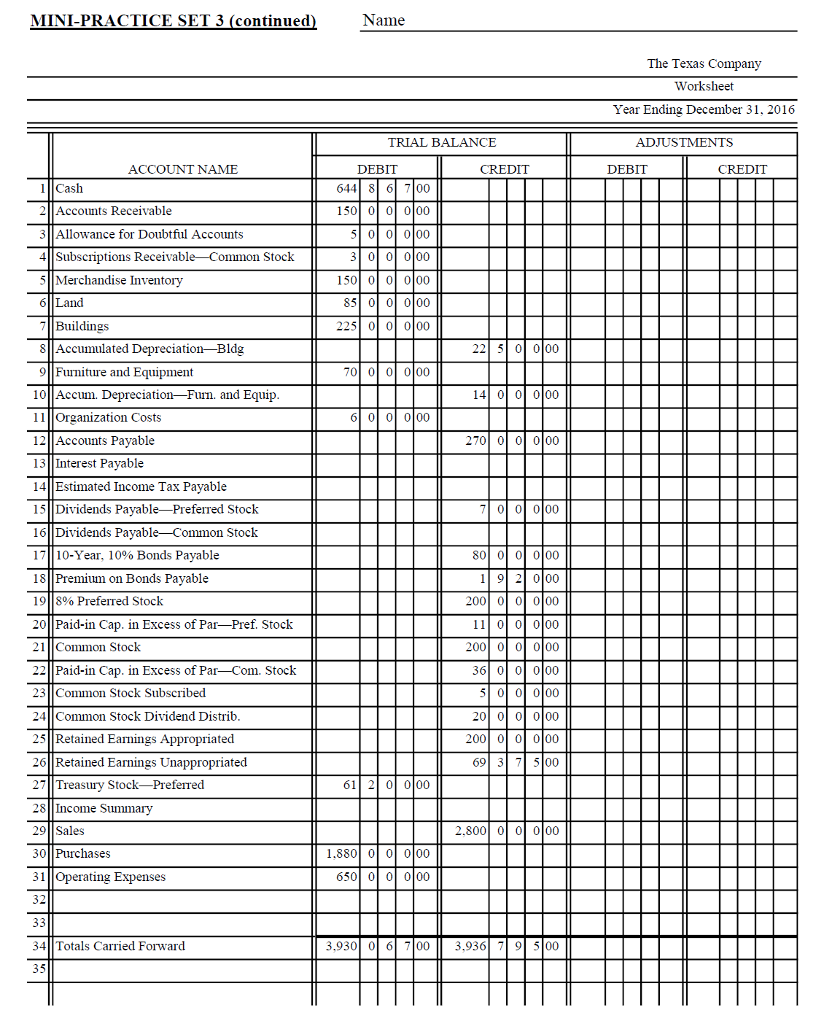
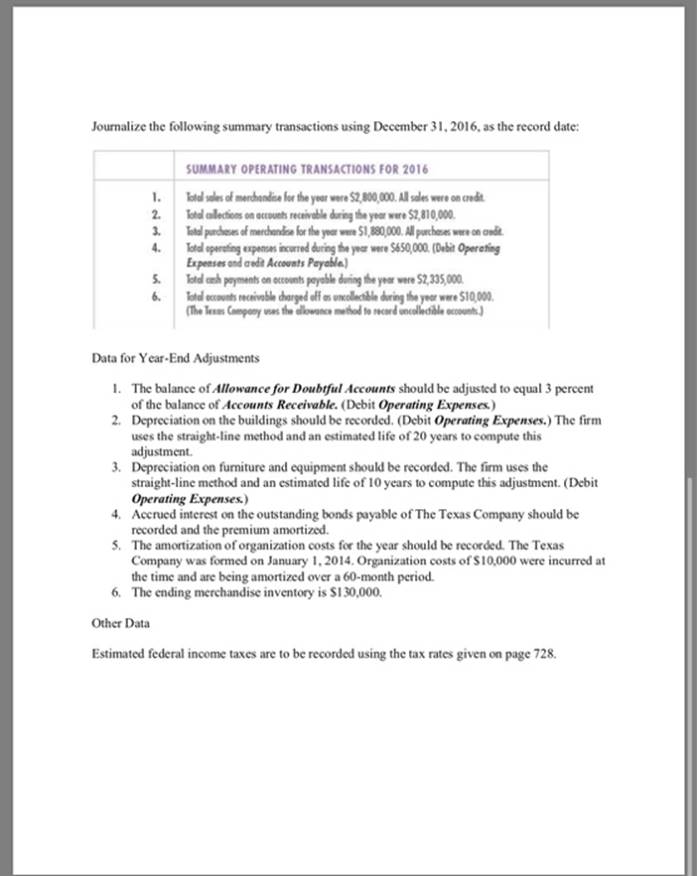
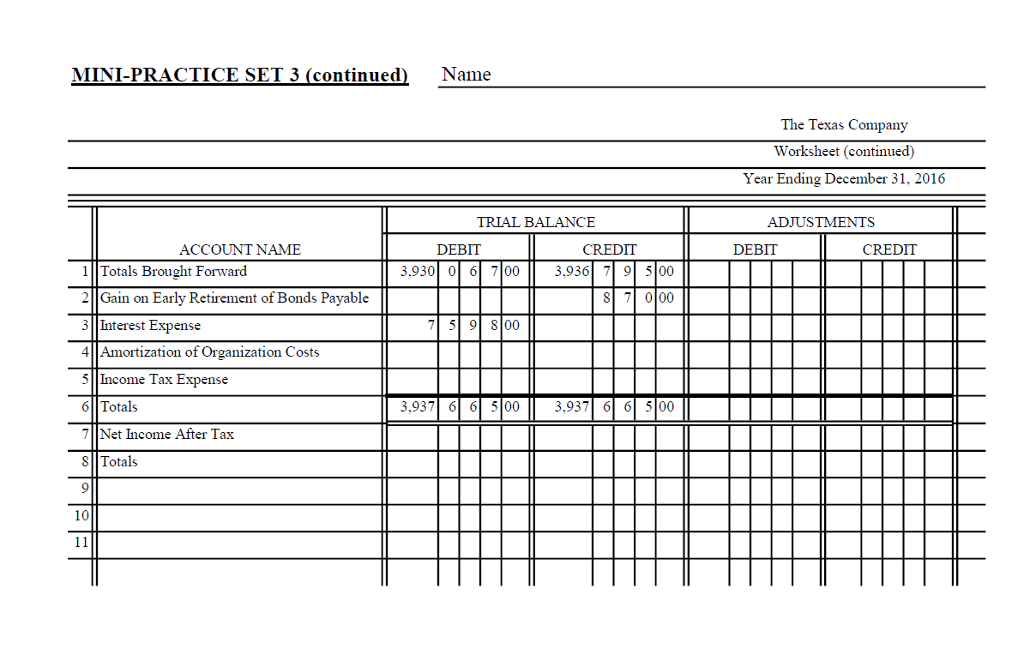
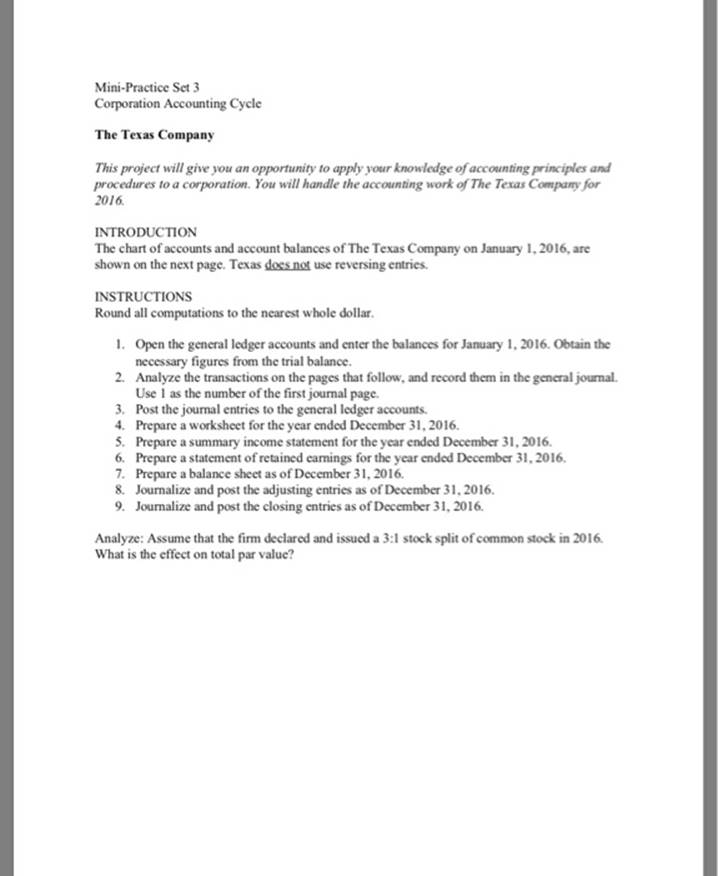
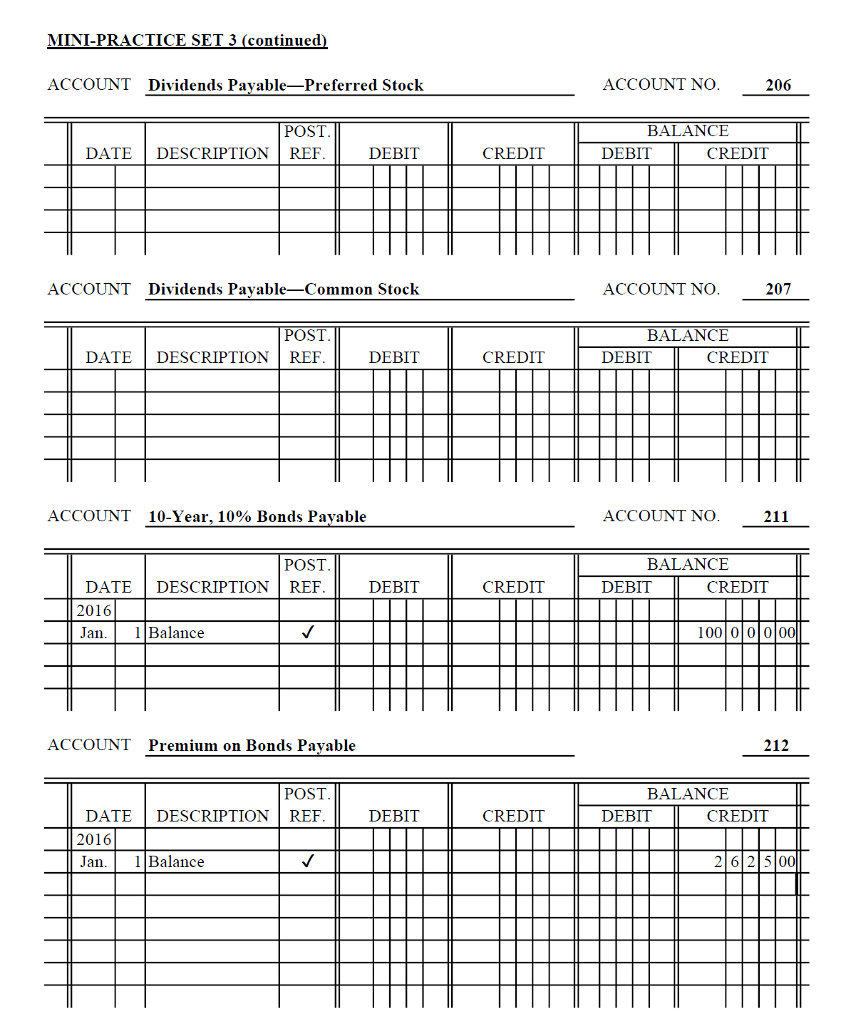
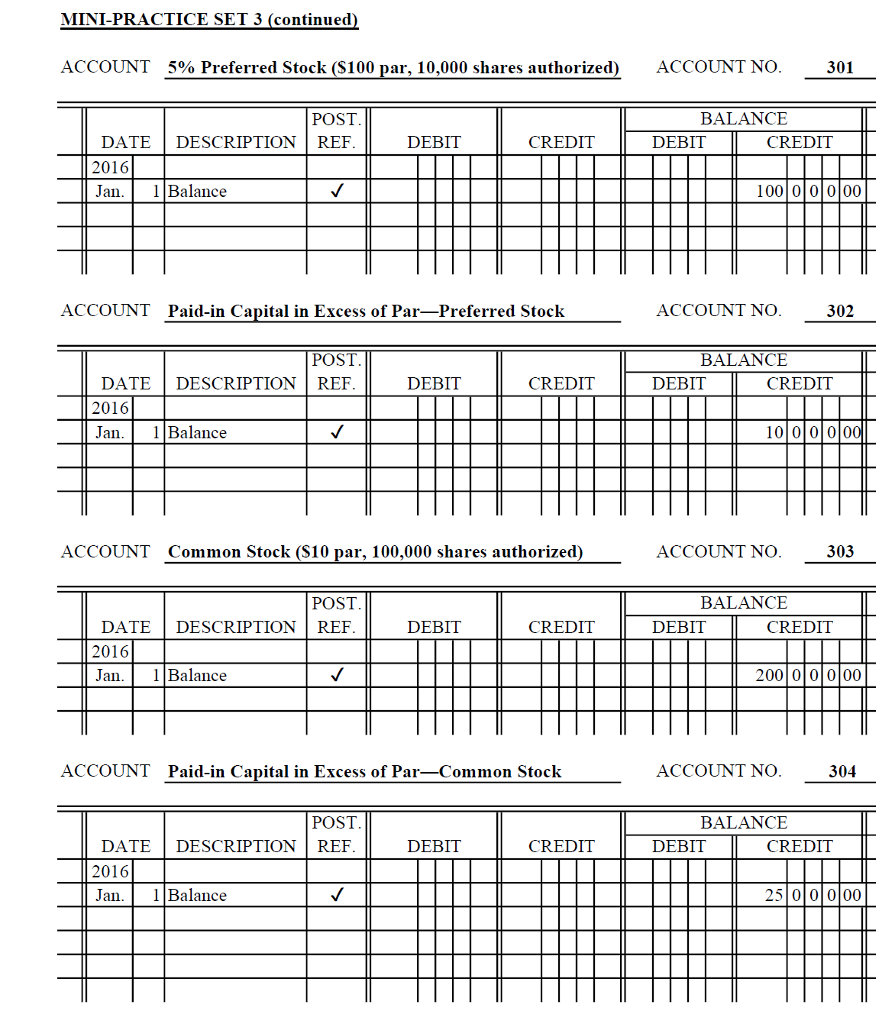
Mini Practice Set 3 Accounting Answers come up a lot when people are grinding through their accounting coursework or prep for certification exams. The set usually covers depreciation schedules, accruals, deferred revenue, and basic adjusting entries. It is straightforward stuff if you know the mechanics, but students tend to mess up the timing on accruals more than anything else. Here is what you are actually dealing with. The practice set gives you a series of business transactions for a fictional company over a single fiscal period. Your job is to record journal entries, post them to the general ledger, and prepare a trial balance that actually balances. That last part is where most people lose points. You do not need fancy software to do it by hand, but you do need to understand debits and credits without second-guessing yourself. I ran into a specific problem last year with a student who was stuck on Question 4. The transaction said the company received $6,000 in advance for a service that would be delivered evenly over six months. The question asked for the adjusting entry at the end of month two. A lot of people credit the full $6,000 to Service Revenue right away. That is wrong. The correct approach is to debit Unearned Revenue for $2,000 and credit Service Revenue for $2,000, leaving $4,000 still sitting in the liability account. The tricky part is that the problem did not explicitly tell you the monthly amount. You had to divide $6,000 by 6 first. Missing that step cost the student the entire point.
The workaround I used was to reframe the problem as a timeline. Draw a simple six-month bar, mark the revenue recognition evenly across it, and circle the portion that has been earned by month two. It takes ten seconds and removes most of the confusion around when to recognize revenue versus when cash is received. If you are looking for the actual answer key, many course instructors post Mini Practice Set 3 Accounting Answers on their learning management systems or share them through departmental channels. Some third-party sites host PDF versions, but those can be outdated or contain errors. I always recommend checking against your textbook's solution manual first if one exists, since different editions sometimes change the numbers in the transactions.
How to approach the set efficiently
The fastest way to get through Mini Practice Set 3 is to work in order and not skip the trial balance step. A lot of people jump straight to the financial statements without verifying the trial balance. If your debits and credits do not match, everything downstream is wasted effort. I usually spend about 45 minutes to an hour on the journal entries, 20 minutes on posting to the ledger, and another 15 minutes checking the trial balance. If it does not balance after 15 minutes of looking, the issue is almost always a transposition error or a single wrong entry that got carried forward. Redo the ledger from scratch in that case. It is faster than hunting for the mistake. Depreciation questions in this set typically use straight-line method. The formula is straightforward: (Cost minus Salvage Value) divided by Useful Life in years. One thing beginners miss is that salvage value is not always zero. If the problem states a salvage value of $500 on equipment that cost $5,000 with a five-year life, your annual depreciation is $900, not $1,000. Using the full cost as the depreciable base is a common error that throws off the entire schedule. Accrual entries are another place where people trip up. The key question is always whether the event has occurred but the cash has not yet moved, or whether cash has moved but the event has not occurred. Revenue earned but not yet billed is an accrued receivable. Cash received before service is performed is unearned revenue. Keep that distinction clear and you will handle the adjusting entries correctly.
Get the Full Details
Common pitfalls to watch for
The biggest issue with this practice set is the rounding differences that appear when calculations are done in stages. If you round the monthly depreciation to the nearest dollar at each step and then sum those rounded figures, you can end up off by a dollar or two compared to calculating the total annual depreciation and dividing evenly. Always carry at least two decimal places through intermediate steps and round only at the final answer. This is especially relevant for the partial-period depreciation questions that sometimes appear in this set. Another problem is mixing up the normal balance of accounts. Revenue accounts have credit balances. Expense accounts have debit balances. Asset accounts have debit balances. Liability and equity accounts have credit balances. If you are unsure about a particular account type, check it before recording the entry rather than guessing. Wrong sign errors are the hardest to find later. Some versions of Mini Practice Set 3 Accounting Answers include a bad debt expense question using the allowance method. The entry is straightforward: debit Bad Debt Expense and credit Allowance for Doubtful Accounts for the estimated percentage of accounts receivable. The counterintuitive part is that the actual write-off happens later and does not affect net income. It reduces Accounts Receivable and the Allowance account equally, leaving net realizable value unchanged. Understanding this sequence prevents confusion when the problem asks for the impact on the income statement versus the balance sheet.
When the standard approach does not work
There are scenarios where the typical textbook method falls apart. One example is when the problem includes a trade-in or exchange of asset that lacks commercial substance. The accounting treatment changes depending on whether a gain or loss is involved, and the general rule is more restrictive than what students usually learn early on. If you run into that situation, the safest move is to reference the specific section of your textbook or course material. The practice set may not cover it, and you will need to apply the broader standard. Another limitation is that practice sets like this one rarely cover the complexity of real-world multi-entity consolidations or lease accounting under current standards. They are designed for foundational understanding. If you need to go beyond the scope of this set, look for advanced problem sets that focus on lease classifications, revenue recognition under the five-step model, or consolidated financial statements. The bottom line is that Mini Practice Set 3 Accounting Answers represent a standard checkpoint in introductory accounting courses. They test whether you can handle the core adjusting entries without relying on memorized patterns. Work through them methodically, check your trial balance before moving forward, and pay attention to the details in the wording of each transaction. The answers will follow naturally if your entries are correct.