How Land Loans Actually Work
Land loans are not like mortgage loans. The payments can look okay on paper, but the terms punish you if you aren't paying attention to details most people miss. A standard mortgage has predictable monthly payments for 30 years. Land loans often require 20 to 50 percent down, carry higher interest rates, and have much shorter repayment periods. You could be paying off a parcel of land in 10 years instead of 30, and your monthly payment will reflect that compression. I recently worked with a contractor who used an online tool and got a payment estimate that was about $200 short per month. The calculator defaulted to a 30-year term because that is what most people search for, but his lender was offering a 15-year land loan at 9.75 percent. The correct payment using the standard amortization formula comes out to around $1,847 per month on a $200,000 loan. The tool showed him roughly $1,640 because it assumed a 6.5 percent rate over 30 years. That gap matters. It changed whether he could clear debt service on the property and still take on the construction loan later.
Using a Land Loan Payment Calculator Correctly
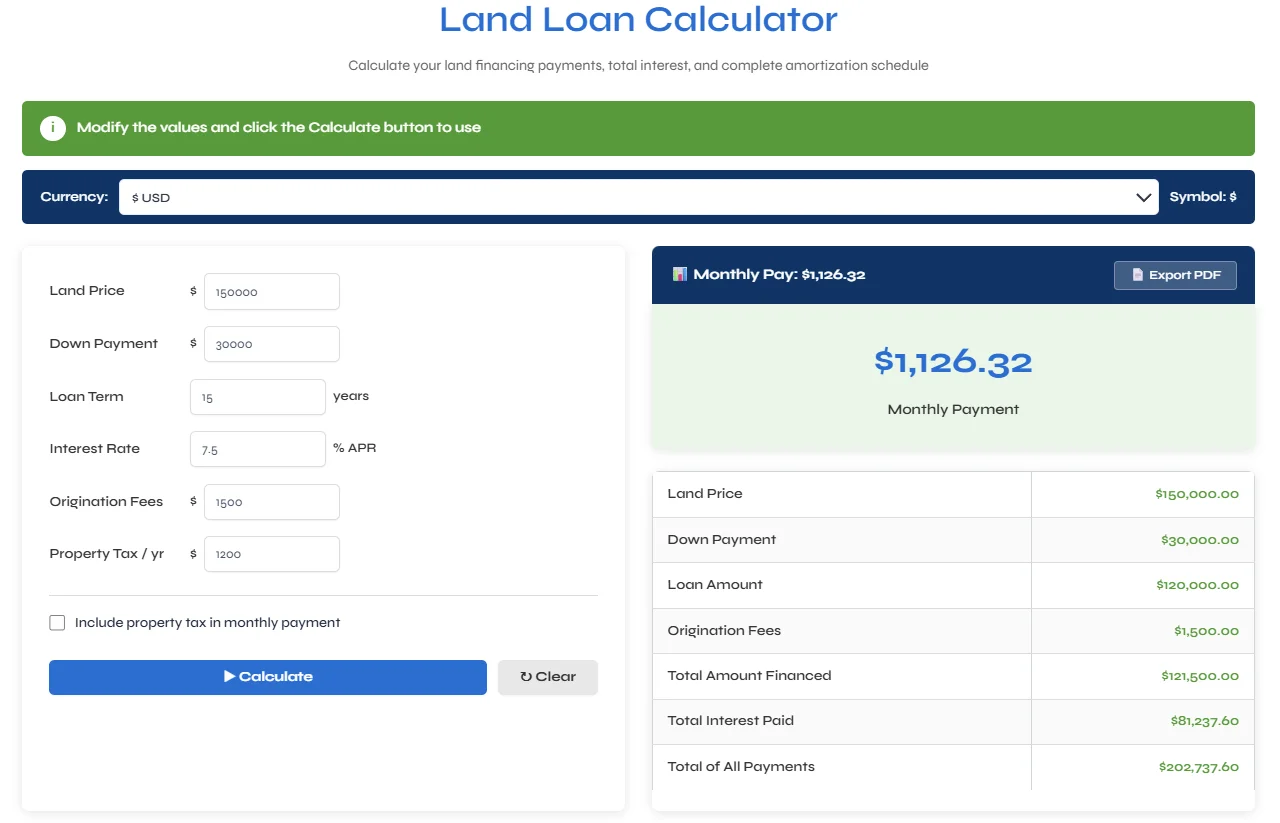
The basic formula behind any Land Loan Payment Calculator is the same one banks use for amortizing loans: M = P × [r(1+r)^n] / [(1+r)^n - 1] P is your loan amount after the down payment. r is your monthly interest rate, which means you divide the annual rate by 12. n is the total number of monthly payments over the life of the loan. You plug those three numbers in and you get your monthly principal and interest payment. Simple enough, but the inputs are where people make mistakes.
The most common error is treating raw land the same as a developed lot. Lenders see raw land as higher risk, so the rate is typically one to two percentage points above conventional mortgage rates. A second error is assuming the full purchase price is the loan amount. Most lenders want 20 to 50 percent down on unimproved land. If the property costs $150,000 and you put 30 percent down, your P is $105,000, not $150,000. Use the correct P or everything downstream is wrong.
Get the Full Details
What the Calculator Does Not Tell You
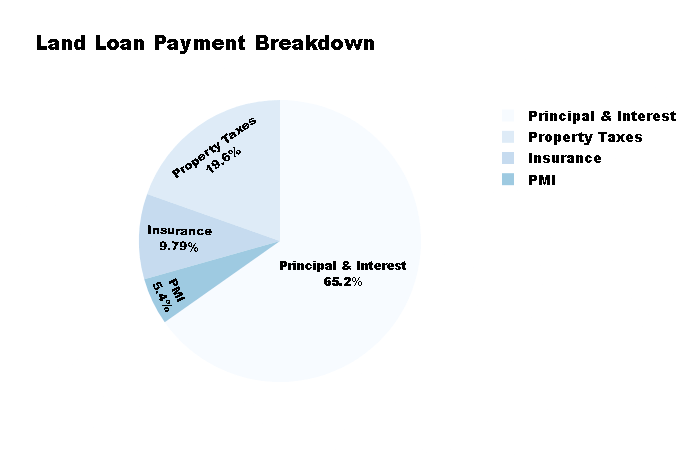
Payment calculators only show principal and interest. They do not include property taxes, insurance, or any lender fees tied to land loans. On raw land, property taxes can still come due even if the lot sits empty. Some counties bill annually, some semi-annually. If your monthly payment estimate is $1,200 but the tax bill runs $3,600 a year, your actual monthly obligation is closer to $1,500. That is a 25 percent jump and it can break a pro forma. Another thing the calculator will not surface is the balloon payment structure. Some land loans are written as 5/1 or 7/1 adjustable-rate products where the payment resets after a few years, or they require a lump-sum payoff at the end of the term. I had a client in central Texas who got a five-year balloon note at 8.5 percent. The monthly payment looked manageable, but he needed to sell the land or refinance into a construction loan before the balloon hit. He did not have a timeline on the development, so the loan became a problem fast. If your calculator does not let you input balloon terms, it is giving you an incomplete picture. Interest-only land loans also exist. Some lenders offer pure interest payments for a set period, usually 12 to 24 months, before principal kicks in. During the interest-only phase the payment is dramatically lower, but once the amortization starts the monthly number jumps because the same balance is being paid down over a shorter window. Run both scenarios through your calculator before you commit. The payment shock is real and it catches people off guard.
When This Approach Fails
A land loan payment calculator works fine for straightforward amortizing loans with standard terms. It breaks down when you are dealing with seller financing that has irregular payment schedules, leasehold interests, or loans tied to bridge or construction financing where disbursements change the outstanding balance monthly. In those cases you need a custom amortization schedule built in a spreadsheet or from your lender, not a generic calculator. If the land has environmental issues, zoning restrictions, or conditional use requirements that affect the timeline, the payment calculator cannot account for the delay cost. Time is money on a carrying loan. Every month you sit on the parcel with a payment due and no revenue, you are burning cash. Factor in at least six months of carrying costs beyond the loan payment if you are doing a flip or a hold strategy. That means budgeting for taxes, insurance, and possibly HOA fees on top of the monthly note payment.
Practical Numbers
Here is a realistic example. Purchase price of $180,000. Down payment of 35 percent brings the loan amount to $117,000. Interest rate of 10.25 percent annual. Term of 15 years. Monthly payment works out to approximately $1,298. Add property taxes of roughly $2,400 per year, divided by 12 for $200 monthly. Insurance and any HOA might add another $50 to $100 depending on the county. Your actual monthly out-of-pocket lands around $1,550 to $1,600, not the $1,298 the calculator shows. Another scenario: same $180,000 purchase, 50 percent down because the land is raw and unimproved. Loan amount drops to $90,000 at 11 percent over 10 years. Monthly payment comes to about $1,237. The higher rate and shorter term push the payment close to the 15-year example despite a smaller loan balance. That is the trade-off with land loans. You either pay more upfront or you pay more every month. There is not a free lunch.
Alternative Paths
If the monthly numbers do not pencil out, consider seller financing. Some sellers will carry a note at a lower rate with flexible terms tailored to your situation. It is less formal, but it can reduce your upfront cash requirement and give you breathing room. Another option is a ground lease if you only need temporary use of the parcel for a construction project. A ground lease avoids the loan entirely during the build phase, then you convert to ownership if the deal structure supports it. Construction loans are a different animal altogether. If you plan to build within a year, skipping the standalone land loan and going straight to a construction-to-permanent loan can save you from double closing costs and the payment shock of switching loan types. The qualification bar is higher and you need a builder contract in hand, but the math often works out better over the full timeline. Bottom line is that the calculator gives you a starting point, not a finish line. Run the numbers with your actual rate, your actual term, and your actual down payment. Then add the carrying costs on top. If the total still feels tight, talk to a lender before you make an offer. Getting pre-approved with real terms beats guessing at payments and discovering too late that the numbers do not hold up.