How to Build and Use a Land Mortgage Payment Calculator Without Getting Tricked by the Numbers
Land mortgages are a pain because they work differently than standard home loans. The down payment is usually higher, the rates are higher, and some lenders won't even finance raw land at all. When you sit down to figure out what your monthly payment actually looks like, the basic formula is the same one banks use for everything else — principal and interest — but the inputs you plug in are where things get messy. A Land Mortgage Payment Calculator is just a tool that takes your loan amount, your interest rate, and your loan term and spits out a monthly payment. That sounds simple enough, but the reason people need one is because the inputs are not straightforward with land. You might have a 30% to 50% down payment requirement. Your interest rate could be two to three percentage points above what you would get on a house. And your loan term might only be five to twenty years instead of thirty, which means the payment is much steeper per month than you expect. The formula behind it all is:
M = P × [r(1+r)^n] / [(1+r)^n – 1] P is your principal loan amount after the down payment. r is your monthly interest rate, which means you take the annual rate and divide by 12. n is the total number of payments, so multiply your loan term in years by 12. If you put all of that into a spreadsheet or a calculator, you get the principal and interest portion. Property taxes and insurance are extra and depend entirely on your location and lender requirements. I spent about three hours once trying to reconcile a land loan quote from a credit union against what my own calculator showed, and the difference was about forty-two dollars a month. Turns out the credit union was amortizing based on a 360-day year with a thirty-day month, which is their internal convention, while my calculator was using standard monthly compounding. The gap narrowed when I adjusted the day-count convention, but it was annoying to debug. If you are cross-checking a lender's number against a calculator, make sure you are both using the same day-count method before you assume the lender made an error.
How to Actually Calculate It Step by Step
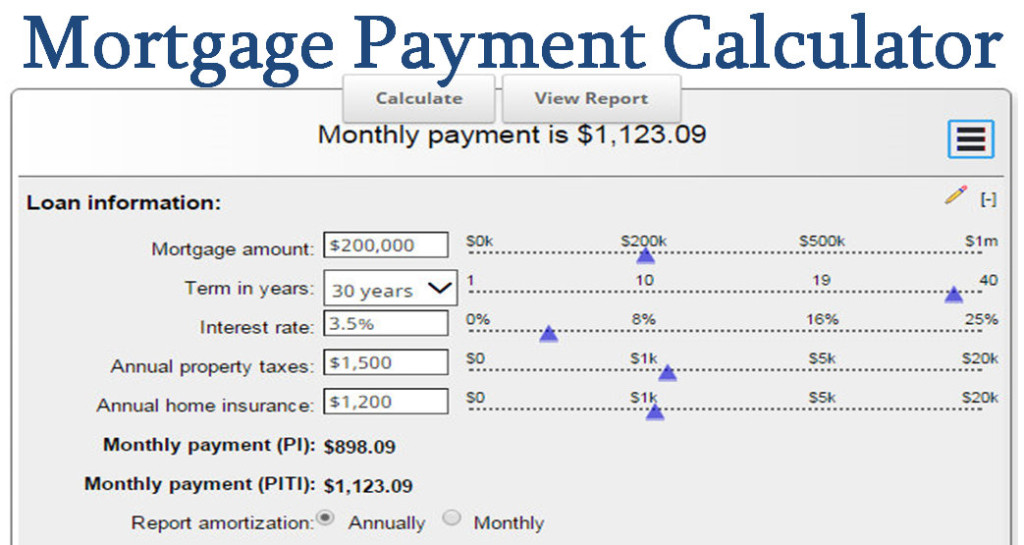
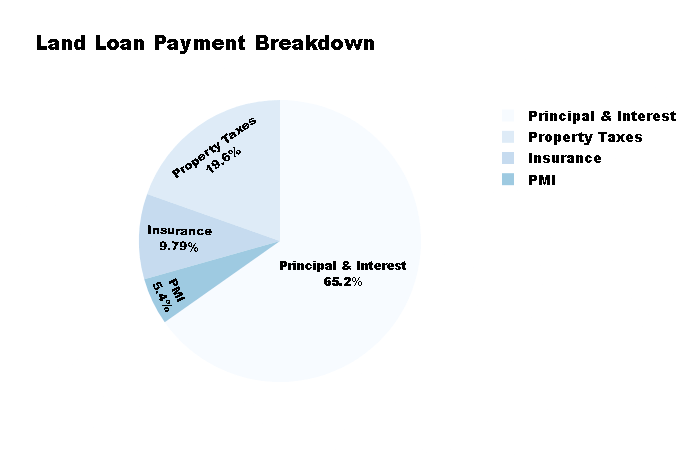
Let me walk through a real example so you can see what happens when you plug in realistic numbers. Say you are buying a piece of vacant land for one hundred twenty thousand dollars. The lender requires forty percent down, so your down payment is forty-eight thousand dollars and your principal is seventy-two thousand dollars. The annual interest rate is eight point five percent, which gives you a monthly rate of about zero point seven zero eight three percent. The loan term is fifteen years, which means one hundred eighty payments. When you run that through the formula, your monthly principal and interest comes out to roughly six hundred forty-eight dollars. Add in property taxes that might run around two hundred fifty dollars a month and homeowner's insurance if the lender requires it, and your total monthly obligation climbs to about nine hundred dollars. That is already higher than a comparable mortgage on an actual house would be, even though the property value is lower. Here is something people consistently miss: the payment you calculate with a Land Mortgage Payment Calculator is only the principal and interest piece. It does not account for impounds, escrow, mortgage insurance, or the fact that some land loans are structured as open-end loans that let you draw against equity later. If you are budgeting for actual cash outflow, you need to add those layers on top yourself. A calculator that only shows P&I will make your payment look smaller than it actually is, and that gap can catch you off guard.
Get the Full Details
Another thing that trips people up is balloon payments. Some land loans are structured as five-year balloons with a fifteen-year amortization schedule. The monthly payment looks reasonable because it is spread over fifteen years, but at the end of five years you owe the entire remaining balance. I worked with a client who saw a payment of five hundred sixty dollars a month on a sixty thousand dollar land loan and assumed that was the full picture. The balloon came due and he did not have the liquidity to refinance. Now he is carrying a bridge loan at twelve percent until he can sell the parcel. Always confirm whether your loan is fully amortizing or has a balloon before you trust the calculator output.
Why Standard Mortgage Calculators Are the Wrong Tool for Land
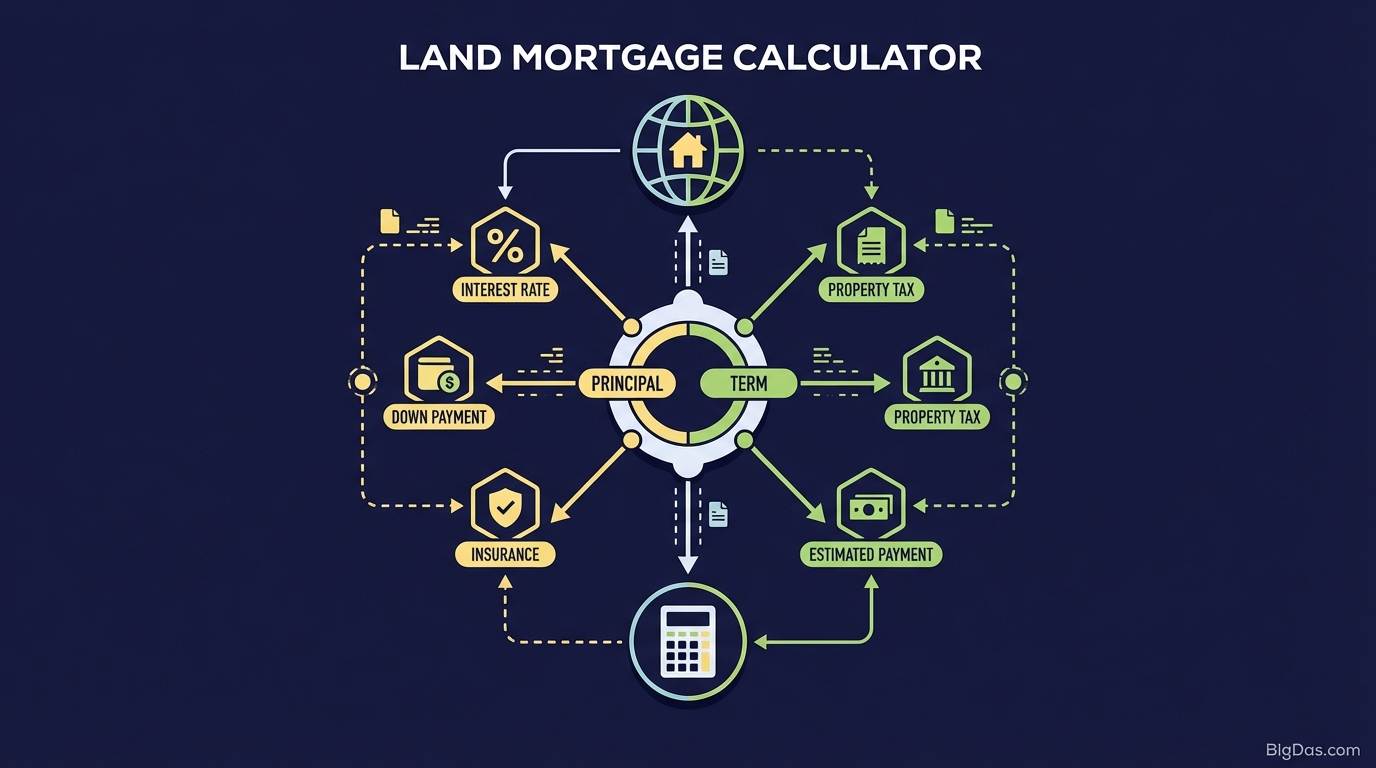
You will find plenty of free calculators online that are built for standard home mortgages. Those assume a twenty percent down payment, a thirty-year term, and rates that reflect conventional financing. If you feed land loan numbers into one of those, the output will be misleading. The payment will look lower than it actually is because the assumed term is longer and the assumed rate is lower. You need a calculator that lets you input the actual parameters your lender is offering, or you need to build your own in a spreadsheet where you control every variable. Building your own is straightforward. Put your loan amount in one cell, your annual rate in another, and your term in years in a third. Use the PMT function in Excel or Google Sheets with the rate divided by twelve and the term multiplied by twelve. Format the result as currency. Then build a second section for estimated taxes, insurance, and any HOA or special assessment fees. That two-section layout gives you both the contractual payment and the realistic total monthly cost in one view. If you want something you can download and use offline, the spreadsheet approach is honestly better than any web-based calculator. You can save it, tweak it when your rate changes, and share it with your lender to ask pointed questions instead of guessing. I keep one template that I reuse for every land deal, and it cuts the analysis time from about twenty minutes down to under five because I am not hunting for the right fields on a website each time.
Where the Calculator Breaks Down and What to Do Instead
The biggest limitation is that these calculators assume the loan will perform exactly as written. In practice, land loans rarely do. Values can drop if zoning changes go against you. Development costs can blow past estimates and eat into your ability to pay. Lenders can call loans due if you violate covenants, though that is less common than people fear with properly documented loans. The calculator will never tell you about any of that. So here is what you do instead: take the payment the calculator gives you and stress it. Run the scenario where your rate jumps two points, where your term shortens because of a refinance penalty, where your property tax assessment doubles after a change in land use. If the numbers still work in those scenarios, you are in a reasonable position. If they do not, you need a bigger down payment or a different loan structure before you close. Also keep in mind that not all land is treated the same. Raw land with no utilities and no road access is riskier than improved land with existing infrastructure. Vacated land gets worse terms. Agricultural land sometimes qualifies for different programs with longer terms and lower rates. A calculator cannot tell you which category your parcel falls into. That part depends on your local assessor's office and your lender's underwriting guidelines. Spend time on that classification before you bother with the payment math, because it changes everything downstream.