Computing Area Under a Curve With Rectangles
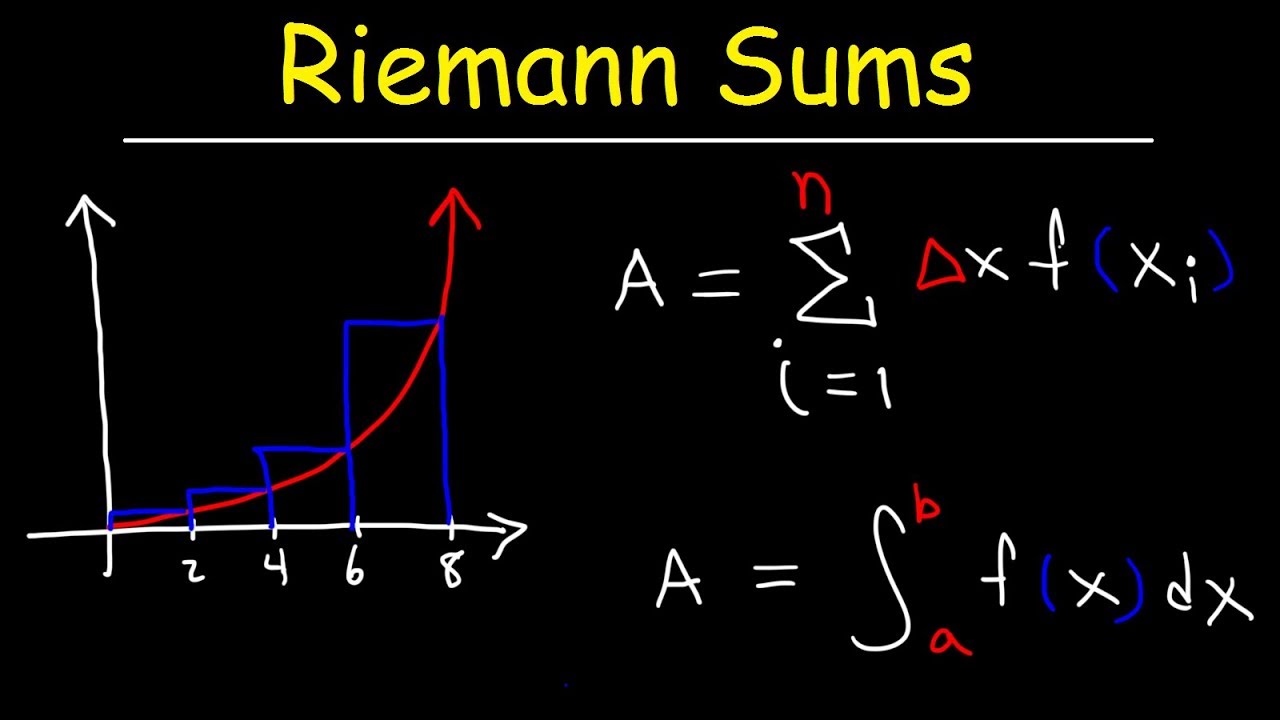
I remember the first time I tried to integrate a messy function by hand on a midterm and ended up with 47 rectangles drawn on graph paper. It took me over an hour. The left endpoint method is the simplest numerical integration approach you can use, but it has specific failure modes that most textbooks don't emphasize early enough. Let me walk through what you actually need to know before you start calculating. The Left Riemann Sum Formula works by dividing the interval [a, b] into n equal subintervals and using the function value at the left endpoint of each subinterval to determine the height of a rectangle. The width of every rectangle is x = (b - a) / n. You then sum up the areas: L_n = from i=0 to n-1 of f(x_i) · x, where x_i = a + ix. Here is a concrete example. Let's approximate the integral of f(x) = x² from 0 to 3 using n = 6 subintervals. First, x = (3 - 0) / 6 = 0.5. The left endpoints are 0, 0.5, 1, 1.5, 2, and 2.5. You evaluate f at each: 0, 0.25, 1, 2.25, 4, and 6.25. Multiply each by 0.5 and add them up: 0.5(0 + 0.25 + 1 + 2.25 + 4 + 6.25) = 0.5(13.75) = 6.875. The exact integral of x² from 0 to 3 is 9, so this is off by about 1.125. With more subintervals the gap shrinks, but the direction of the error matters.
Why the Left Riemann Sum Formula Often Underestimates
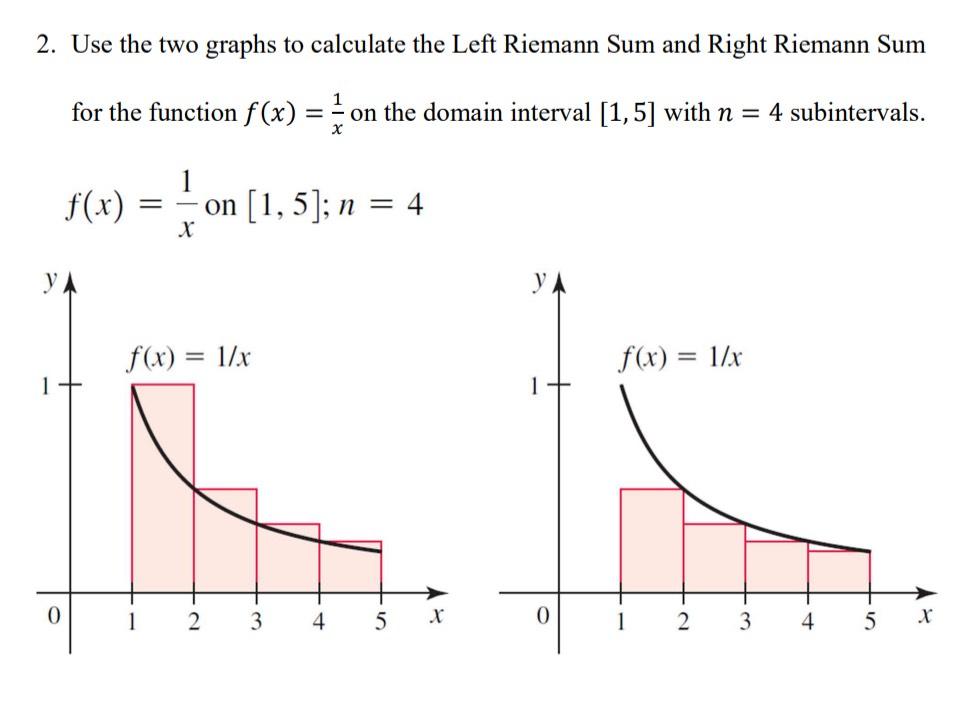
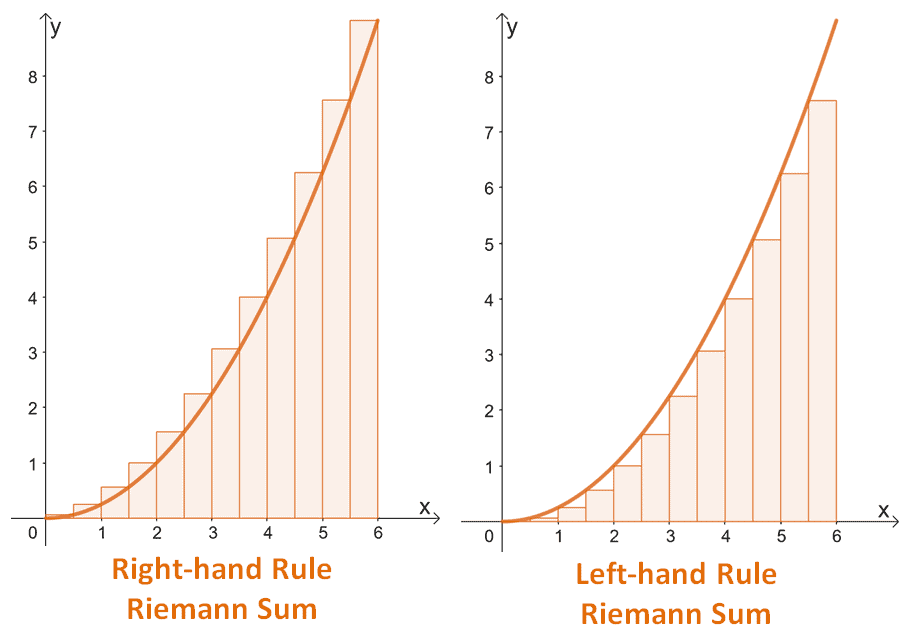
For an increasing function, the left endpoint method will always give an underestimate because every rectangle falls below the curve. For a decreasing function, it overestimates. This is the basic behavior, but here is something that trips people up repeatedly: the error does not simply halve when you double the number of subintervals. The global error for the left Riemann sum scales with 1/n, meaning to cut the error in half you need twice as many rectangles, not four. Compare that to Simpson's rule, which scales with 1/n. If you're working with a smooth function and need accuracy, the left sum is genuinely inefficient for anything beyond rough estimation. I ran into a real problem a few years ago while building a MATLAB script to approximate the integral of sin(x²) from 0 to 2. The function oscillates and the oscillations get tighter as x approaches 2. Using the left Riemann sum with n = 1000 gave me an answer that was nowhere near the known value. The issue wasn't that the formula was wrong — it was that the sampling was missing the peaks of the oscillation entirely. My workaround was to switch to adaptive subdivision: I split the interval into regions where the function is relatively flat, then used much finer partitions only where the curvature spiked. This cut computation time dramatically while keeping the error under control. Another pitfall that isn't obvious at first: if your function has a vertical asymptote or a discontinuity inside the interval, the left Riemann sum will produce garbage and you won't immediately know why. I once forgot to check the domain of a rational function before applying the method and got a finite number back. It was completely wrong, but the arithmetic itself was correct, which made debugging slow.
When to Use It and When Not To
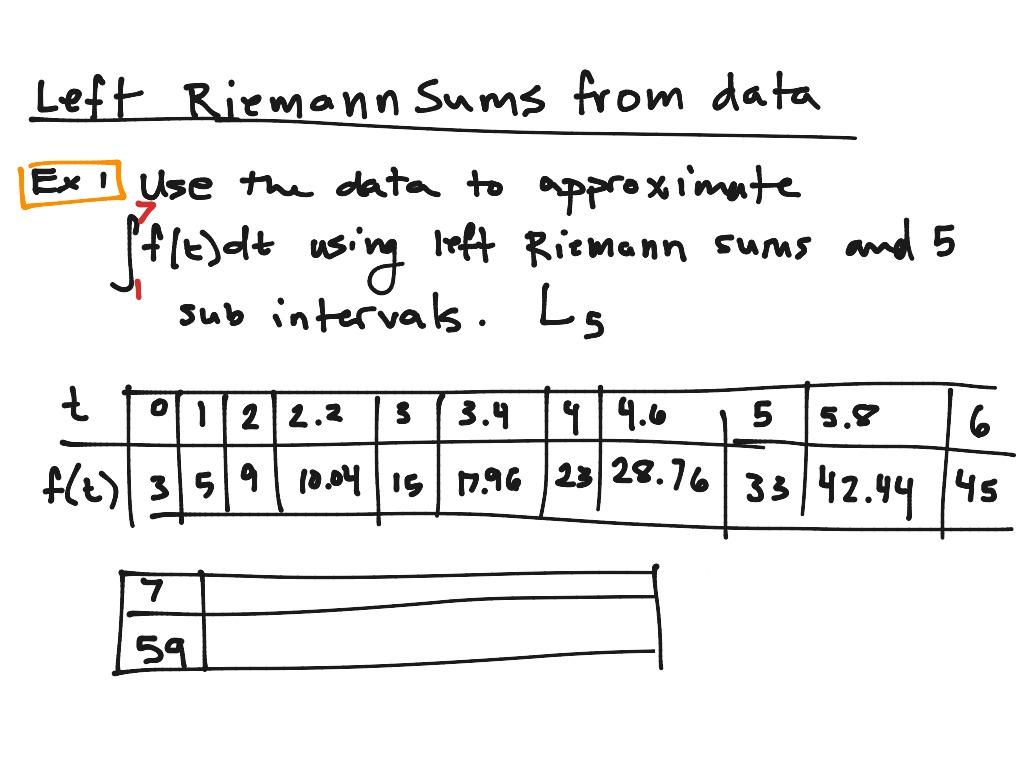
The left Riemann sum is useful when you need a quick, rough approximation and the function is well-behaved — no sharp turns, no asymptotes, nothing pathological. It is also the standard starting point for teaching numerical integration because the logic is transparent. But if you need precision, switch to the trapezoidal rule or Simpson's rule. The trapezoidal rule over the same interval with n = 6 in my earlier example would give 8.375 instead of 6.875, much closer to the true value of 9. Even the midpoint rule would have outperformed the left endpoint sum by a significant margin. For functions given as discrete data points rather than closed-form expressions, the left sum is perfectly reasonable since you don't have the luxury of choosing evaluation points strategically. In that case, you just take the data as it is and multiply each value by the step size. That is about as clean as it gets.
Get the Full Details