What actually happens when you fill out a Letter Of Attorney Form
A power of attorney form is a legal document where one person (the principal) gives another person (the agent or attorney-in-fact) the authority to act on their behalf. That's the textbook definition. In practice, it's usually more messy than that because every jurisdiction has slightly different requirements, and the moment you step outside a standard form, things get complicated fast. I've seen people waste weeks trying to use a generic template from the internet for a transaction that required state-specific statutory language. The bank or court will reject it without much explanation. You end up chasing a notary who isn't certified in the right way, and you're back to square one.
The basics of a Letter Of Attorney Form
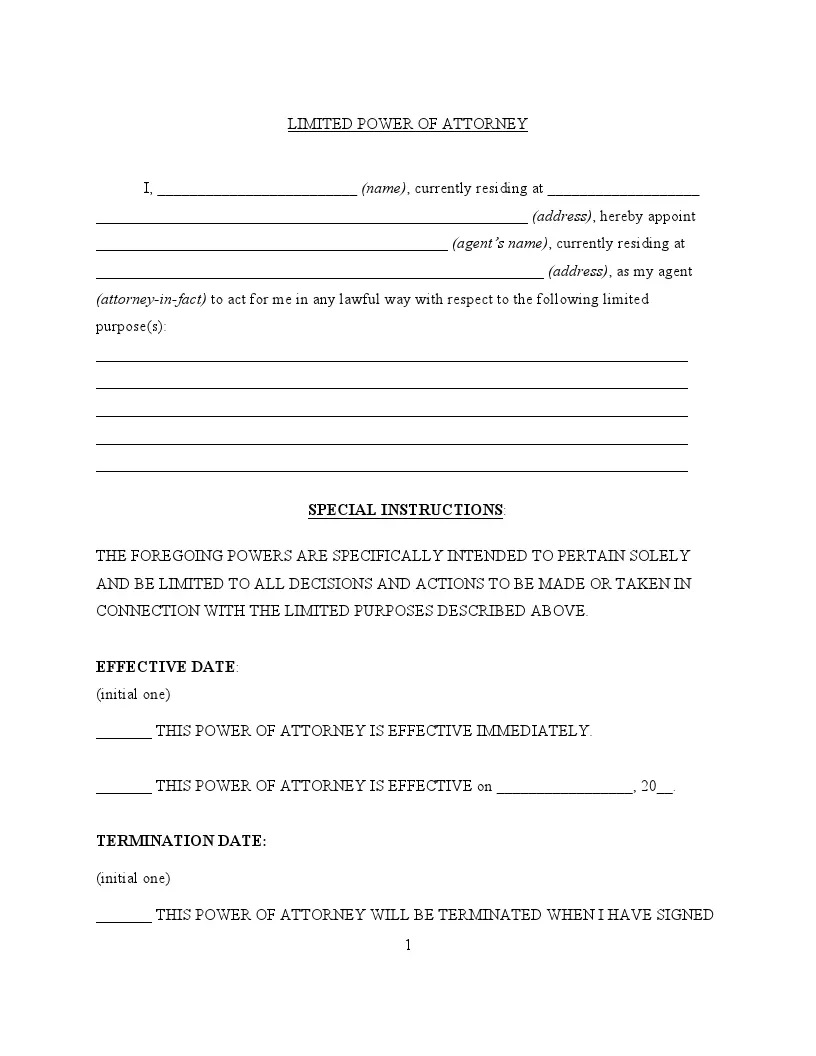
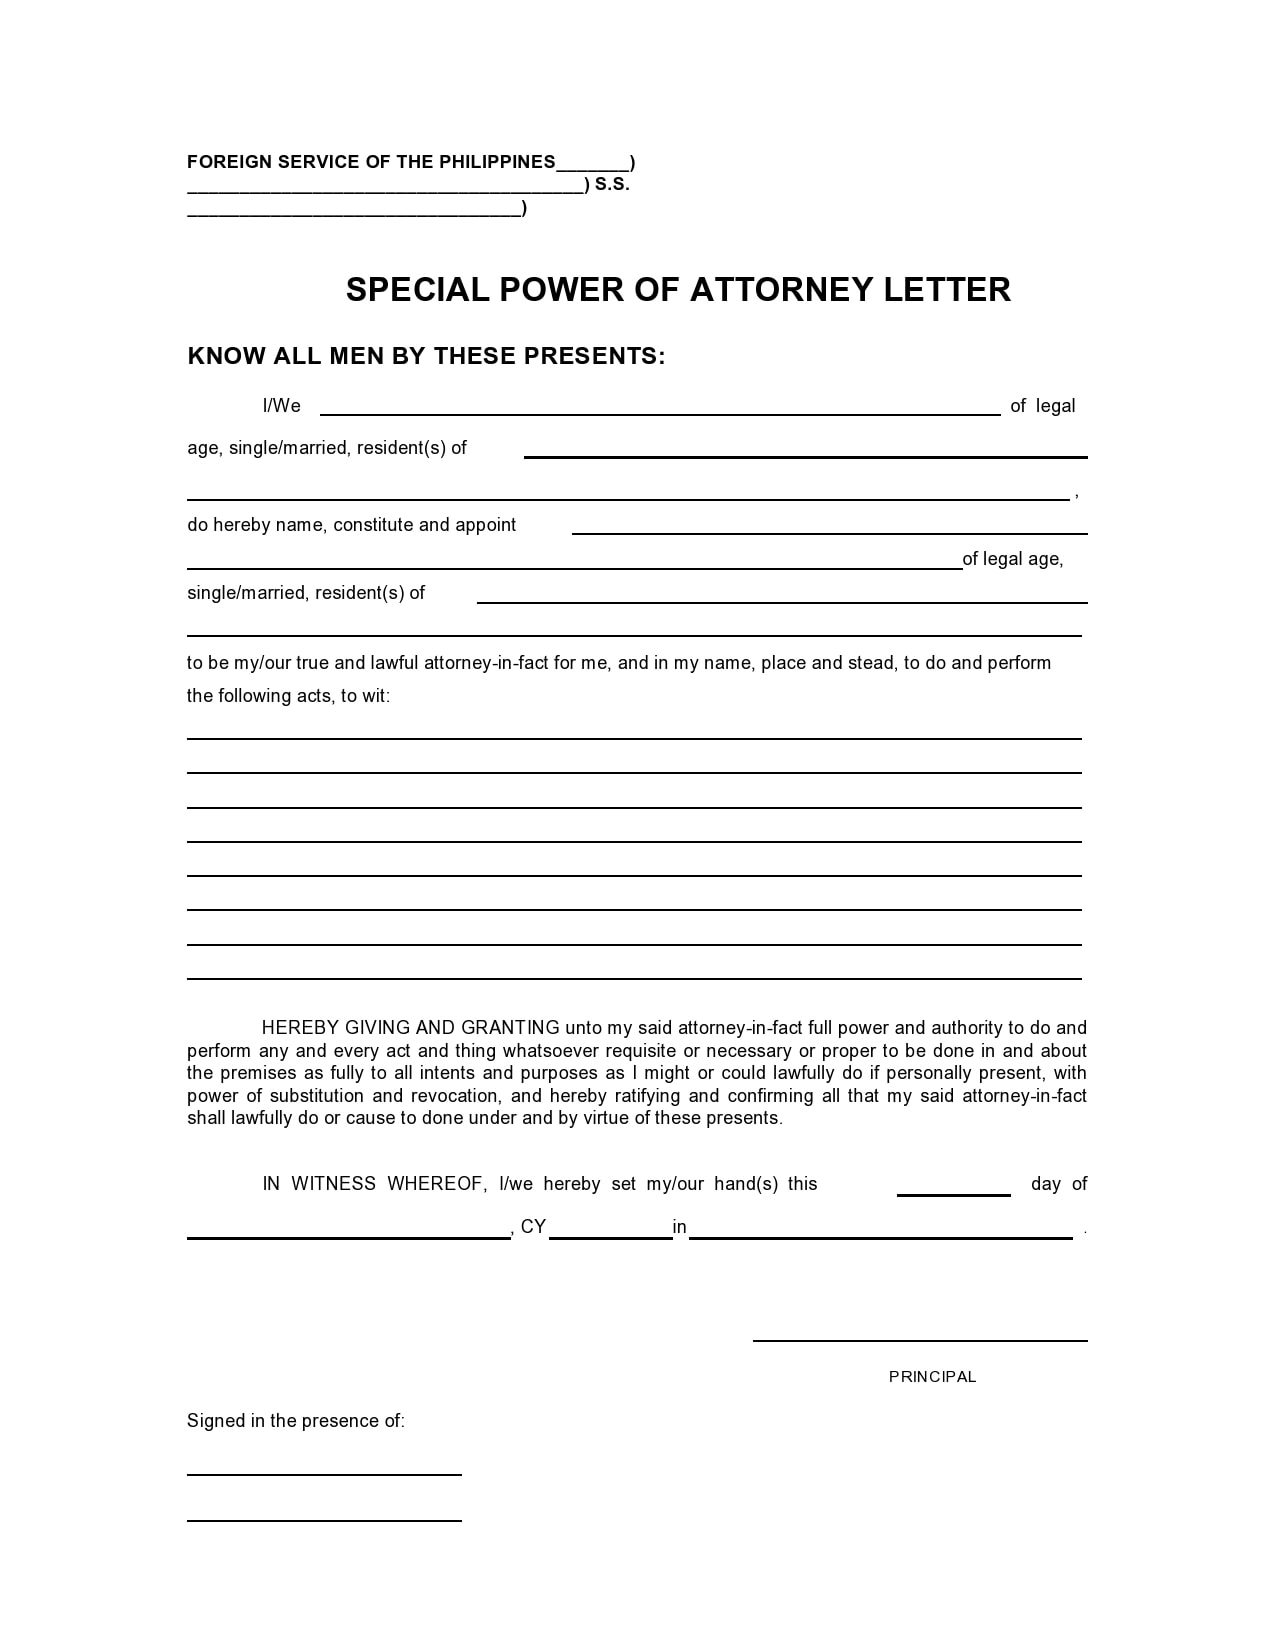
There are generally two main types you'll run into. A general power of attorney gives broad authority to handle financial and legal matters. A limited or special power of attorney restricts the agent to a specific task or time window. Most people need the limited version for something like closing on a property while they're overseas. The general version is usually reserved for estate planning situations where someone might become incapacitated. There's also the durable variation, which means the authority survives the principal's incapacity. Without that durability clause, the document becomes useless the moment someone needs it most. I see this mistake constantly. People draft a standard POA for a parent who is already showing signs of cognitive decline, only to find out it's void the second a doctor declares them incapacitated. The workaround is simple: make sure the document explicitly states it remains in effect during incapacity, or use the term "durable power of attorney" if your state requires it. A properly executed Letter Of Attorney Form needs several core elements. The principal's full legal name and address. The agent's full legal name and address. A clear description of what powers are being granted. The effective date, or whether it takes effect immediately or only upon a triggering event like incapacity. Your signature, notarization, and in many states, witness signatures. Some jurisdictions require the document to be recorded with the county clerk if it involves real estate transactions.
How to actually get it done without wasting time
Start by checking whether your state has a statutory form. Many states publish official templates that courts and institutions are programmed to accept without question. Using the state-specific form cuts the rejection rate dramatically. If you're dealing with a financial institution, call them first and ask if they have a preferred form. I once had a client try to use a valid out-of-state POA at a regional bank, and they refused it flat out. The bank's compliance department would not budge. Switching to their internal form resolved it in two days instead of three weeks of back and forth. Be specific about the powers you're granting. General language like "my agent may handle all my financial affairs" sounds comprehensive but can actually create problems. Institutions prefer to see enumerated powers. List them out. Selling real estate. Managing bank accounts. Filing taxes. Making healthcare decisions if applicable. The more specific you are, the less likely anyone is to push back on the document's validity. Notarization is almost always required. Some states also require witnesses. Check your local requirements before you sign anything. A document that's notarized but missing witnesses will be rejected in jurisdictions that require both. This is one of those details that nobody mentions until you're already in trouble.
Get the Full Details
Edge cases and what I've learned the hard way
Here's a specific situation that cost me considerable time and frustration. A client needed a Letter Of Attorney Form to sell a rental property in Florida while he was living in New York. The Florida property appraiser's office accepted the out-of-state notarization without issue. But when he tried to record the deed at the county recorder's office, they rejected it because the document didn't include a Georgia-specific acknowledgment language for the notary certificate. The notarization itself was valid, but the wording on the notary block didn't match Florida's statutory requirements for out-of-state executions. The fix was straightforward but not obvious. I had the client reprint the document, have the notary re-complete it using language that referenced Florida law specifically, and then resend it. It added about four days to the timeline and roughly sixty dollars in notary and courier fees. The lesson here is that when dealing with real estate in a different state, the receiving agency's requirements govern, not the state where the document is being signed. Another thing people routinely misunderstand is the difference between an agent's authority and the third party's obligation to accept it. Just because you have a valid power of attorney doesn't mean every institution has to honor it immediately. Banks in particular can be slow to accept out-of-state documents or older forms. They have compliance departments that audit these things, and they may request an opinion letter from your attorney or ask for the original document to be re-notarized within the last ninety days. Some institutions have their own internal forms they insist you complete alongside the legal POA. This isn't necessarily obstruction. It's risk management on their end. But it will slow you down if you're not expecting it.
Limitations you should know about
A power of attorney is not a substitute for proper planning in every scenario. It cannot authorize someone to make healthcare decisions unless it's specifically a healthcare proxy or medical power of attorney, which is a separate document in most states. It cannot override a trust. It cannot be used after the principal dies, at which point the executor or administrator of the estate takes over. And if the principal revokes the document while mentally competent, it's gone, regardless of whether the agent has already started acting under it. One more thing that catches people off guard. If the agent named in the Letter Of Attorney Form is also the beneficiary of the principal's estate, some institutions will scrutinize the document more heavily. They may require additional proof that the principal understood the arrangement and wasn't under undue influence. This is especially relevant if the principal is elderly or was recently diagnosed with a condition affecting cognition. Having an independent attorney witness the signing or prepare a capacity evaluation can prevent those headaches later.
Letter Of Attorney Form common pitfalls to avoid
Using an outdated form is probably the single most common problem. Some states updated their statutory POA forms within the last decade, and institutions are increasingly refusing older versions. Check the copyright date on whatever template you're using. If it's more than five years old, verify with the relevant agency whether they still accept it. Another frequent issue is naming a successor agent without specifying the order of succession. If your primary agent can't or won't serve, the document may become inactive unless you've named an alternate. I've seen multiple cases where the primary agent moved abroad and couldn't practically act, but no successor was named, leaving the principal's affairs in limbo. Finally, don't treat a POA as a one-and-done document. Life changes. Marriages, divorces, deaths of agents, changes in state residency. Review the document every few years or whenever a major life event occurs. Update it if necessary. An old POA naming an ex-spouse as agent is not just inconvenient, it's a liability.