How Extra Principal Payments Actually Change Your Loan
Most people have no idea what happens to their amortization schedule once they start throwing extra money at the principal. They see a bar chart on some website showing interest savings and call it a day. That's usually fine, but if you're actually planning to make strategic prepayments or you need to show someone — a lender, a spouse, an accountant — exactly what your modified schedule looks like, generic calculators fall apart fast. The fundamental issue is that standard amortization assumes a fixed payment over a fixed term. Once you introduce irregular extra principal payments, you're no longer working with a standard annuity formula. You're working with a series of uneven cash flows, and the math has to shift accordingly. This is why most off-the-shelf tools either ignore extra payments entirely or give you rounded estimates that drift from reality over time.
Building a Loan Amortization Calculator With Extra Principal Payments
Start with the monthly interest rate, which is your annual rate divided by 12. Not 360. Divided by 12. People mess this up constantly when they're trying to reverse-engineer something, and then the whole schedule is off by a fraction that compounds over years. The base formula for a standard payment is straightforward: PMT = P × [r(1+r)^n] / [(1+r)^n - 1]
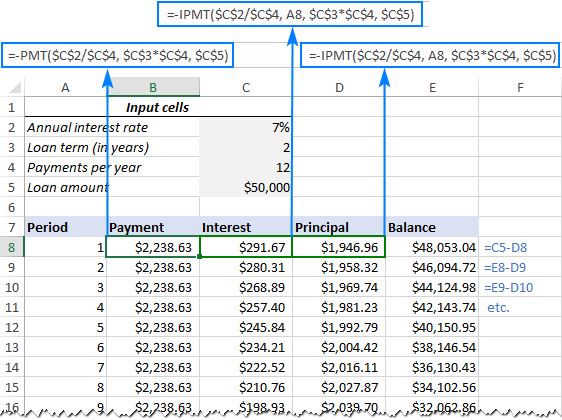
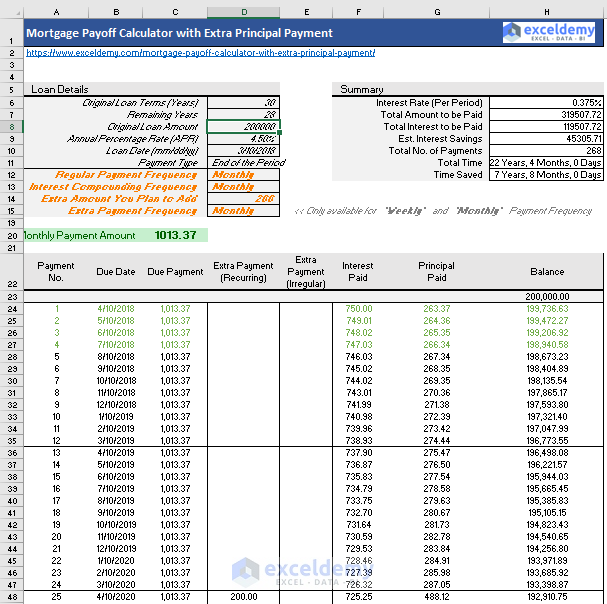
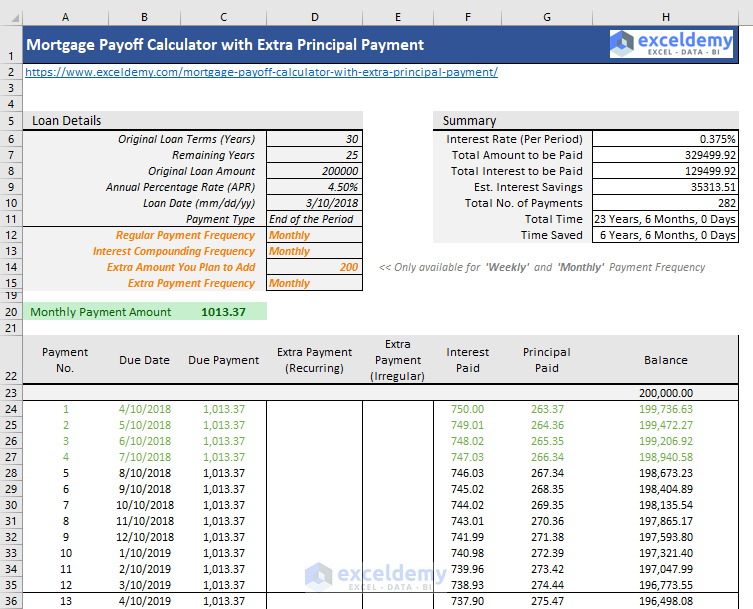
Where P is the principal, r is the monthly rate, and n is the total number of payments. This gives you your baseline payment before any extras. But once you start adding extra principal, the payment stays the same while the remaining balance drops faster than the standard schedule projects. Each month, you recalculate the interest portion based on the new balance, subtract it from your regular payment, and apply whatever's left plus your extra amount directly to principal. Here's where it gets practical. Let's say you have a $250,000 loan at 6.5% over 30 years. Your standard payment comes to about $1,581.37. If you throw an extra $500 at principal every month, that $500 doesn't just reduce next month's interest — it changes the entire trajectory. In the first month, standard interest is $1,354.17. Your regular payment covers that, leaving $227.20 toward principal. Add the extra $500 and your total principal reduction for month one is $727.20 instead. The new balance is $249,272.80. Do this repeatedly and you shave years off the loan. For the actual implementation, whether you're building this in a spreadsheet or code, you need a loop structure. Standard spreadsheet functions like PMT or IPMT won't handle variable prepayments. You're going to build row by row:
Get the Full Details
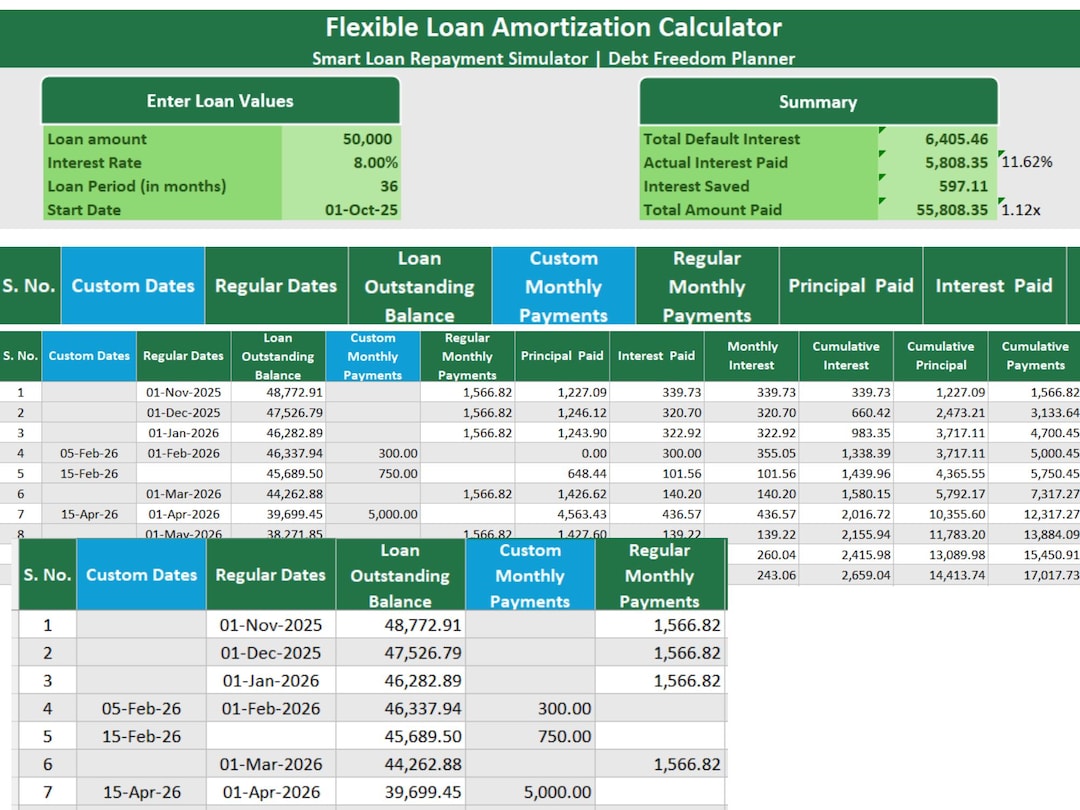
- Calculate interest for the period: remaining balance × monthly rate
- Apply regular payment minus interest to principal (this is the standard allocation)
- Add your extra principal payment to that principal portion
- Subtract the total principal payment from the remaining balance
- Repeat until the balance hits zero or the original term ends
If the balance hits zero before the scheduled term, you stop the loop early and flag that as your payoff date. Most implementations I've seen skip this and just show zeros for the remaining months, which is misleading because it implies the loan continues when it actually doesn't. I spent about three weeks debugging a client's amortization model last year because their calculated interest totals didn't match what their lender was reporting. The discrepancy was small per month — a few dollars — but over 180 payments it added up to nearly $600 in unexplained interest. Turned out the calculator was applying extra principal at the wrong point in the cycle. The lender was processing prepayments on the 15th of each month while the spreadsheet assumed they went through at the end of the period. That timing difference meant each extra payment was being credited one day later than it actually was, so it earned a full month's worth of interest before getting applied to principal. Switching the calculation to mid-period application closed the gap completely. This matters more than you'd think. If you're building a calculator for real use — not just a personal estimate — you need to ask how the lender actually handles prepayments. Do they apply them immediately? At the next statement date? Do they skip a payment cycle? The answer changes your output.
Two Things Beginners Get Wrong
First, the distinction between recasting and re-amortizing. When you make a large extra payment, some lenders will recast the loan, which means they keep your payment the same but recalculate the term based on the new lower balance. Others will re-amortize, keeping the term the same but reducing your monthly payment. These produce dramatically different outcomes. A recast on a 30-year loan with a big prepayment in year three could still leave you making payments for another 25+ years. A re-amortize would lower your payment but you'd still be in the loan for roughly the same duration. Most online calculators assume the first scenario — they just extend the payoff date — but that's not how every lender operates. Second, rounding. Amortization schedules are full of rounding decisions that matter. Some lenders round the monthly payment to the nearest cent at every step. Some round the interest portion only. Some round the principal portion. A well-built calculator should match your lender's rounding convention, or your schedule will gradually diverge from theirs. I've seen spreadsheets that drift by $2 or $3 over five years simply because they used Excel's default rounding instead of matching the actual loan document's terms.
When This Approach Breaks Down
Calculators with extra principal payments work fine for fixed-rate loans with predictable prepayment patterns. They get messy fast with adjustable-rate mortgages because you're now recalculating not just the principal allocation but also the interest rate itself at each adjustment date. The loop structure still works, but you need to track rate changes separately and recompute the payment at each reset. I'd recommend splitting that into two phases: one section for the fixed period and another for the adjustable period, linked by the remaining balance at the first reset date. Balloon loans are another edge case. If your loan has a balloon payment at year seven but you're making extra principal throughout those seven years, the calculator needs to recognize that the final payment isn't just the regular amount — it's the remaining balance in full. Most templates I've seen don't handle this cleanly. They either ignore the balloon or try to absorb it into the regular schedule, which inflates your payments artificially. For anyone who needs this functionality without building from scratch, I'd suggest looking at Excel-based solutions rather than web calculators. Web tools tend to oversimplify the prepayment logic, often applying extras in a way that doesn't match actual lender processing. An Excel model gives you visibility into every cell and the ability to adjust rounding, timing, and application rules to match your specific loan. Google Sheets works too, though it lacks some of the financial function precision that Excel has for this particular use case.
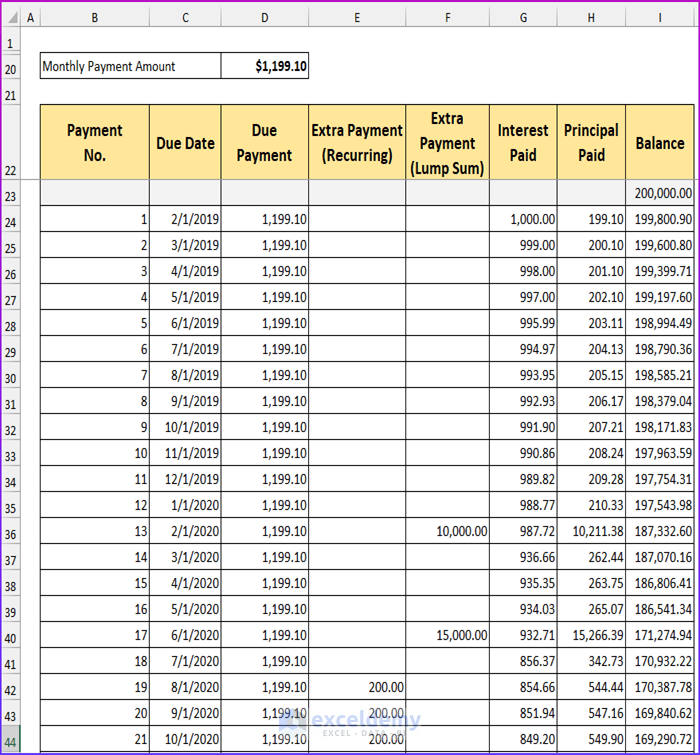
Loan Amortization Calculator With Extra Principal Payments — What to Look For
When evaluating a calculator for this purpose, check whether it shows you the modified payment schedule month by month, not just the aggregate interest savings. The aggregate number is useful for motivation but useless for decision-making. You need to see how each extra payment shifts the remaining balance, how the interest portion shrinks over time, and where the payoff date lands. If the tool only gives you a single "you'll save $47,000 in interest" figure without showing the path there, it's not detailed enough for serious planning. Also verify that it handles partial extra payments, not just round amounts. Real life doesn't align with neat numbers. Someone might overpay by $127.43 one month and $0 the next. A good calculator treats every payment independently rather than assuming a constant extra amount. And if your loan has a prepayment penalty, factor that in. Some loans charge a percentage of the remaining balance for the first few years if you pay down principal faster than scheduled. A calculator that ignores this will give you a false sense of savings. The penalty might wipe out months of interest benefit depending on the terms.