Building a Loan Amortization Schedule in Excel
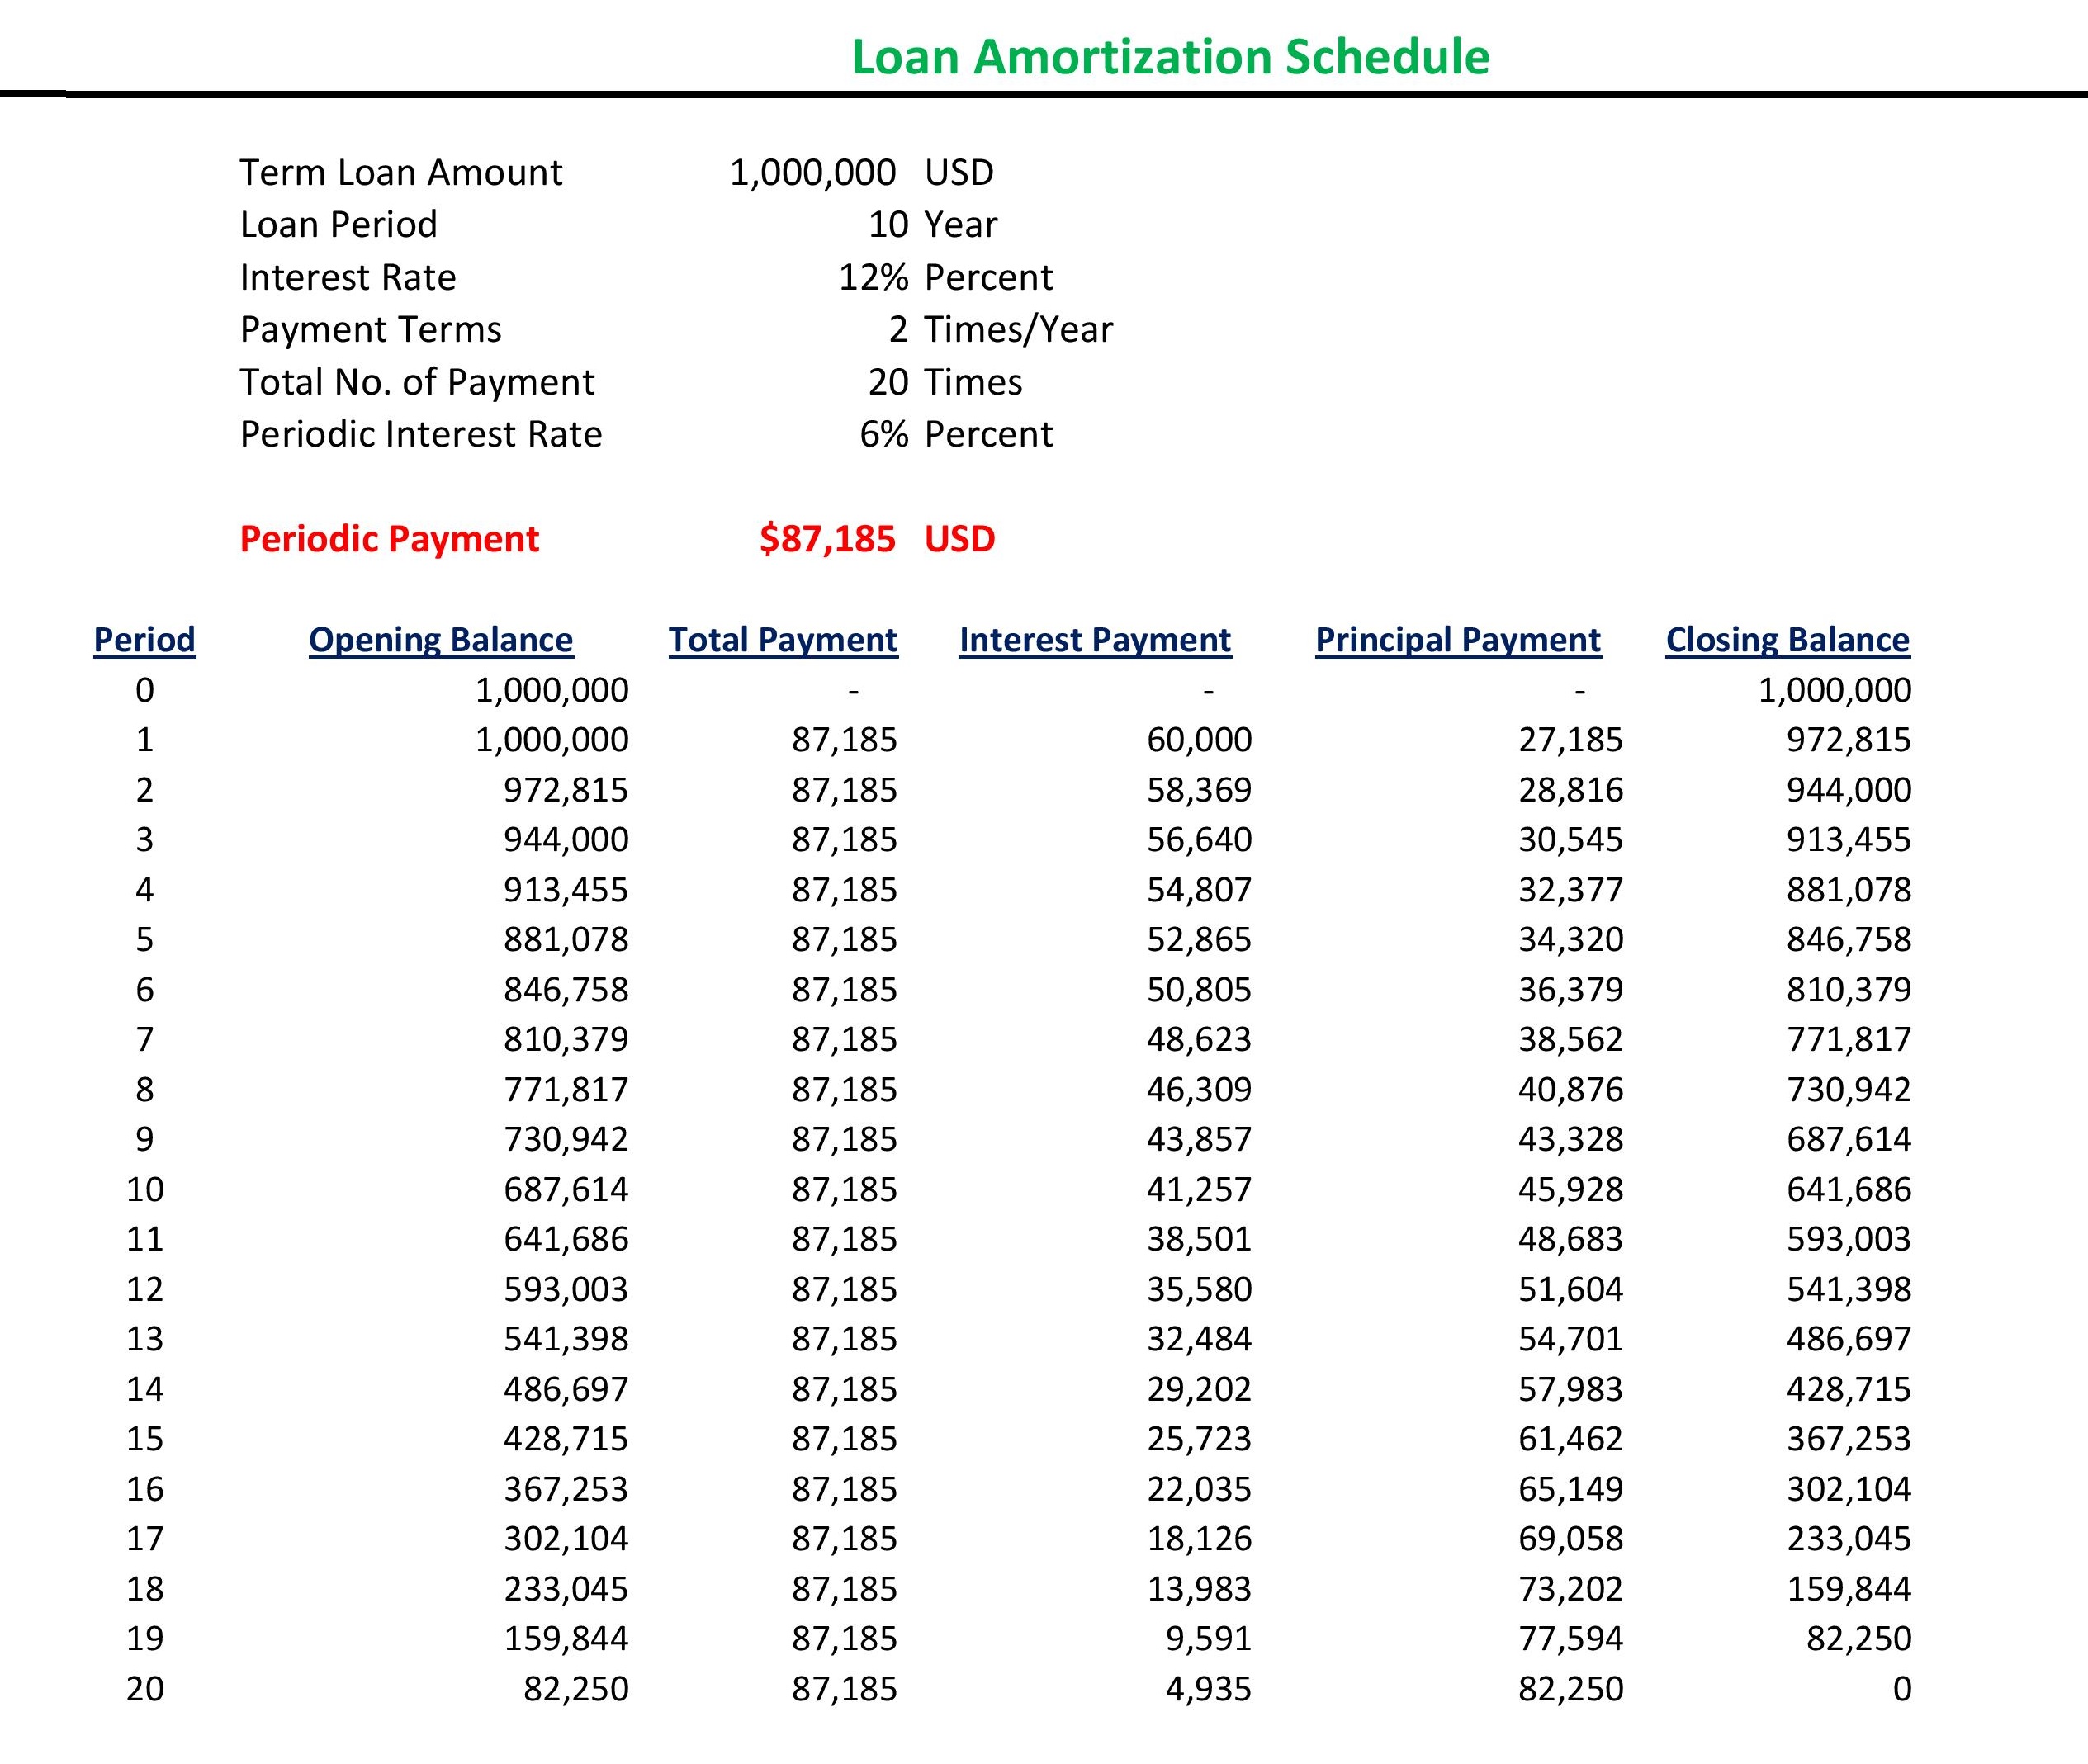
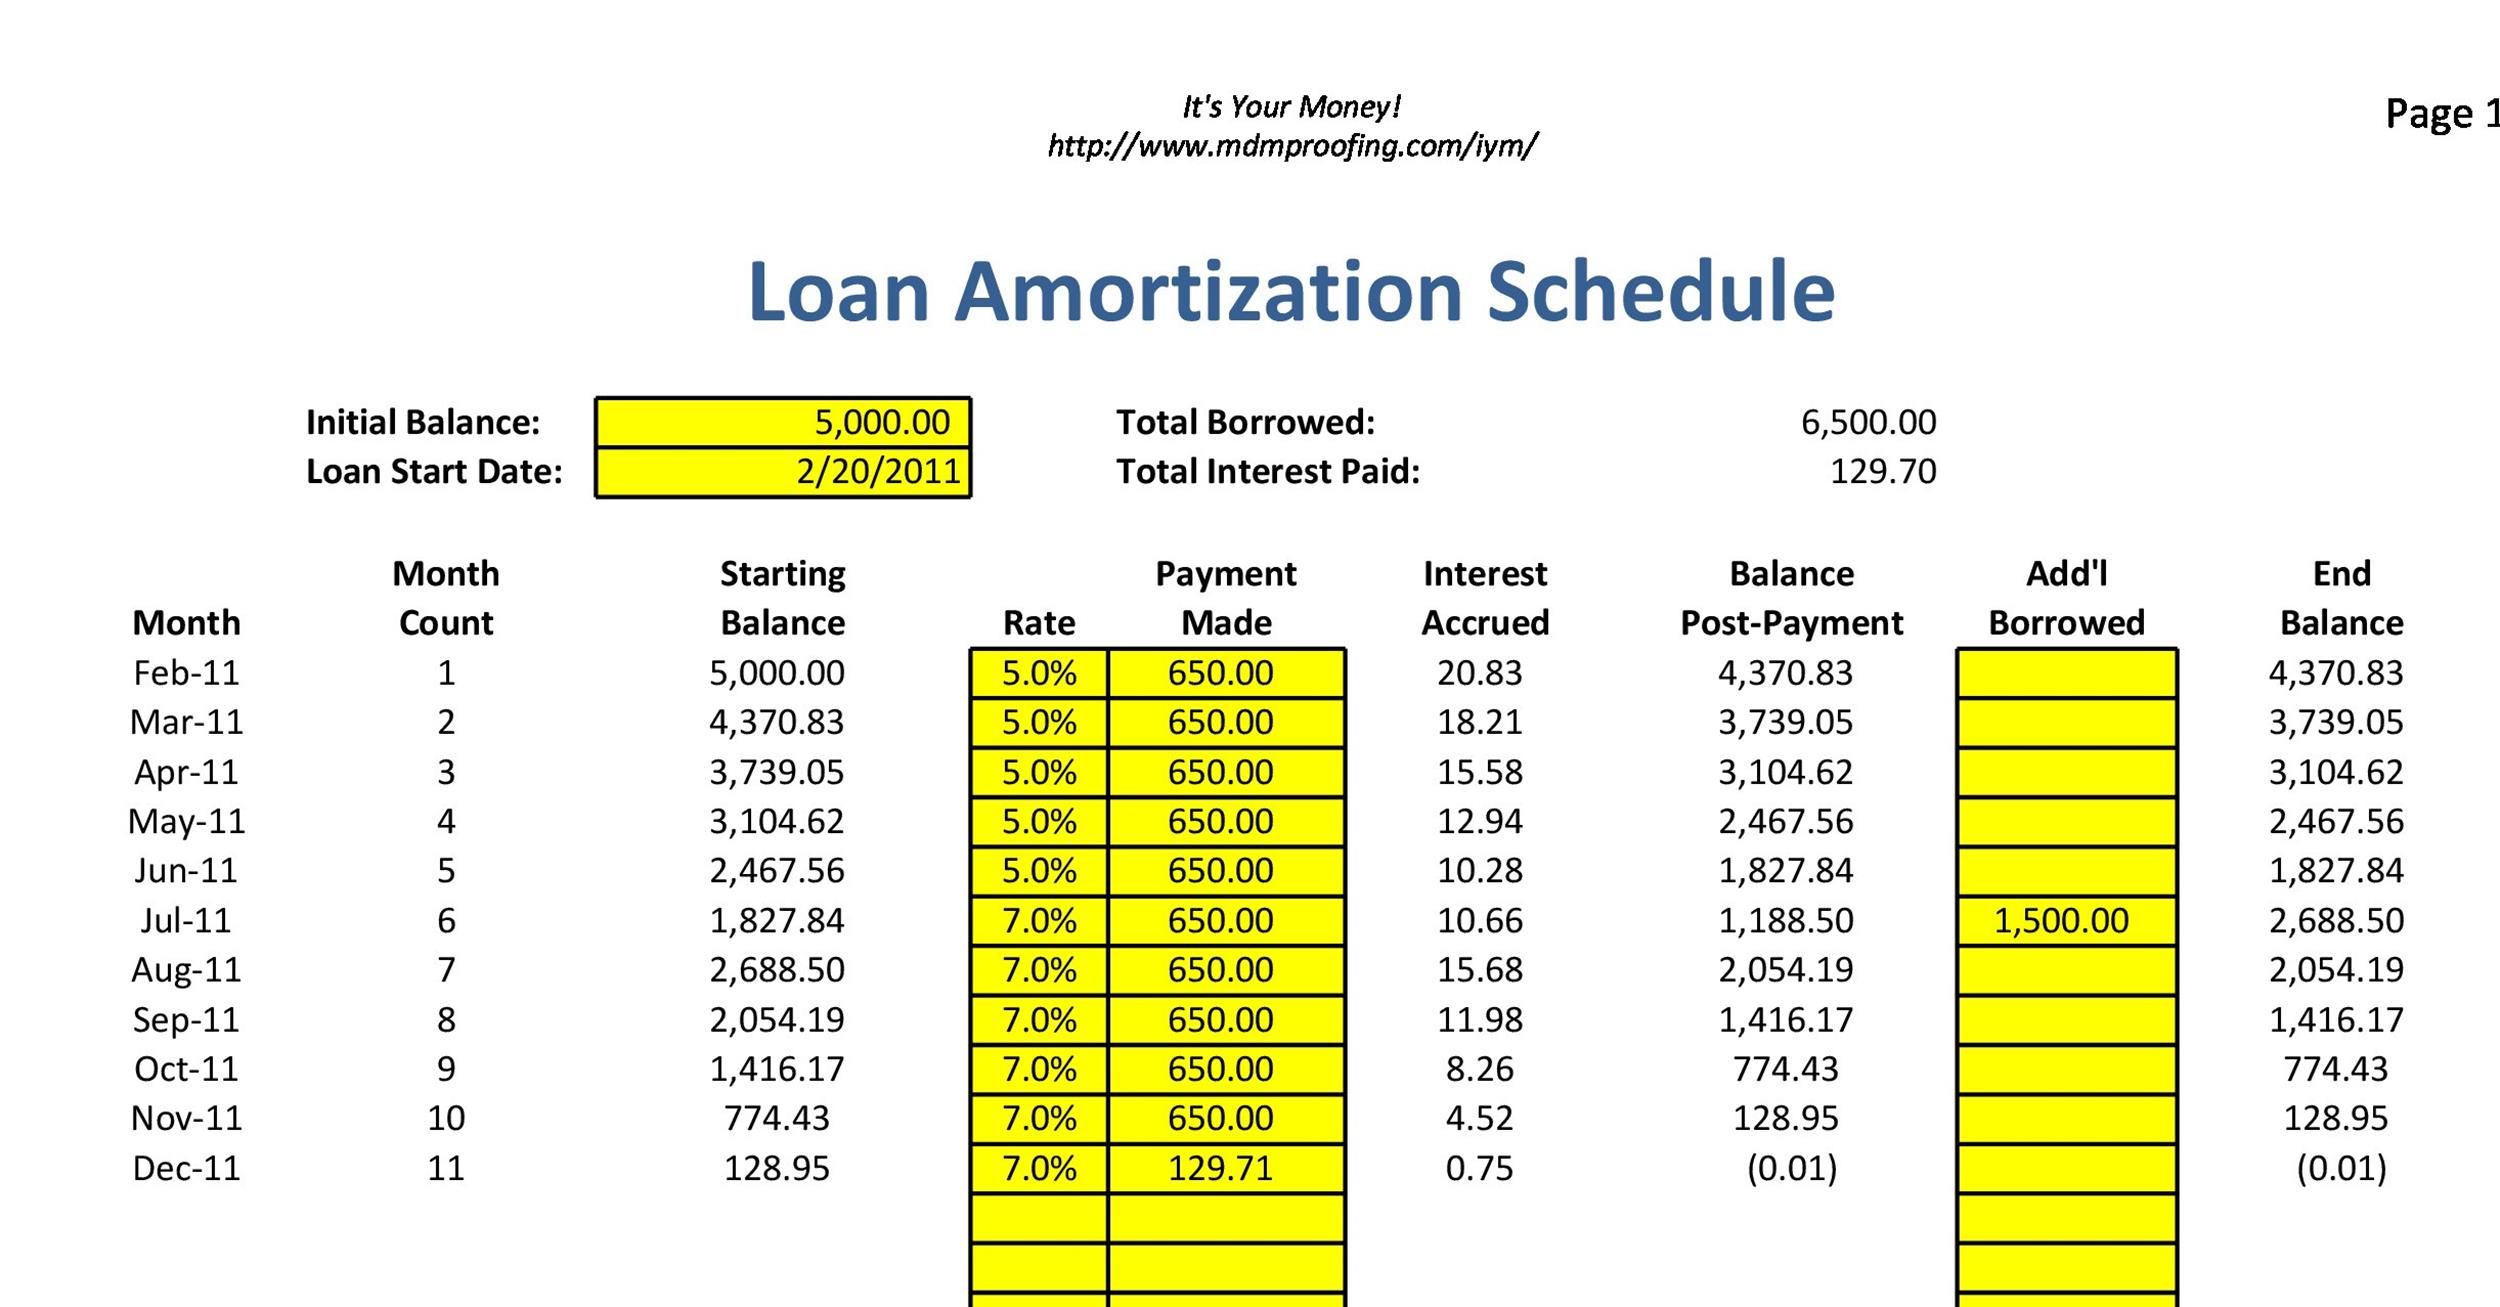
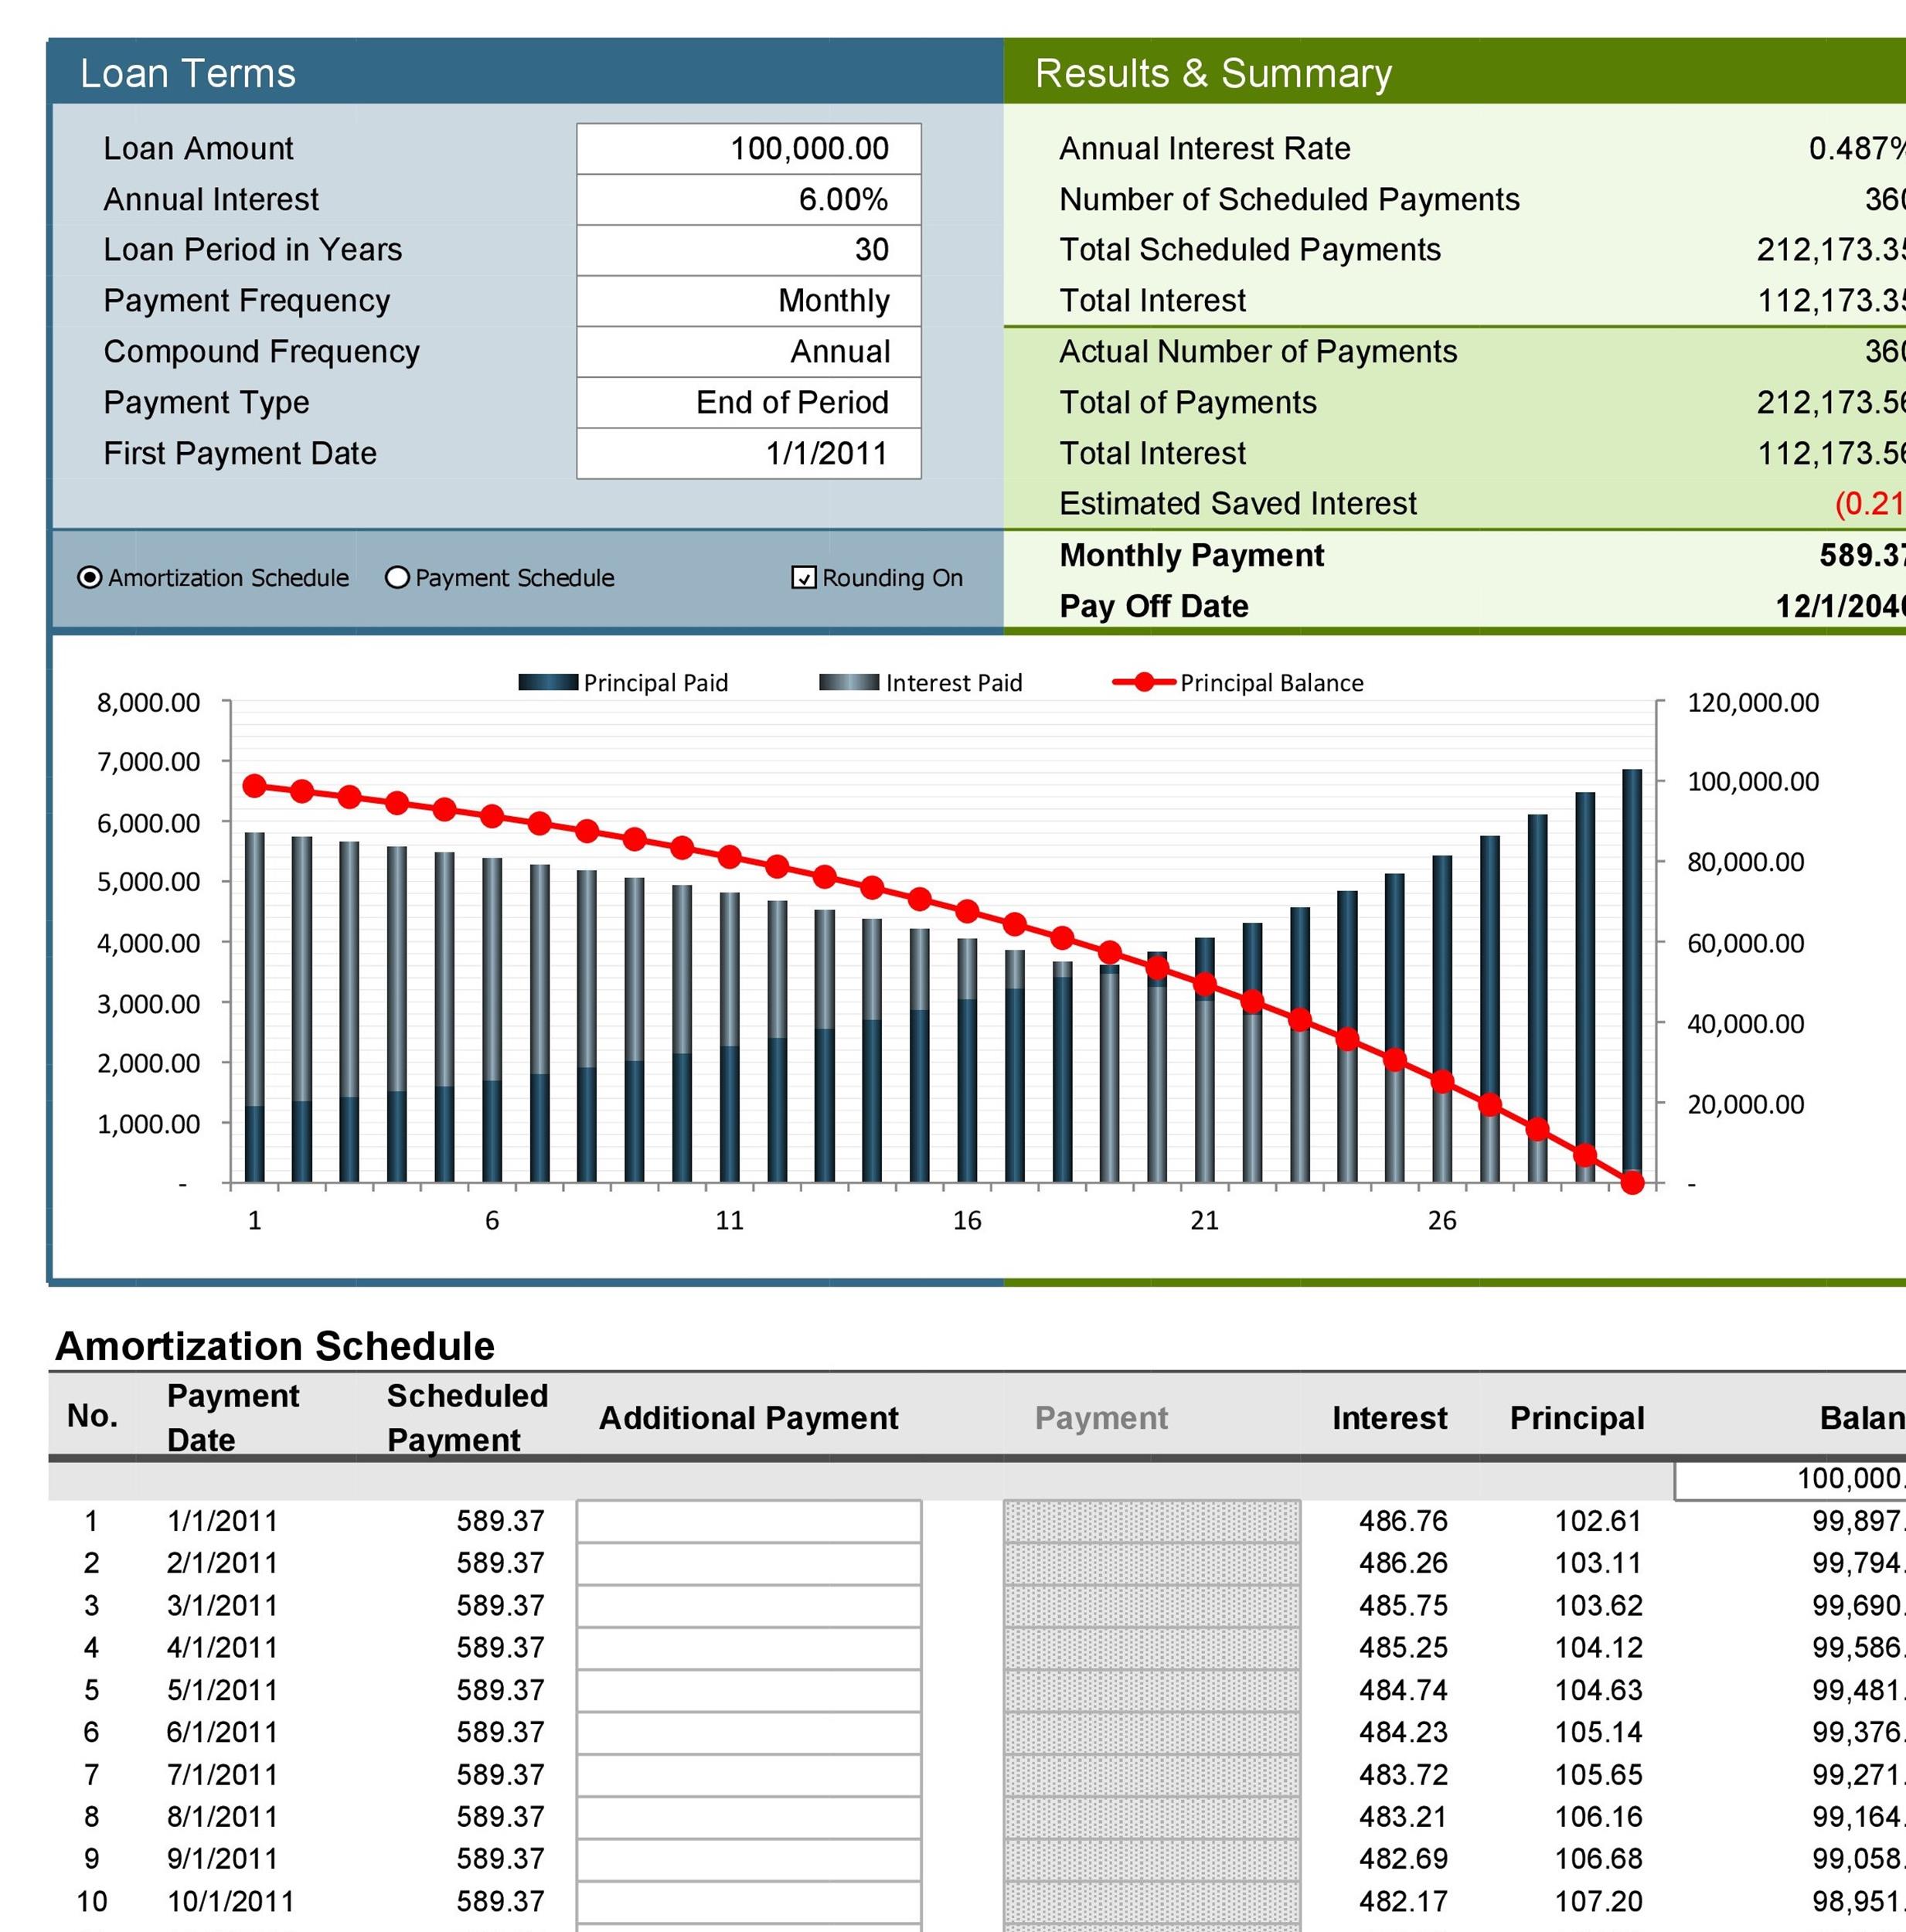
Most people overcomplicate this. The idea behind a Loan Amortization Schedule Excel template is just tracking how each payment splits between interest and principal over time. Interest gets paid first every month, and the rest goes toward reducing the balance. That's it. The reason it feels complicated is because there are enough functions and formatting decisions to create confusion early on. You need six inputs at minimum: the loan amount, the annual interest rate, the total number of payments, the start date, and two optional but important ones — whether payments are made at the beginning or end of the period, and an extra principal column if borrowers sometimes pay more than the minimum. The monthly payment formula uses PMT:
=PMT(rate/12, nper, -pv, 0, 0) That negative sign in front of pv matters. Without it, Excel returns a negative payment, which looks wrong and confuses people who aren't used to seeing cash flow direction built into the function. Put the payment in its own cell and reference it throughout the schedule so you can change one value and have everything recalculate. Here's the breakdown for each row in the schedule:
Interest portion: =BeginningBalance * (AnnualRate / 12) Principal portion: =MonthlyPayment - InterestPortion New balance: =BeginningBalance - PrincipalPortion
Get the Full Details
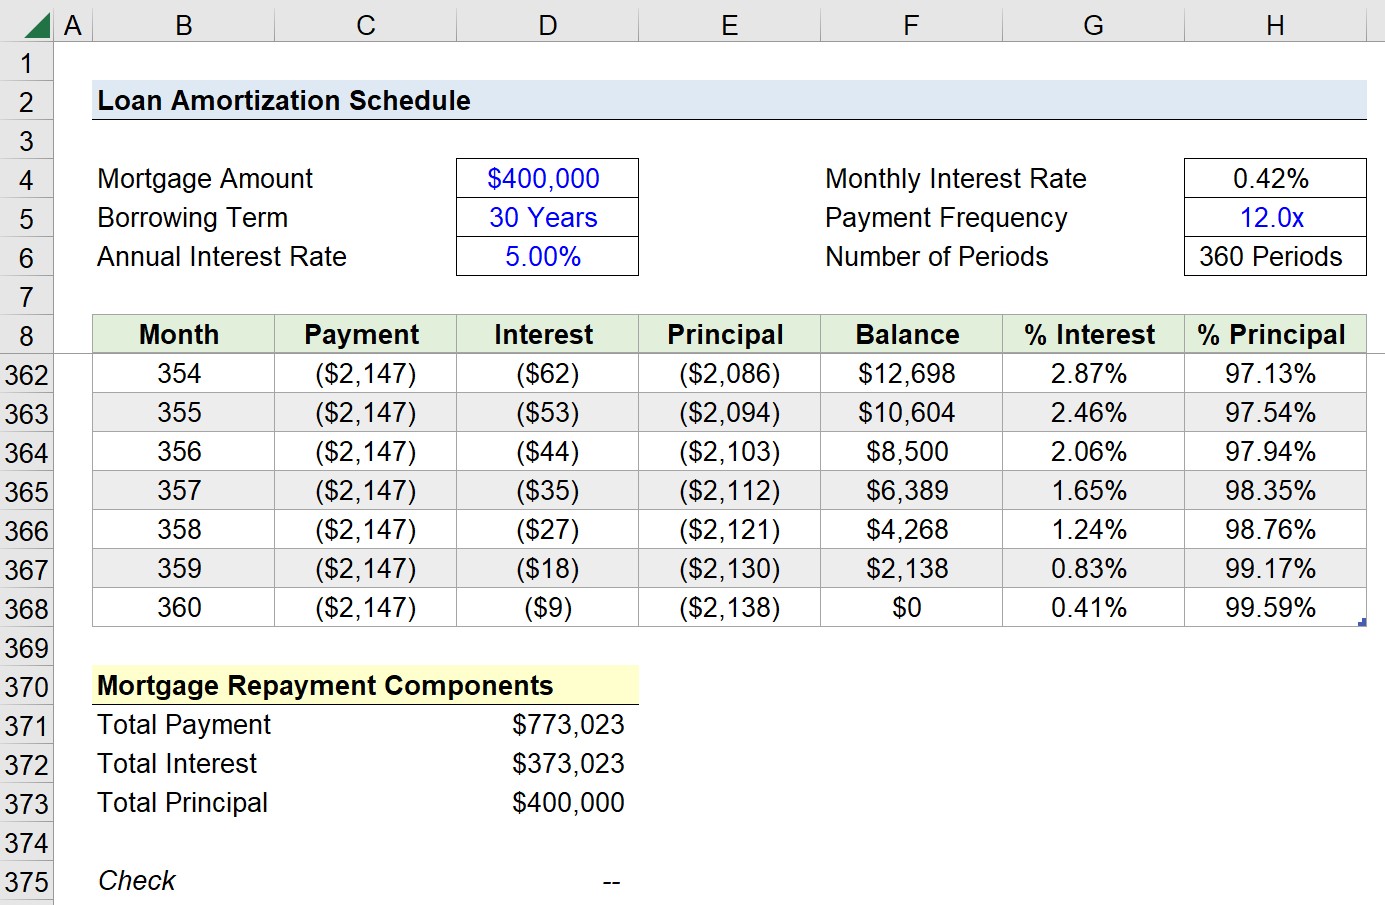
The first month interest is always the highest number. It drops every single month. On a $250,000 loan at 6.5% over 30 years, the first payment's interest is $1,354.17 out of a $1,580.16 total payment. By month 180, the interest portion has fallen to $687.43. By month 359, it's $10.48. The last payment's interest is basically zero. I once spent three hours debugging a schedule someone sent me where the ending balance was $47.32 instead of zero. The issue was cumulative rounding. Excel displays two decimal places by default but calculates with far more precision internally. When you sum the principal column, the tiny fractions stack up. The fix is wrapping every calculation in ROUND(): =ROUND(InterestPortion, 2)
Do this for the interest, the principal, and the new balance each month. You'll save yourself from chasing phantom discrepancies that don't actually exist in the real loan — they only exist in your spreadsheet. For the date column, use: =EDATE(StartDate, RowNumber)
This keeps the payment dates consistent even if you filter or sort the table later. EDATE handles month-end edge cases automatically, which EDATE does and DATE+31 does not. There's a counter-intuitive detail most beginners miss. The PMT function assumes the rate and nper are in the same time unit. If your rate is annual and your nper is months, you must divide the rate by 12 and use 12 times the years for nper. Mixing these up is the single most common error I see. Someone will put the annual rate directly into PMT with monthly periods and wonder why the payment comes out roughly twelve times too high. Another nuance: the type argument in PMT. Setting it to 1 means payments are due at the beginning of the period. Setting it to 0 (the default) means end of period. For mortgages, it's always 0. For leases or rent, it can be 1. Using the wrong value shifts every payment date by one period and changes the total interest paid by a noticeable amount over the life of the loan.
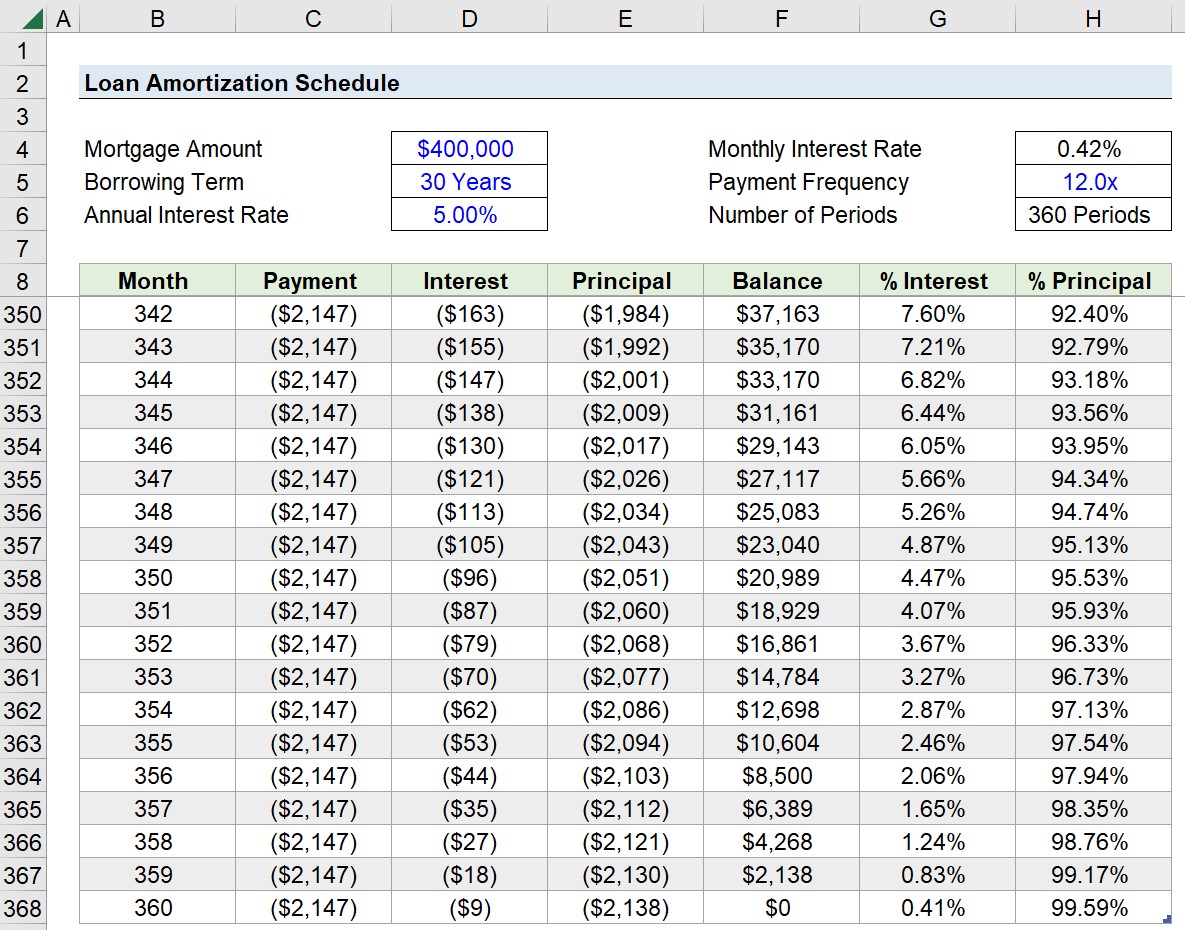
I built a schedule once for a commercial loan where the borrower made irregular additional principal payments every quarter. Standard amortization templates don't handle this well because the payment amount stays fixed in the PMT cell. The workaround was to add an "Extra Payment" column and recalculate the remaining balance after each extra payment, then recompute the number of periods left using NPER with the new balance. It meant a few more formulas, but it was the only way to show the actual payoff date accurately.
What This Approach Doesn't Handle Well
A standard fixed-rate Loan Amortization Schedule Excel template fails completely for adjustable-rate mortgages, balloon payments, or loans with payment caps. If the interest rate changes, the PMT function gives you a single static number and that's wrong. You'd need to rebuild the schedule in segments, recalculating the payment at each adjustment date with the new rate and remaining term. It also doesn't account for escrow. The payment you see in PMT is principal and interest only. Property taxes, homeowners insurance, and mortgage insurance are separate line items that lenders collect monthly but hold in escrow. If you need a full housing payment breakdown, you'll add those as constant columns outside the amortization calculation. For loans with prepayment penalties or tiered interest structures, the simple model breaks down. In those cases, a custom VBA script or a dedicated loan servicing tool is more appropriate than trying to force it into standard spreadsheet functions.
The payoff date is easy to calculate once the schedule is built. Look at the row where the remaining balance first drops to zero or below. In practice, it's often a few days before the scheduled final payment because the last payment is usually smaller than the regular amount. Excel won't always show this cleanly unless you add a conditional formatting rule or a simple formula that flags the payoff row. A full 30-year schedule has 360 rows. It renders fine in modern Excel but can slow down older versions if you have complex formatting applied to every cell. Keep conditional formatting minimal. Use cell styles instead of manual color fills. The difference is noticeable on large schedules. If you want a working template to start from, you can download a pre-built Loan Amortization Schedule Excel file here: [Insert download link]. It includes the PMT setup, the interest and principal columns, the date calculations using EDATE, the ROUND() fix for precision, and a payoff detection row. Everything is labeled so you can see which cells are inputs versus which are calculated. Change the top three cells and the rest updates automatically.

Quick Reference for Common Functions Used
PMT(rate, nper, pv) — calculates the fixed monthly payment. Rate is the per-period rate. Nper is total number of periods. Pv is the present value or loan amount. IPMT(rate, per, nper, pv) — returns the interest portion of a specific payment number. Useful for quick checks without building the full schedule. PPMT(rate, per, nper, pv) — returns the principal portion of a specific payment. Same use case as IPMT.
NPER(rate, pmt, pv) — tells you how many payments it takes to pay off the loan given a payment amount. Handy when you want to know how much faster you'll be debt-free with extra payments. IPAY() and PPAY() don't exist. People sometimes search for these and get confused. The correct functions are IPMT and PPMT. The schedule works best when you separate the input cells from the calculation cells with a clear visual boundary. A thin border or a light fill color on the input section prevents accidental edits. I've seen people change a formula cell because it looked like part of the input area and spend time figuring out why their entire schedule went haywire.
One thing worth noting about the PMT output: it includes both principal and interest. If your loan has origination fees or points rolled into the amount, the PV should reflect the actual financed amount, not the purchase price. Lenders sometimes advertise a lower payment by including fees in the loan balance, and the PMT function will match that number exactly. Just make sure you're entering the correct financed amount. For most personal finance use cases, a fixed-rate mortgage or auto loan amortization schedule is straightforward to build and maintain. The pitfalls are mostly around rounding, rate-period alignment, and assuming the template handles situations it wasn't designed for. Keep the inputs clean, use ROUND() consistently, and verify the final balance is actually zero. If it isn't, go back to the rounding check first.