What actually happens when a balloon payment comes due
A balloon loan is just a standard amortized loan that never quite pays itself off. You make regular payments calculated as if the debt will be gone in, say, seven years, but the full remaining balance is due at the end of year five. The scheduled payments cover interest and a chunk of principal, but not nearly enough to clear the debt by maturity. Then there it sits — a lump sum you either refinance, sell the asset, or pay from cash reserves. Here is how you actually construct one from scratch without relying on a template that glosses over the balloon portion. First, gather your numbers: the principal amount, the annual interest rate, the payment frequency, the amortization period (how many periods the payment is calculated over), and the balloon date (when the large final payment hits). These four inputs drive everything else.
The payment itself uses the standard annuity formula. If you are working in Excel, the PMT function does the heavy lifting: =PMT(rate/nper, nper, -principal) Where rate is the periodic rate (annual rate divided by payments per year), nper is the total number of payments over the amortization period, and principal is the starting balance. This gives you the regular monthly or quarterly payment amount that never changes.
Then you build the schedule row by row. For each period, calculate the interest portion as the remaining balance multiplied by the periodic rate. Subtract that interest from your fixed payment to get the principal reduction for that period. Subtract the principal reduction from the remaining balance. Repeat until you reach the balloon date. At the balloon date, the remaining balance is your balloon payment. It is usually a substantial number — often 30 to 50 percent of the original principal depending on your terms. That final payment clears the loan. I spent several hours once building a balloon schedule for a commercial real estate deal where the amortization was 30 years but the balloon triggered after seven. The lender quoted me an annual percentage rate of 6.75 percent on a $2.4 million loan. The monthly payment came out to roughly $15,580. After 84 payments, the remaining balance was $2,087,340. That is the number that keeps people up at night. I had to build a separate sensitivity table showing what happens if the balloon is refinanced at 8.5 percent instead of the quoted 6.75 — the payment would have jumped to nearly $17,800, which the borrower could not sustain. We restructured the deal to include a 2-year interest-only period before the balloon kicked in, which shaved roughly $180,000 off the balloon amount.
Get the Full Details

Why the balloon balance is almost always higher than people expect
Beginners frequently assume that because the loan amortizes over 30 years, paying for seven years means roughly 23 percent of the principal is gone. It is not. In the early years of any amortizing loan, the interest portion dominates. With a 6.75 percent rate on a $2.4 million loan, your first month pays about $13,500 in interest and only $2,080 toward principal. After seven years of that pattern, you have only reduced the balance by about 13 percent, not 23. This is the core mechanic behind balloon loans and why they exist. Lenders use them to offer lower monthly payments than a fully amortizing loan would require. Borrowers accept them because they plan to sell or refinance before the balloon due date. Both sides think they are getting a good deal until the balloon date arrives.
Common errors when building these schedules
The most frequent mistake I see is confusing the amortization period with the loan term. A 30-year amortization with a 7-year balloon is not a 7-year loan. The payment calculation uses 30 years. The balloon triggers at year 7. Mixing these up produces completely wrong numbers and schedules that do not reconcile. Another error is forgetting to adjust the periodic rate for the payment frequency. Monthly payments require dividing the annual rate by 12. Quarterly payments require division by 4. Using the annual rate directly with monthly periods inflates your interest calculation dramatically. Third, some spreadsheets incorrectly subtract the full payment from the balance each period instead of separating interest and principal. The payment stays constant, but the interest portion shrinks and the principal portion grows over time. Your schedule must reflect that shift period by period.
I also encountered a case where the balloon was structured as a bullet payment rather than a remaining balance payoff. The contract stated the borrower would repay 60 percent of the original principal at maturity, with the remaining 40 percent continuing on a new amortization schedule. That is not a standard balloon — it is a partial balloon with a refinancing component built into the original loan. The amortization schedule needs two distinct phases: the initial payment period and the post-balloon continuation period. Building this in a single spreadsheet requires a column that switches formulas at the balloon date, which most template downloads do not handle correctly.
What to watch for in practice
Balloon loans carry refinancing risk above everything else. If the property or asset value declines between origination and the balloon date, you may not be able to refinance the remaining balance on favorable terms — or at all. I worked with a borrower who could not refinance a $1.8 million balloon because the underlying commercial property had lost 18 percent in value over three years. The lender required a 65 percent loan-to-value ratio at refinancing. The new appraisal put the loan at 82 percent LTV. The borrower had to bring $420,000 in cash to closing just to avoid default. Prepayment penalties are another trap. Many balloon loans include a yield maintenance clause or a hard prepayment penalty that makes early refinancing expensive. Always check the penalty structure before relying on a balloon loan as a short-term solution. The tax treatment of balloon payments also deserves attention. In some jurisdictions, the balloon portion may not be deductible as interest in the year it is paid if it is structured as a return of principal. Consult a tax professional if this is a business loan.
A practical alternative if the balloon feels too risky
If you need lower monthly payments but want to avoid the balloon uncertainty, a fully amortizing loan with a slightly higher rate may be more practical. The payments will be higher, but there is no lump sum due at the end. For a $2.4 million loan at 7.25 percent fully amortized over 30 years, the monthly payment would be approximately $16,380 — only about $800 more per month than the balloon structure, with no balloon payment at year seven. Over the full 30 years, you pay more in total interest, but you eliminate the refinancing risk entirely. Whether that tradeoff makes sense depends on your cash flow stability and your confidence in the asset value at the balloon date.
Where to get a usable template
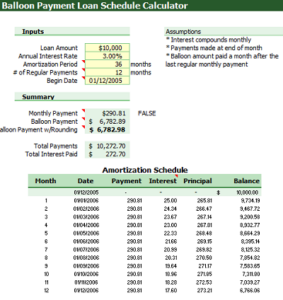
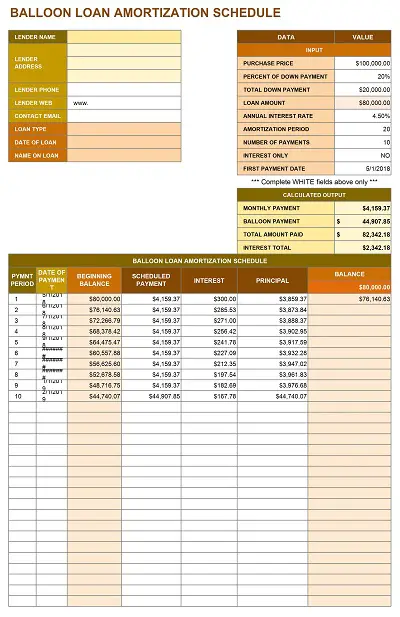
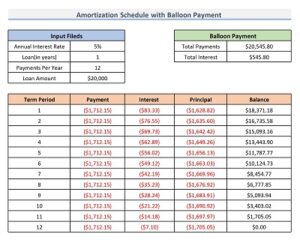
Most spreadsheet templates online do not handle the balloon transition correctly. They either calculate payments based on the wrong period count or fail to show the remaining balance at the balloon date. When you download a Loan Amortization Schedule With Balloon template, verify that the final row before the balloon date shows the correct remaining balance and that the balloon payment is listed separately from the regular payment column. A properly built template will have three distinct sections: the regular payment schedule, the balloon calculation, and a summary showing total interest paid versus total principal repaid across both phases. If you need something that handles partial balloons, interest-only periods, or variable rate adjustments, you will likely need to build the schedule yourself or hire someone to customize a template. The base formulas are straightforward, but the edge cases multiply quickly once you move beyond simple fixed-rate balloon loans.