Building a Basic Loan Calculator in Excel
The easiest way to make a Loan Calculator Excel is to use the built-in PMT function. You need three pieces of information from the borrower: the principal amount, the annual interest rate, and the number of payments. Here is the formula you would enter into a cell: =PMT(rate, nper, pv) Rate is the periodic rate. If your loan is annual percentage rate, you divide by 12 for monthly payments. Nper is the total number of payment periods. Pv is the present value, which is the loan amount. Put a negative sign in front of Pv if you want the result to show as a positive monthly payment. Without that, Excel returns a negative number because it treats payments as cash outflows.
Here is the setup most people get wrong. They put the annual rate directly into the PMT function without dividing. That gives you a monthly payment that is twelve times too high. I have seen this exact mistake on spreadsheets presented to clients at closing. They thought the monthly payment was $4,000 on a $200,000 loan when the actual rate should have been around $1,000.
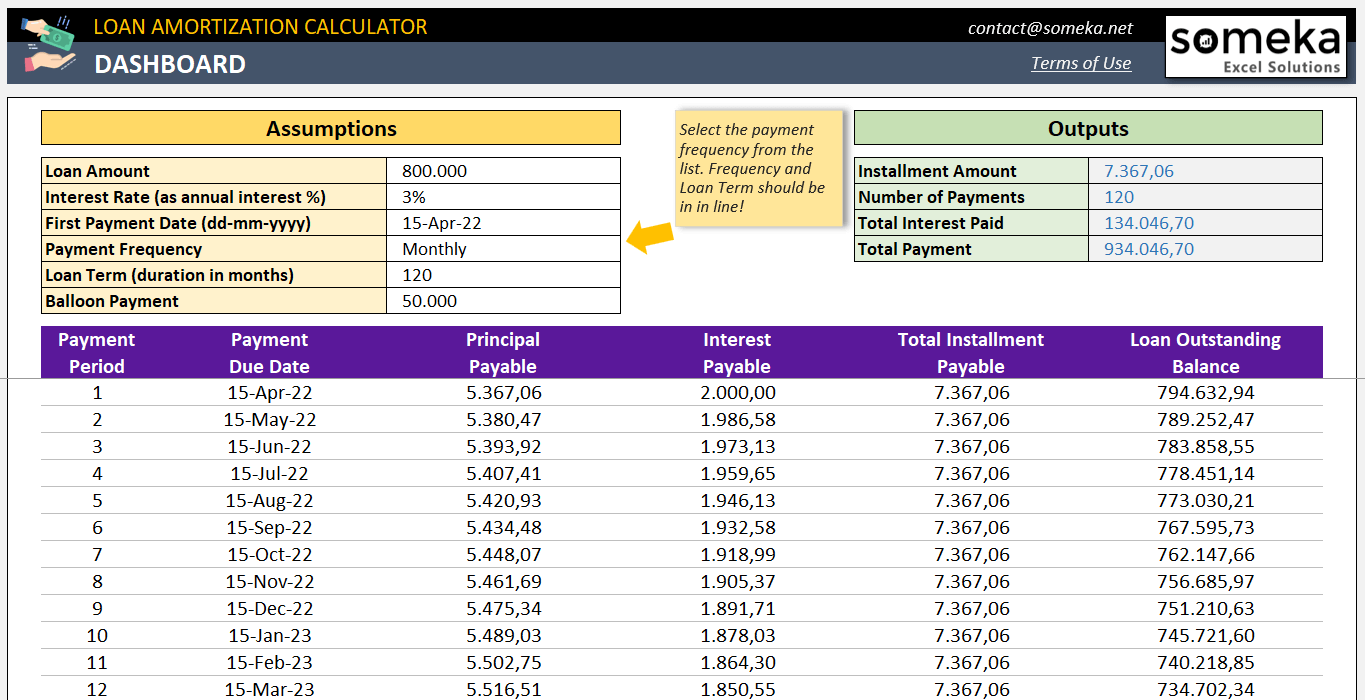
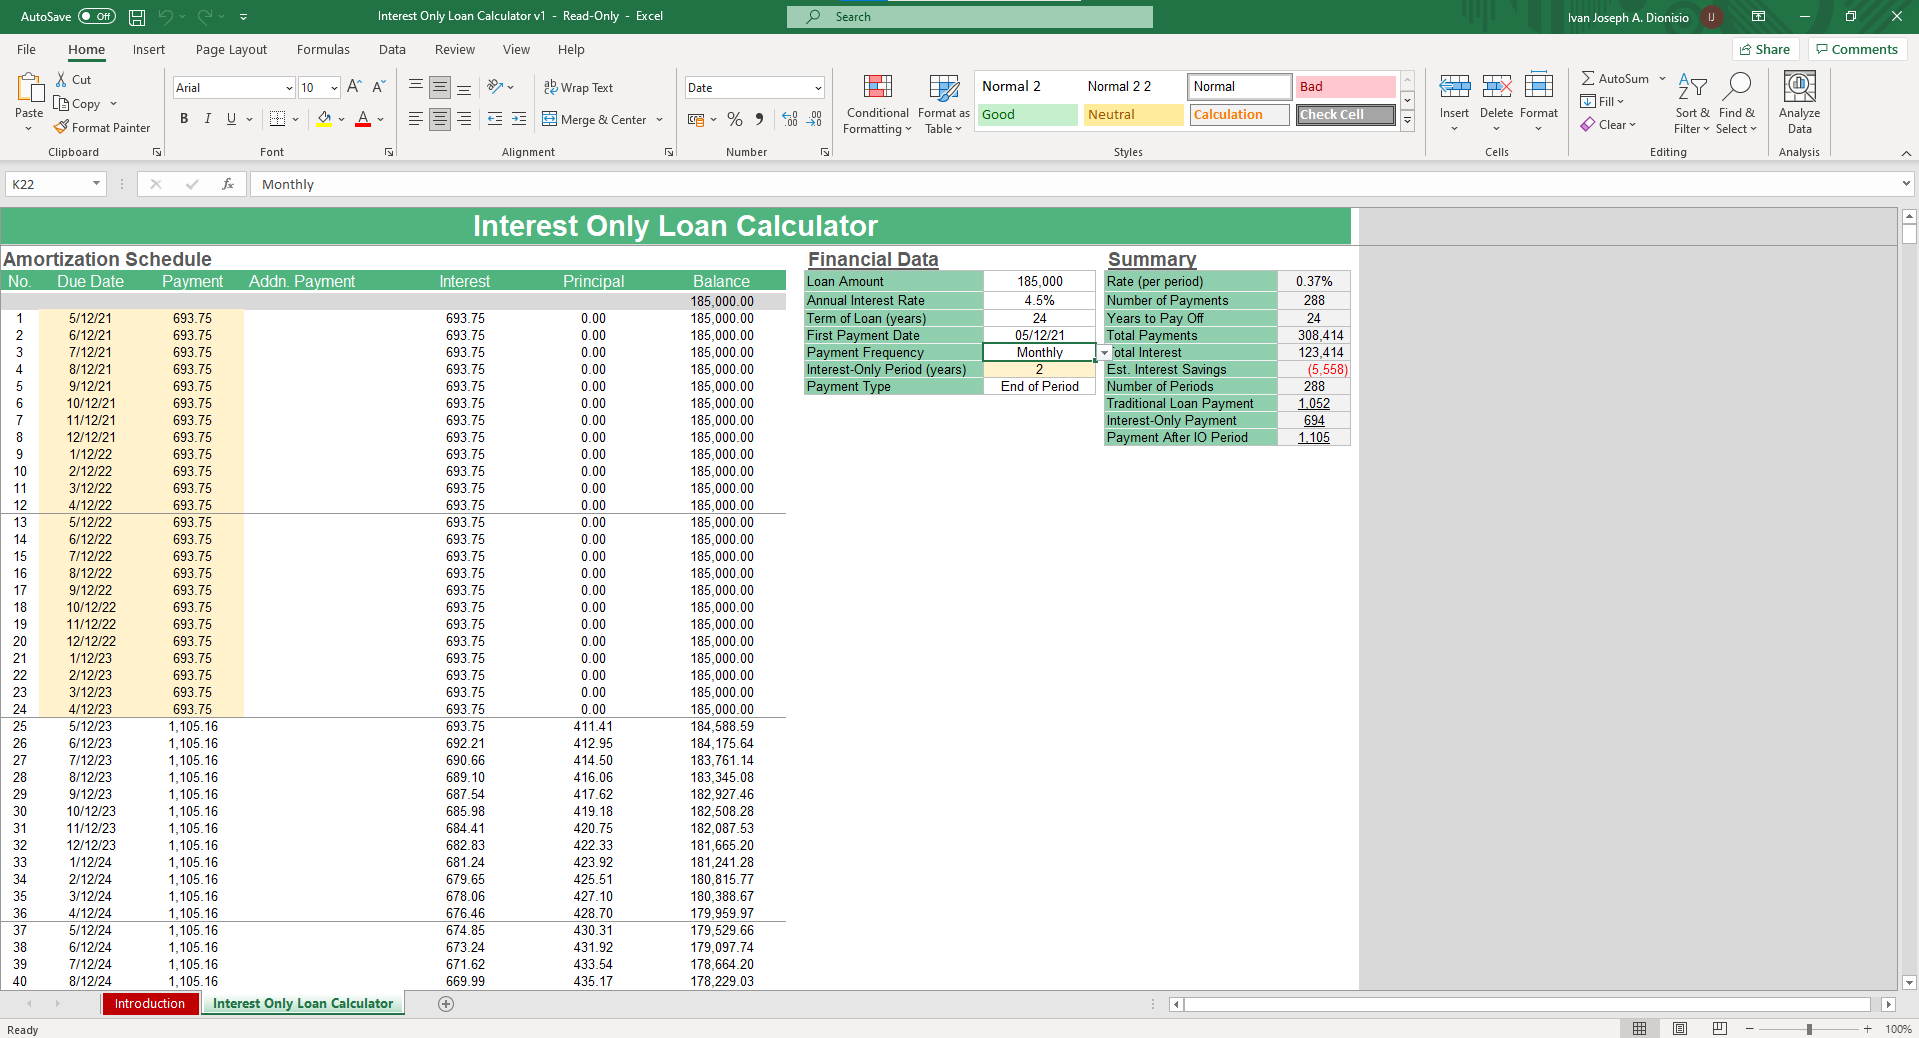
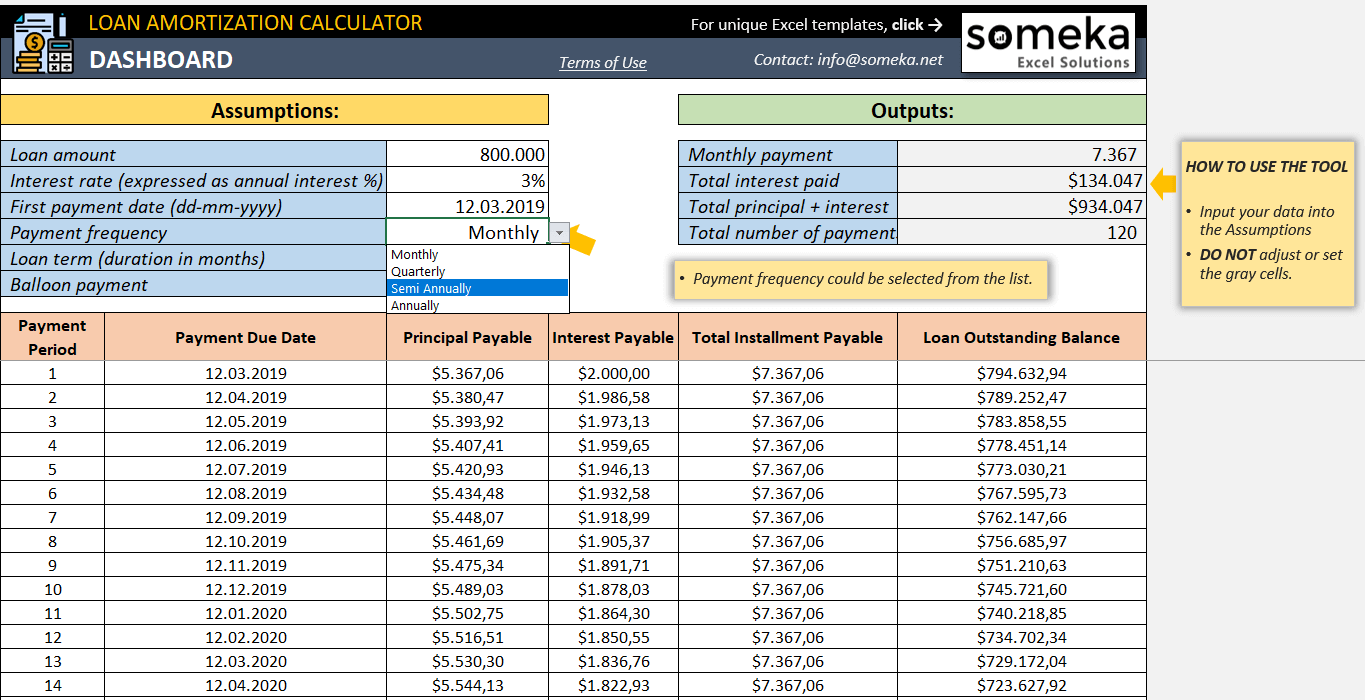
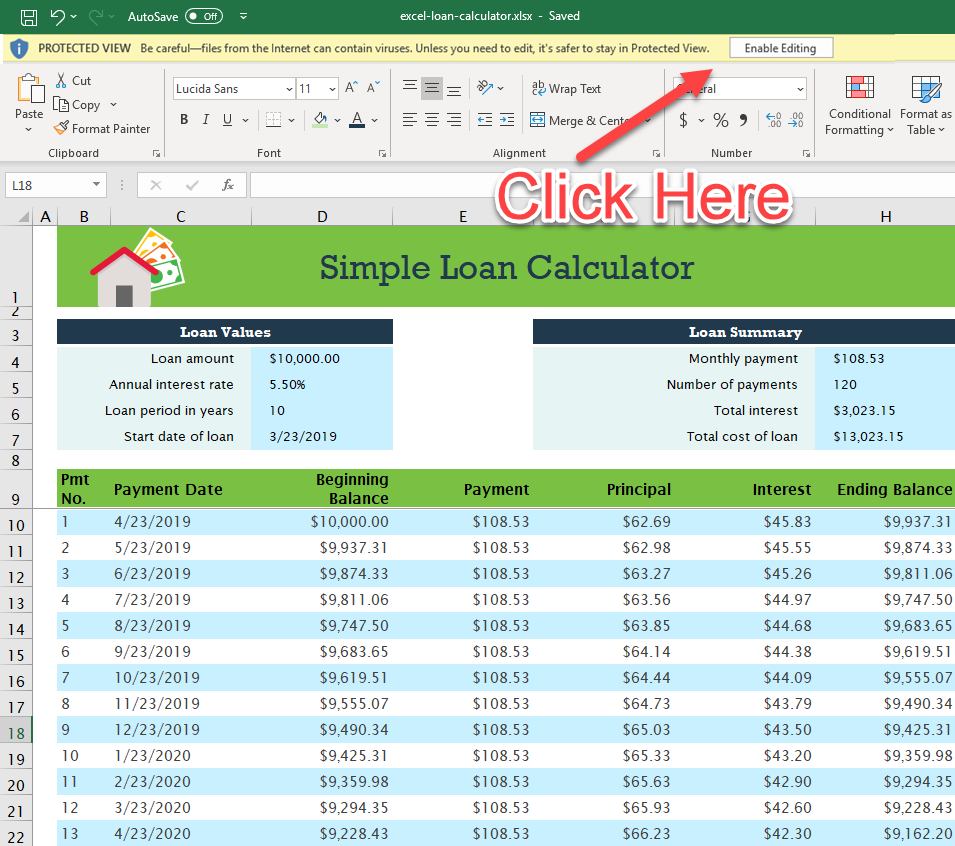
Loan Calculator Excel: Setting Up the Amortization Schedule
A monthly payment number alone is not very useful. You need to see how each payment breaks down between interest and principal over the life of the loan. That is where the amortization table comes in. Create columns for payment number, beginning balance, payment amount, principal portion, interest portion, and ending balance. The interest portion for any given period uses the IPMT function: =IPMT(rate, period, nper, pv)
Get the Full Details

The principal portion uses PPMT: =PPMT(rate, period, nper, pv) The ending balance for each row equals the beginning balance minus the principal portion. The beginning balance for the next row pulls from the previous row's ending balance. Copy these formulas down for the full term. For a 30-year loan at monthly payments, that is 360 rows. Paste Special values over the formulas after you verify the last row reads zero, otherwise you risk the spreadsheet breaking if someone edits a cell further up.
I once built a Loan Calculator Excel for a commercial real estate client who needed to model balloon payments. The standard amortization schedule assumption is that the loan pays off completely at the end of the term. In their case, only 60 percent of the principal was amortized over five years, and the remaining balance was due at maturity. The PMT function gave me the wrong number because it assumes full amortization. I had to back into the correct payment using the FV function as a constraint, setting the future value to the known balloon amount, and solving iteratively. A quick Goal Seek on the payment cell saved me from writing a manual quadratic solver. One thing people rarely consider is how rounding affects the final payment. When you round each principal and interest portion to the nearest cent, the last payment often ends up a few cents off from what the formula predicts. Over 360 months, those rounding differences accumulate. I found this out the hard way when a borrower called me saying their final payment was $12.47 instead of the $1,234.56 shown in the schedule. I traced it through row by row and the discrepancy came from Excel displaying rounded values while computing with full precision underneath. The fix was using ROUND functions around each calculation, then adjusting the final payment to clear the remaining balance exactly. There are real limitations to an Excel-based Loan Calculator Excel. It does not handle variable interest rates. If you have an ARM that adjusts every year based on an index plus a margin, the PMT function will give you a single fixed payment number, which is wrong. You need to recalculate the payment at each adjustment date and rebuild the schedule. I have seen people try to approximate this by manually changing the rate cells and hitting F9, but that approach breaks down quickly past three or four adjustments. For variable-rate products, a VBA script or a linked Python model is more reliable, even if it takes longer to set up initially.
Another common pitfall is ignoring fees in the calculation. Points, origination fees, and closing costs are often rolled into the loan amount or deducted from the proceeds. Neither PMT nor IPMT accounts for these. If the borrower pays two points upfront on a $300,000 loan, the effective interest rate is higher than the stated rate, and the monthly payment does not reflect that cost. The only way to capture it accurately is to calculate the internal rate of return across all cash flows, not just the payment amount. The XIRR function in Excel can do this, but you have to structure the cash flows correctly with dates, which most people do not bother with. If you need a functional spreadsheet to start from, you can download a working Loan Calculator Excel template that includes the amortization schedule, interest and principal breakdowns, and cumulative balance columns. Set your inputs in the designated cells, make sure the rate is formatted as a decimal divided by 12 for monthly calculations, and copy the amortization formulas down to however many periods you need. Double-check the final row before trusting the numbers.