Getting a loan for land purchase is a different beast from buying a house, and most people don't figure that out until they've already wasted weeks
I spent about three years working loan files for raw land transactions before I got tired of it. The process is longer, the rates are higher, and the underwriting criteria are nastier than anything you'll see for a residential mortgage. When you walk into a bank asking for a Loan For Land Purchase, they treat it like a commercial deal even if the parcel is the size of a suburban backyard. That matters because it changes every single term in the contract. Here's how it actually works when you stop reading marketing brochures and start looking at the paperwork.
Loan For Land Purchase
Land loans fall into roughly three buckets. Raw land means vacant, no utilities, no permits approved. Improved land has roads, water, electric, and sometimes sewer stubbed to the lot. Build-ready land has an approved building permit in hand. The farther left you are on that spectrum, the worse your terms will be. I've seen rate spreads of two full percentage points between raw parcels and build-ready ones with identical buyer profiles. The down payment is where people first get confused. Most lenders require twenty-five percent minimum for raw land. Some go up to thirty-five percent. If you have a construction loan lined up to build within twelve months, certain lenders will accept fifteen percent because the risk is shorter and there's collateral in the form of plans and contractor contracts. But fifteen percent is rare and usually requires a top-tier credit score and significant reserves. Interest-only payments are standard. You'll pay only the interest for the first one to three years, then the loan converts to amortizing. This keeps your monthly payment lower during the acquisition phase when you're not generating income from the property. Some lenders offer full amortization from day one, but the monthly payment jumps noticeably once that conversion hits.
Here's a specific edge case I ran into that almost stalled a deal last year. A buyer wanted to purchase a half-acre parcel with no utilities, zoned residential, and they had an architectural plan ready to go. The lender's automated underwriter flagged it as raw land because there was no permit yet. I pushed back by submitting the architect's stamp letter, the signed engineering agreement for well and septic, and the pre-approval from the county building department. They reclassified it as build-ready and dropped the down payment requirement from thirty percent to twenty percent. That single reclassification saved the buyer about eighteen thousand dollars out of pocket. Without that documentation package, the deal would have collapsed because the buyer simply couldn't come up with the extra cash. The loan terms themselves are tight. Typical maximum loan-to-value ratios sit at seventy-five percent for raw land and eighty percent for improved or build-ready. Original maturities range from five to twenty years depending on the lender. You'll rarely find anything beyond twenty-five years unless you're dealing with a farm or land contract through agricultural lending programs. The balloon payment structure is common too. Some lenders finance for ten years then demand the full balance, which means you either sell, refinance, or come up with a large lump sum at that point. Closing costs run higher than residential deals. Expect two to four percent of the purchase price, which includes the environmental assessment, survey, title insurance with extra endorsement work for vacant land, and sometimes a phase one wetlands review if the parcel borders any water features. On a two hundred thousand dollar parcel, that's four thousand to eight thousand dollars you need to bring to closing on top of the down payment.
Get the Full Details
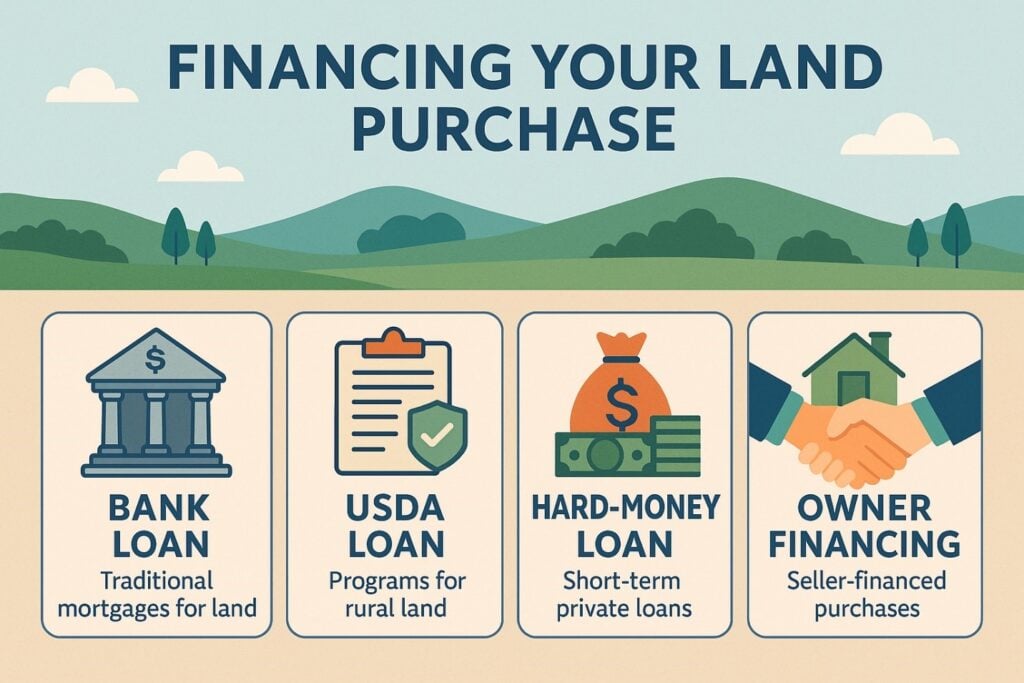
There's one thing nobody tells you about land loans: the appraisal process is broken. Appraisers specialize in houses, not dirt. When they value raw land, they look for recent sales of comparable parcels within a five-mile radius. If you're in a rural area where comparable sales haven't moved in five years, the appraised value can come in ten to fifteen percent below what you're paying. I've seen deals fall apart because the appraisal gap forced the buyer to bring extra cash they didn't have. The workaround is getting a broker price opinion from a local land specialist before you write the offer, which costs you about five hundred dollars and gives you a realistic sense of where the appraisal will land. If you're shopping around, don't just call the big national banks. Community banks and credit unions often have better land loan programs because they understand the local market and hold the loans in portfolio rather than selling them on the secondary market. Rural Development loans through the USDA are an option if the parcel meets their eligibility requirements, and those can offer up to one hundred percent financing for qualifying borrowers in designated rural areas. The tradeoff is the processing time runs longer, typically forty to sixty days compared to thirty days for conventional land loans. The due diligence period matters more on land than on any other property type. You need to verify zoning, confirm utility availability in writing, check for restrictive covenants or HOA restrictions, test the soil for percolation if you plan a septic system, and make sure the parcel has legal road access. An easement dispute over a shared driveway can cost you thirty thousand dollars to resolve after closing. I learned that one the hard way on a job in 2022 when a buyer closed on a lot that appeared to have frontage on a public road, only to discover the road was a private easement maintained by twelve other homeowners, and the HOA fees alone ran six hundred dollars a month.
Don't skip the survey. A boundary line dispute on raw land is expensive and ugly. I've seen cases where a fence installed twenty years ago sits eight feet inside the legal property line, and the neighbor can claim adverse possession if you don't document the discrepancy early. Getting a modern ALTA survey before closing costs between eight hundred and two thousand dollars, but it prevents far worse headaches later. Another common mistake is assuming you can build immediately. Even with an approved plan, permit timelines vary wildly by county. In some jurisdictions, a residential building permit takes ninety days. In others, it takes nine months because of environmental review requirements. Your land loan payment continues during this entire period with nothing to show for it. If you're carrying a hundred thousand dollar loan at eight percent interest, that's roughly six hundred and sixty-seven dollars a month you're burning while waiting for a piece of paper that says you can dig a hole. The best strategy I've found is to structure the land loan as a short-term bridge with a defined exit plan. Secure a twelve-to-eighteen-month loan, complete your due diligence, get permits approved, then refinance into a construction loan or permanent mortgage once the project has momentum. This approach acknowledges that land loans are inherently risky for lenders, so you're working with their constraints rather than against them. It also gives you leverage to negotiate better terms because you can show the lender a clear path to payoff.
If the parcel is small and you're planning to build on it quickly, consider whether a home equity line of credit makes more sense than a standalone land loan. The rates are lower, the process is faster, and you avoid the restrictive covenants that come with pure land financing. The catch is you need sufficient equity in your existing home, and you're putting that property at risk instead of the land itself. It's a real option for people who already own a home and just need capital to acquire a buildable lot. Documentation checklist for the strongest application: a two hundred fifty word statement of intent explaining how you plan to use the land, proof of funds for the down payment and closing costs, a preliminary title report showing clean ownership, contractor or engineer letters confirming utility availability, and a copy of any existing survey. The more upfront you give lenders, the faster they process the file and the more likely they are to stretch on LTV and rate. I've seen applicants who submitted complete packages get approved in fourteen days, while incomplete files sat in queue for forty-five days with multiple requests for additional documentation that could have been included from the start. One final note on rates. Land loan rates typically run one to two points above the prime mortgage rate at any given time. If the thirty-year fixed rate is six percent, expect land loans to quote between seven and eight percent. During periods of elevated rates, that spread can widen further because lenders perceive raw land as the riskiest asset class in their portfolio. Always lock your rate once you have a locked purchase contract, because land loans can take longer to close than home purchases, and you don't want to be exposed to rate movements during underwriting.

The whole process from application to closing usually takes thirty to sixty days for land loans compared to twenty to thirty days for residential mortgages. Budget your timeline accordingly, and don't sign a purchase agreement until you have a firm loan commitment in hand rather than pre-approval. Pre-approval on a land loan is much less meaningful than on a home purchase because the underwriting standards shift so dramatically based on parcel characteristics.