Why Your Generic Mortgage Calculator Is Lying to You (And What to Use Instead)
I spent three years helping clients compare loan estimates across Massachusetts before I stopped trusting standard calculators. The problem isn't that they're wrong, it's that they leave out half the story. A calculator that only plugs principal, interest, and term into the amortization formula gives you a monthly payment number, sure. But in Massachusetts, that number is missing property tax, insurance, homestead-related deductions, and sometimes even the impact of your local municipal financing structures. I learned this the hard way when a client came to me after closing because her actual monthly cost was $400 higher than what the online calculator showed. She had used a popular national mortgage calculator that didn't account for Massachusetts' relatively high property tax rates in certain municipalities.
What the Ma Mortgage Calculator Actually Does Differently
The Ma Mortgage Calculator refers to a mortgage estimation tool built specifically for Massachusetts transactions. That means it factors in things like the Massachusetts property tax rate by city or town, homeowner's insurance estimates specific to coastal or inland risk zones, and potentially the state's mortgage recording tax at 0.46% on deeds and mortgages. It may also account for the Massachusetts homestead exemption, which protects a certain amount of home equity from creditors but also affects how lenders view equity calculations in some scenarios. The key difference is local granularity. A national calculator treats all states roughly the same. A Ma Mortgage Calculator breaks things down by municipality where possible.
How to Use It Without Getting Misleading Numbers
Here's the practical process. You start by identifying your exact municipality because property tax rates in Massachusetts vary wildly. Malden might have a rate around $4.50 per thousand in assessed value while a place like Beverly could be closer to $2.80. The difference on a $500,000 home is thousands of dollars annually. Enter your purchase price or refinance amount, your down payment percentage, your interest rate, and your loan term. The calculator will spit out a monthly estimate. But don't stop there. Verify the property tax line item by looking up your actual town's tax rate on the Massachusetts Department of Revenue website. I had a case last year where the calculator pulled a tax rate from the county level instead of the town level, which threw the entire number off by about $120 a month. Cross-check every line item against your actual municipal data.
Get the Full Details
The Homestead Exemption Factor Most People Miss
Massachusetts has a$5,000 homestead exemption that reduces the assessed value of your primary residence for property tax purposes. Some Ma Mortgage Calculator tools account for this automatically if you mark the property as your primary residence. Others don't. If yours doesn't, you need to adjust the assessed value manually by subtracting $5,000 before running the calculation. It's a small amount but over a 30-year mortgage it adds up. I also found that some calculators fail to factor in the automatic homestead protection that applies to all Massachusetts homeowners whether they file a declaration or not. This protection is worth up to $125,000 in equity but doesn't directly affect your monthly payment, so most calculators skip it. That's fine for payment estimation but worth knowing if you're evaluating the overall financial picture.
When the Ma Mortgage Calculator Falls Short
No calculator is perfect. Here are the situations where you should not rely on one. First, if you have a FHA loan with MIP or an VA loan with a funding fee, most Ma Mortgage Calculator tools do not include those in their standard output. You need to add the MIP or funding fee manually to your monthly payment estimate. Second, if you are buying in a condominium, the HOA fees can range from $200 to over $800 per month depending on the building. Some calculators have a field for HOA but many don't, and the ones that do often leave it as an optional input rather than surfacing it prominently. Third, if you are refinancing and your new loan will be above the conforming loan limit for Massachusetts, which is $766,550 in most areas and higher in high-cost counties, jumbo loan rates apply and those are structured differently. Standard calculators assume conforming loan terms.
A Workaround for the HOA Problem
I ran into a specific issue with a client who was comparing two condos in different towns. The Ma Mortgage Calculator showed one unit as more affordable because the property taxes were lower, but it did not include HOA fees in the default view. The unit with lower taxes had HOA fees that were $350/month higher, completely flipping the comparison. My workaround was to take the calculator's base payment, add the HOA fee as a separate line item, and then also factor in the difference in insurance premiums. Coastal condos in places like Plymouth or Cohasset run significantly more for insurance than inland units. I built a simple spreadsheet that pulled the calculator output and layered in those variables. It took me about ten minutes to set up and saved my client from making a costly comparison error.
Interest Rate Realities in Massachusetts
Massachusetts does not have a separate state-level interest rate environment, but certain programs do. The Massachusetts Housing Partnership and various local first-time homebuyer programs offer below-market rates or down payment assistance that standard calculators won't capture. If you are using a Ma Mortgage Calculator for a conventional loan, the numbers are generally reliable. If you are exploring a MassHousing loan or a CASH Flow program, you should verify the calculator's assumptions against the actual program guidelines. I once saw a client use a calculator that assumed a 30-year fixed at a certain rate, then apply for a MassHousing loan that came with a different rate and different closing cost structure. The gap between the estimate and the real numbers was significant enough to change her decision on which neighborhood to buy in.
Reading the Output Like a Professional
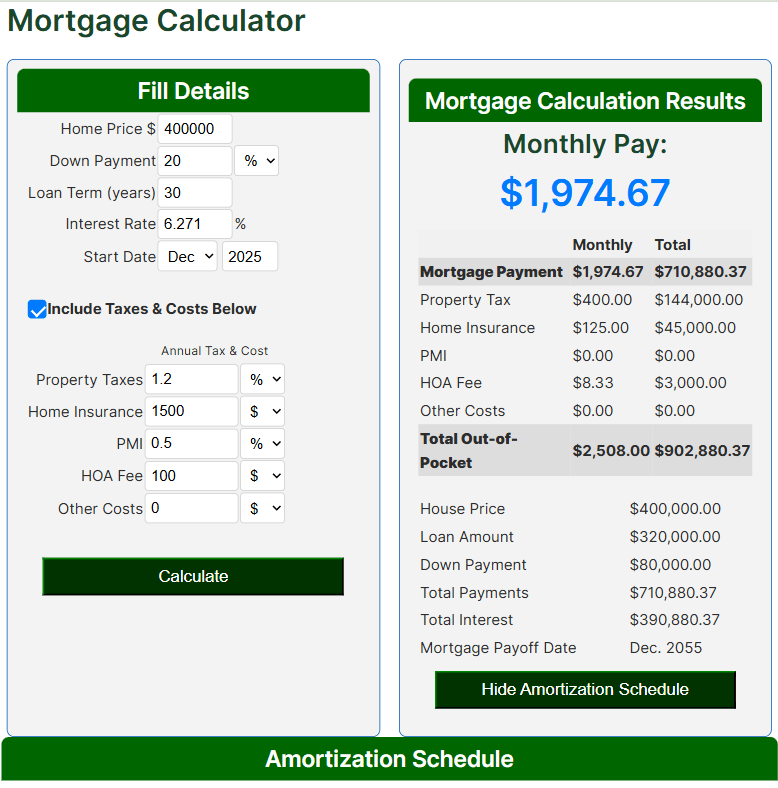
When you look at the result from a Ma Mortgage Calculator, focus on the PITI breakdown: principal, interest, taxes, and insurance. If the calculator only gives you a P&I number, it is not giving you the full picture. A responsible estimate includes the other two components. Look for a tool that breaks down each element separately so you can verify them against local data. Also check whether the calculator includes mortgage insurance in the estimate. If your down payment is under 20%, private mortgage insurance will be part of your monthly payment, and some calculators hide this or exclude it entirely. In Massachusetts, PMI typically ranges from 0.5% to 1% of the loan amount annually depending on your credit score and down payment size.
The Bottom Line on What to Trust
Use a Ma Mortgage Calculator as a starting point, not a final answer. It gives you a ball park figure that is better than guessing, but you need to validate it against actual municipal data, your specific loan program, and any HOA or special assessment fees that the tool may not know about. The ones that include municipality-level tax rates and optional fields for HOA, PMI, and insurance are the most useful. Anything less is a rough sketch. I recommend running your numbers through at least two different calculators and comparing the outputs. If they differ by more than 5%, something is making different assumptions and you need to dig into the settings to find out what.