How Prices Actually Coordinate What We Produce, Buy, and Sell
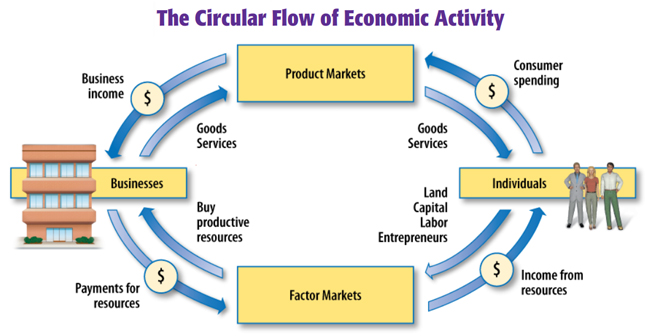
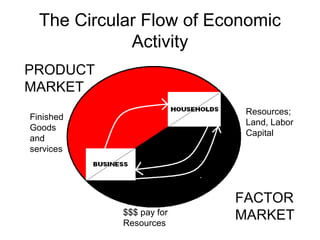
The coordination problem is the central puzzle of any economy larger than a village. You cannot centrally plan bread, microchips, and avocados simultaneously. Nobody has the information. Markets solve this by turning dispersed knowledge into price signals, and that is how they coordinate economic activity through a mechanism that is deceptively simple but fragile under the right conditions. Prices are compressed information. When copper supply contracts because a major mine in Chile shuts down unexpectedly, the price rises. That single number tells a phone manufacturer in Shenzhen to redesign around aluminum, tells a construction firm in Toronto to delay wiring work, and tells a mining company in Peru to expand operations. No meeting was scheduled. No memo was sent. Everyone just reacted to the price. I spent three weeks tracking a supply chain disruption during the 2021 container shipping crisis. What I observed was not chaos but a distributed recalibration happening in real time. Freight rates spiked, which caused retailers to shift orders from sea to air for high-margin goods, while low-margin bulk items got cut from shipments entirely. Allocators didn't sit down and agree on a priority list. The rate itself became the allocator.
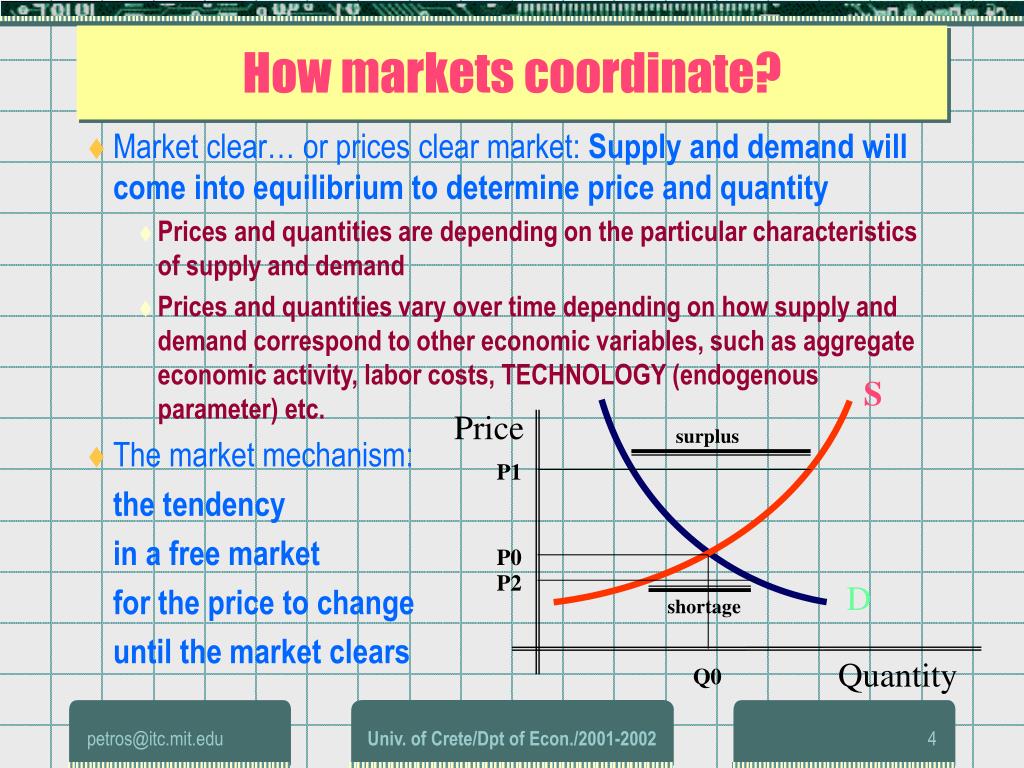
Here is the mechanism stripped down to its essentials. A shortage creates upward pressure on price. Higher prices accomplish three things at once: they ration existing supply toward the buyers who value it most, they incentivize producers to increase output, and they signal consumers to seek substitutes. The reverse happens in a surplus. This is the coordination loop, and it runs continuously across every tradable asset, service, and good. The thing most people miss is that this only works cleanly when property rights are enforced and information flows relatively freely. I ran into a case recently where a local regulatory barrier prevented a commodity from moving between two regions that both needed it. One region had a glut and prices collapsed. The other had a shortage and prices spiked. The market should have arbitraged this away instantly. It didn't, because the barrier made the trade illegal rather than unprofitable. I resolved it by restructuring the transaction through a licensed intermediary in a neighboring jurisdiction, which took about four days and cost roughly 12% of the commodity value in compliance fees. That is the hidden tax on broken coordination mechanisms.
The Hidden Costs of Coordination Failure
When the price signal is distorted, the entire coordination system drifts. This happens more often than most practitioners admit. A few common distortion sources: price controls, subsidy regimes, monopsony power, and information asymmetry so severe that one side cannot verify what the other side knows. Consider health insurance markets. The classic adverse selection problem exists precisely because patients know their own health risk better than insurers do. The price signal gets blunted because the people most likely to buy insurance are the ones insurers most want to exclude. This is not a minor friction. It is a structural flaw that can collapse the market entirely if left unchecked. Most modern systems address it through mandate structures or risk-adjusted payment models, which are messy compromises rather than elegant solutions. Another counter-intuitive point: higher prices do not always coordinate better. In markets with network effects, a price spike can trigger panic buying that amplifies the shortage, which drives prices higher, which triggers more panic buying. This feedback loop is what turned a localized lithium shortage into a global pricing spiral in early 2024. The market was coordinating, yes, but through a destabilizing positive feedback loop rather than a dampening negative one.
Get the Full Details
Practical Framework for Working With Market Coordination
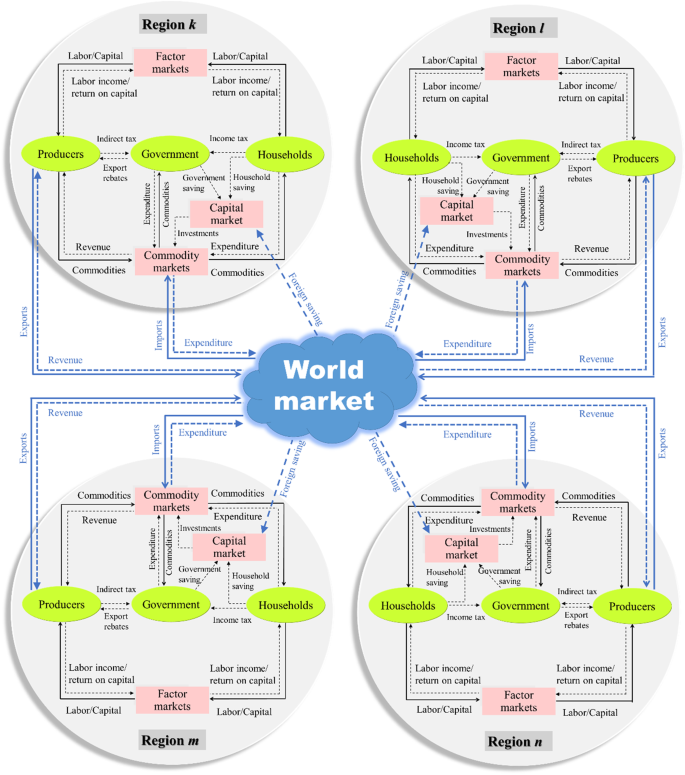
If you are making decisions in an environment where coordination matters, start by mapping the signal paths. Where does information about supply and demand actually flow? Is it through prices, through contracts, through relationships, or through something else entirely? The answer determines how fast and accurately the system can adjust. In commodity trading, I always check the basis before looking at the spot price. The basis, which is the difference between the local price and the futures price, tells you whether the coordination mechanism is functioning locally or if there is a breakdown in transport, storage, or regulation. A widening basis during normal conditions is usually a warning sign. A collapsing basis during a crisis means the market is finding its equilibrium faster than expected. For businesses, the practical takeaway is this: monitor your input prices and your output prices independently, then track the spread. A compressing spread usually means coordination is breaking down on one side of your value chain. An expanding spread with stable volumes means the market is efficiently reallocating resources toward your sector. Neither situation lasts forever, but both give you actionable information that volume data alone will never provide.
I have seen firms make the mistake of treating a temporary price dislocation as a structural shift. In 2022, several mid-market manufacturers locked in multi-year supply contracts at elevated prices because they assumed the inflationary pressure was permanent. Within eighteen months, those contracts became a serious liability as prices reverted. The market had coordinated correctly. The firms had not distinguished between a transitory signal and a persistent one.
When Markets Fail to Coordinate
No coordination system is universal. Public goods, externalities, and commons problems are the standard failures. But there are subtler failure modes worth noting. One is coordination lag. Markets coordinate eventually, but the timeline matters enormously. During the early stages of the semiconductor shortage, the price signal existed from day one. The coordination response, in terms of new capacity coming online, took approximately eighteen to twenty-four months. For industries with long capital cycles, the lag between signal and response can outlast the crisis itself. By the time the coordination completes, the underlying demand shift may have reversed, creating a new imbalance in the opposite direction. Another failure mode is signal fragmentation. In modern digital markets, prices are not uniform. They vary by platform, by user segment, by timing, and by algorithmic pricing strategies. This means the same good can have a dozen different effective prices simultaneously, each communicating a slightly different coordination signal to different participants. The aggregate outcome is harder to predict and harder to influence than in a market with a single clearing price.
For anyone working in procurement or supply chain, the workaround is straightforward: build redundancy into your coordination assumptions. Do not optimize solely for the price signal you observe today. Model what happens when that signal is delayed, distorted, or fragmented. The margin you lose to redundancy is usually smaller than the margin you lose when a single-threaded coordination strategy breaks. The mechanism itself is robust over long time horizons. Over short ones, it is vulnerable to every kind of distortion a human institution can produce. The practical discipline is learning to read the signal, filter the noise, and act before the coordination loop completes. Most people wait too long. Most firms wait too long and blame the market for being unpredictable when the actual problem was simply bad signal processing.