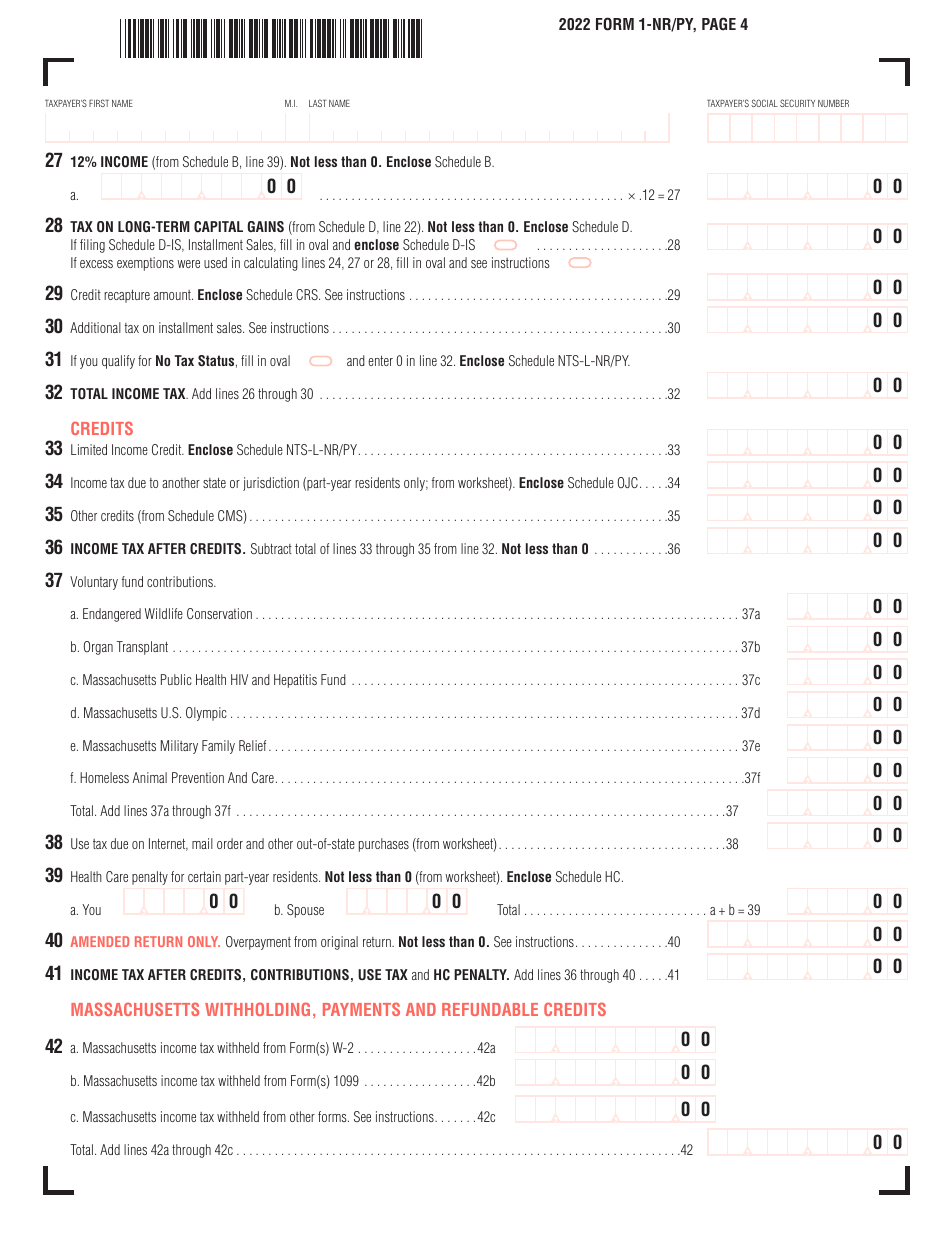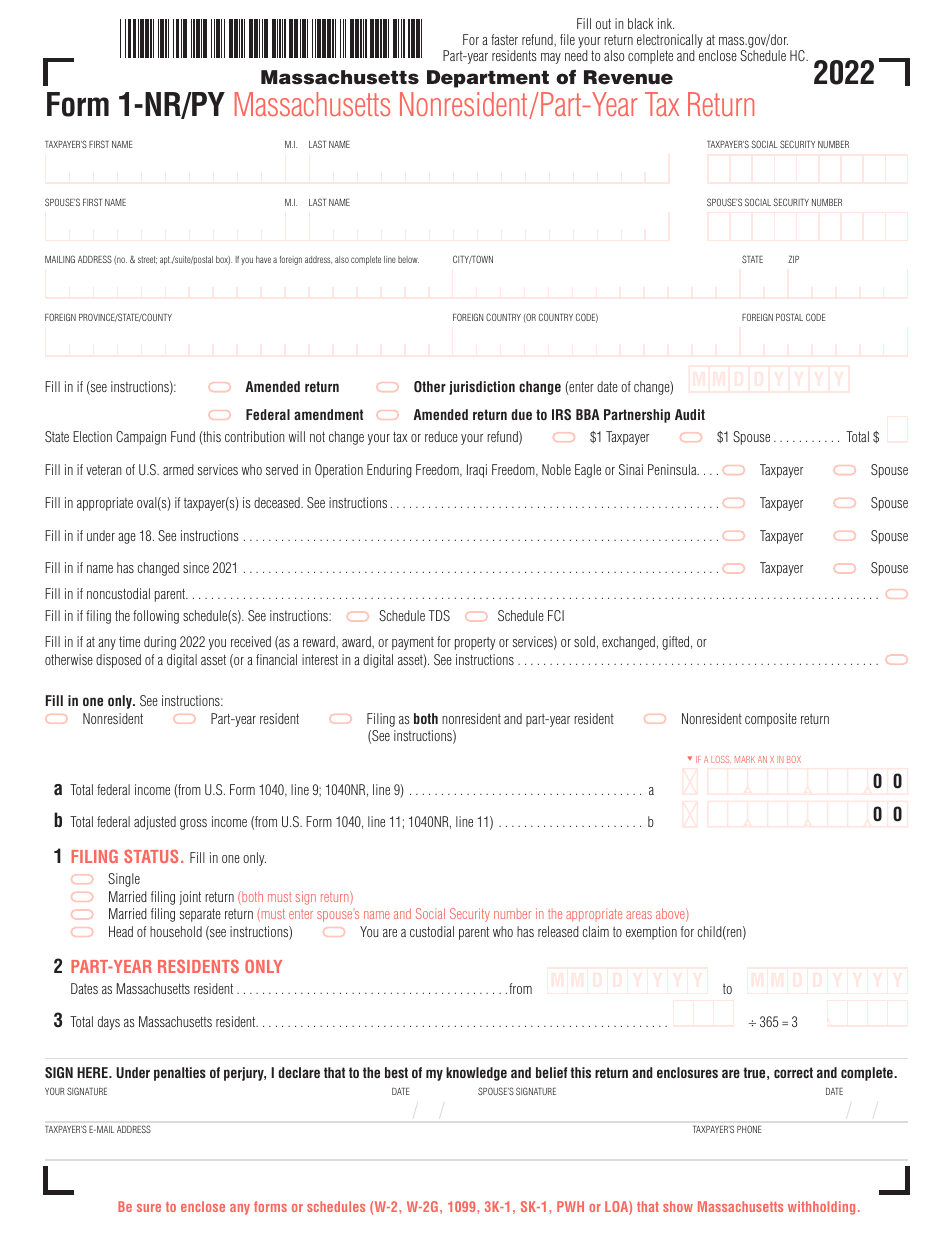
Working Through the Massachusetts Form 1 Nonresident and Part-Year Resident Instructions
The Massachusetts Department of Revenue puts out the Form 1 instructions for nonresidents and part-year residents every year, and the 2022 version covers a lot of ground that trips people up if they are not careful. I have filled these out enough times now that I know exactly where the traps are, so let me walk through how it actually works instead of just restating what the DOR pamphlet says line by line. Form 1 Nr Py applies when you either did not live in Massachusetts for the entire tax year or maintained a permanent place of abode here but spent more than six months outside the state during 2022. The core distinction matters because it determines which income gets taxed by Massachusetts and which stays with your home state. The instructions split everything into two main sections: Schedule Nr for nonresidents and Schedule Py for part-year residents. Both use the same basic framework but handle the allocation differently, and that difference is where most mistakes happen. The Massachusetts source income rules are not intuitive. Wages earned while you physically worked in Massachusetts are Massachusetts income, regardless of where your employer is headquartered or where you file your federal return. That means if you had a remote job with a Massachusetts employer but spent most of the year working from home in Florida, only the days you were physically present in Massachusetts count as Massachusetts-source wages. The DOR instructions spell this out on page 15 or so of the pamphlet, but they do not make it super obvious unless you already know how it works.
How the Allocation Actually Works in Practice
For Schedule Nr, you take your federal adjusted gross income and then multiply it by a fraction. The numerator is the Massachusetts-source income and the denominator is your total federal AGI. That fraction gets applied to your Massachusetts tax liability, and then you subtract any credits or withholding you already paid to Massachusetts. The math is straightforward. The hard part is correctly categorizing every dollar of income. Schedule Py is more complicated because you have to divide the year into two periods: the resident period and the nonresident period. Income earned during the resident period is fully taxable by Massachusetts. Income earned during the nonresident period follows the same source rules as Schedule Nr. You essentially file two mental returns and combine them, which is why the instructions include that bifurcated worksheet on pages 22 through 24. I have seen people skip that worksheet and just prorate their entire year proportionally by months, which is wrong and will almost certainly trigger a notice from the DOR. One thing the 2022 instructions do not emphasize enough is how rental income gets treated. If you own property in Massachusetts but live in New York, that rental income is Massachusetts-source regardless of where you manage the property. I learned this the hard way in 2019 when I filed using only my New York residency as the basis and got an assessment letter three months later. The workaround is simple: go through every line of your federal Schedule E and mark which properties are in Massachusetts, then allocate accordingly on Schedule Nr. It takes about ten minutes if you already have your 1099s organized.
Common Pitfalls That Will Cost You Time and Money
The most frequent error I see is mixing up the two schedules. Schedule Nr and Schedule Py look similar on the face of it, but the apportionment method is fundamentally different. If you are a part-year resident, using Schedule Nr calculations will give you the wrong number. The DOR does not reject the form at filing, so you can submit it and get an acceptance notice while still owing money. That acceptance notice is not the same as being audit-proof. Another issue is double-counting withholding. If your employer withheld Massachusetts tax from your paychecks but you are filing as a nonresident, you need to verify that the withholding only relates to Massachusetts-source wages. I had a client once who worked remotely for a Massachusetts company but lived in Connecticut for the entire year. His employer was still withholding Mass tax because the company defaulted to its home state policy. The fix was to get a written statement from the employer confirming no Massachusetts-source work was performed and then claiming a credit for the over-withholding on Schedule Nr, line 8. Without that documentation, the DOR will assume the withholding was correct and your refund gets smaller than it should be. There is also the issue of the Massachusetts personal exemption, which changed significantly in 2022 due to inflation adjustments. The standard exemption amount increased to $4,200 for single filers, up from $4,000 the prior year. If you are using tax preparation software, make sure it is updated to the 2022 figures. Older versions of common programs will still pull the 2021 exemption and understate your refund by a few hundred dollars, which is frustrating for something that should be automatic.
Get the Full Details
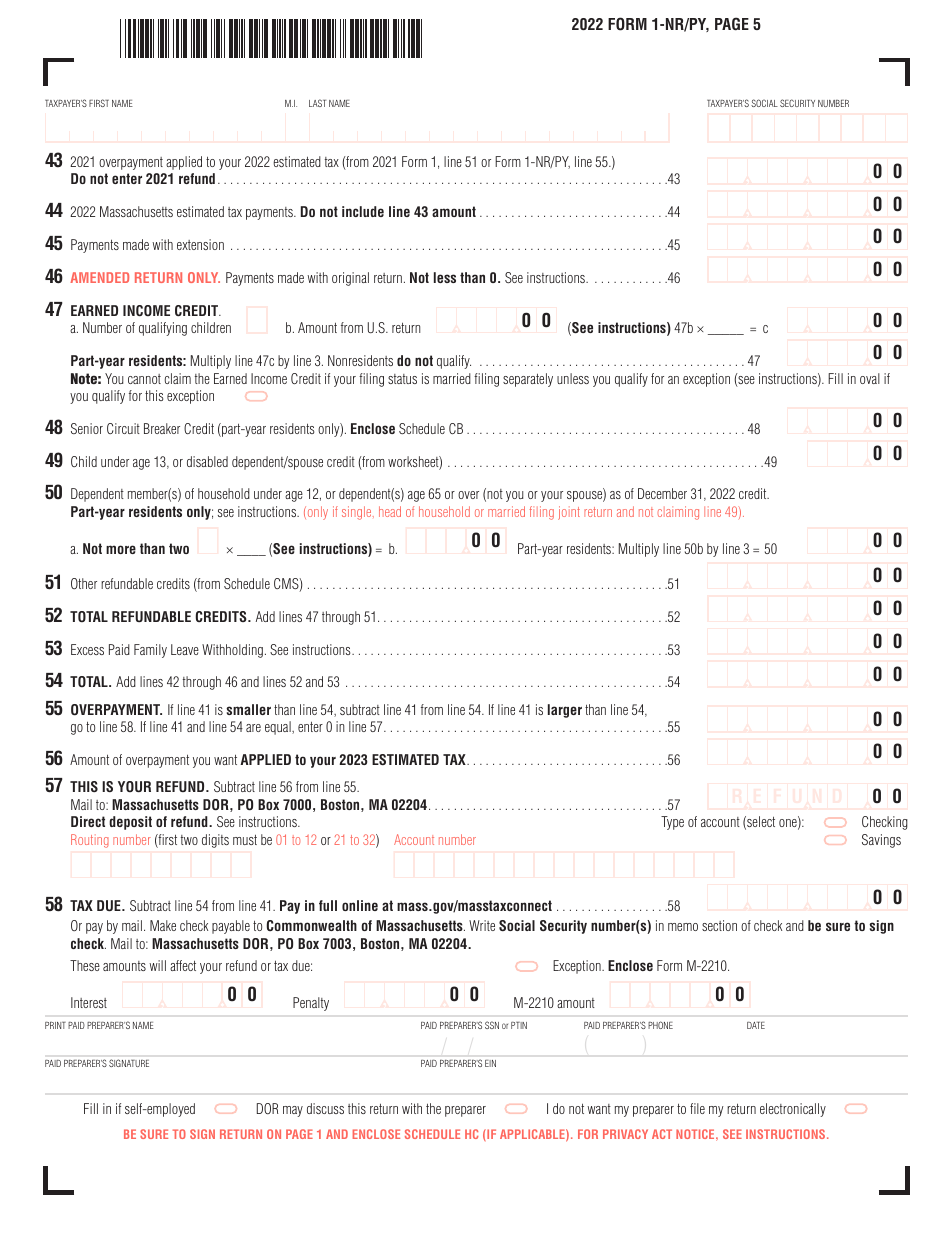
When the Instructions Fall Short
The 2022 Form 1 Nr Py instructions assume a fairly standard situation: wage income, maybe some interest or dividends, and possibly rental income. They do not adequately cover more complex scenarios like stock option income, partnership K-1s with Massachusetts-sourced items, or foreign earned income exclusions. If you have any of those, the DOR guidance is thin and you end up making judgment calls based on general principles rather than specific direction. For partnership allocations specifically, the instructions reference the federal rules but do not explain how Massachusetts treats distributive shares when the partnership operates in multiple states. The practical workaround is to file Schedule K-1 information alongside your Form 1 and be prepared to show the DOR how the allocation was determined. I recommend keeping a separate schedule that maps each partner's distributive share to the states where the underlying income was earned. This takes extra time upfront but saves you from scrambling if the DOR sends a request for documentation, which happens more often than you would expect on multi-state partnerships. The DOR does not have a dedicated nonresident help line that is easier to reach than the general hotline. Wait times can run 45 minutes or more during peak season. If your situation is straightforward, the online instructions are sufficient. If you have a messy multi-state income picture, paying for a licensed Massachusetts tax preparer for one hour of consultation is usually worth the cost. I have calculated the hourly rate on my own time spent dealing with DOR correspondence, and it comes out to roughly $200 an hour once you factor in form fill-out, research, and follow-up. A good preparer costs less than that and typically catches errors before you hit submit.