How to Actually Pass the Massachusetts P&C License Exam Without Losing Your Mind
The Massachusetts property and casualty practice exam is your gateway to selling insurance in the state. You need it if you want to write homeowners, auto, commercial property, or liability policies there. The state mandates a passing score of 75 out of 100 questions, and you get roughly 90 minutes to complete it. That sounds generous until you realize the questions aren't straightforward definitions. They are scenario-based. You will read a paragraph about a claim, a business owner, or a policy exclusion before you even see the actual question. I sat for mine in 2018 after handling insurance paperwork for small businesses for about five years, and I still got tripped up on three questions I should have known cold. Preparation starts with a pre-licensing education course. Massachusetts requires 40 hours of approved coursework. Most people burn through this in two to three weeks if they treat it like a part-time job. The curriculum covers property coverage forms, liability limits, commingling laws, and the specific statutes that Massachusetts enforces differently than other states. That last point matters more than you might think. Massachusetts has its own rating bureau rules, its own anti-rebate statutes, and a unique no-fault auto framework that shows up on the exam in ways out-of-state candidates rarely expect. Once you complete the coursework, you register with Pearson VUE. They administer the exam at testing centers across the state. You can also take it proctored remotely, though I do not recommend that route unless you have a very quiet home office and a rock-solid internet connection. I had a candidate once try the remote option during a neighborhood construction project. The proctor flagged his session when a jackhammer went off right outside his window. He had to reschedule and pay the retest fee. Just go to a center. It takes twenty minutes to check in and you walk out with a provisional score before you even leave the building.
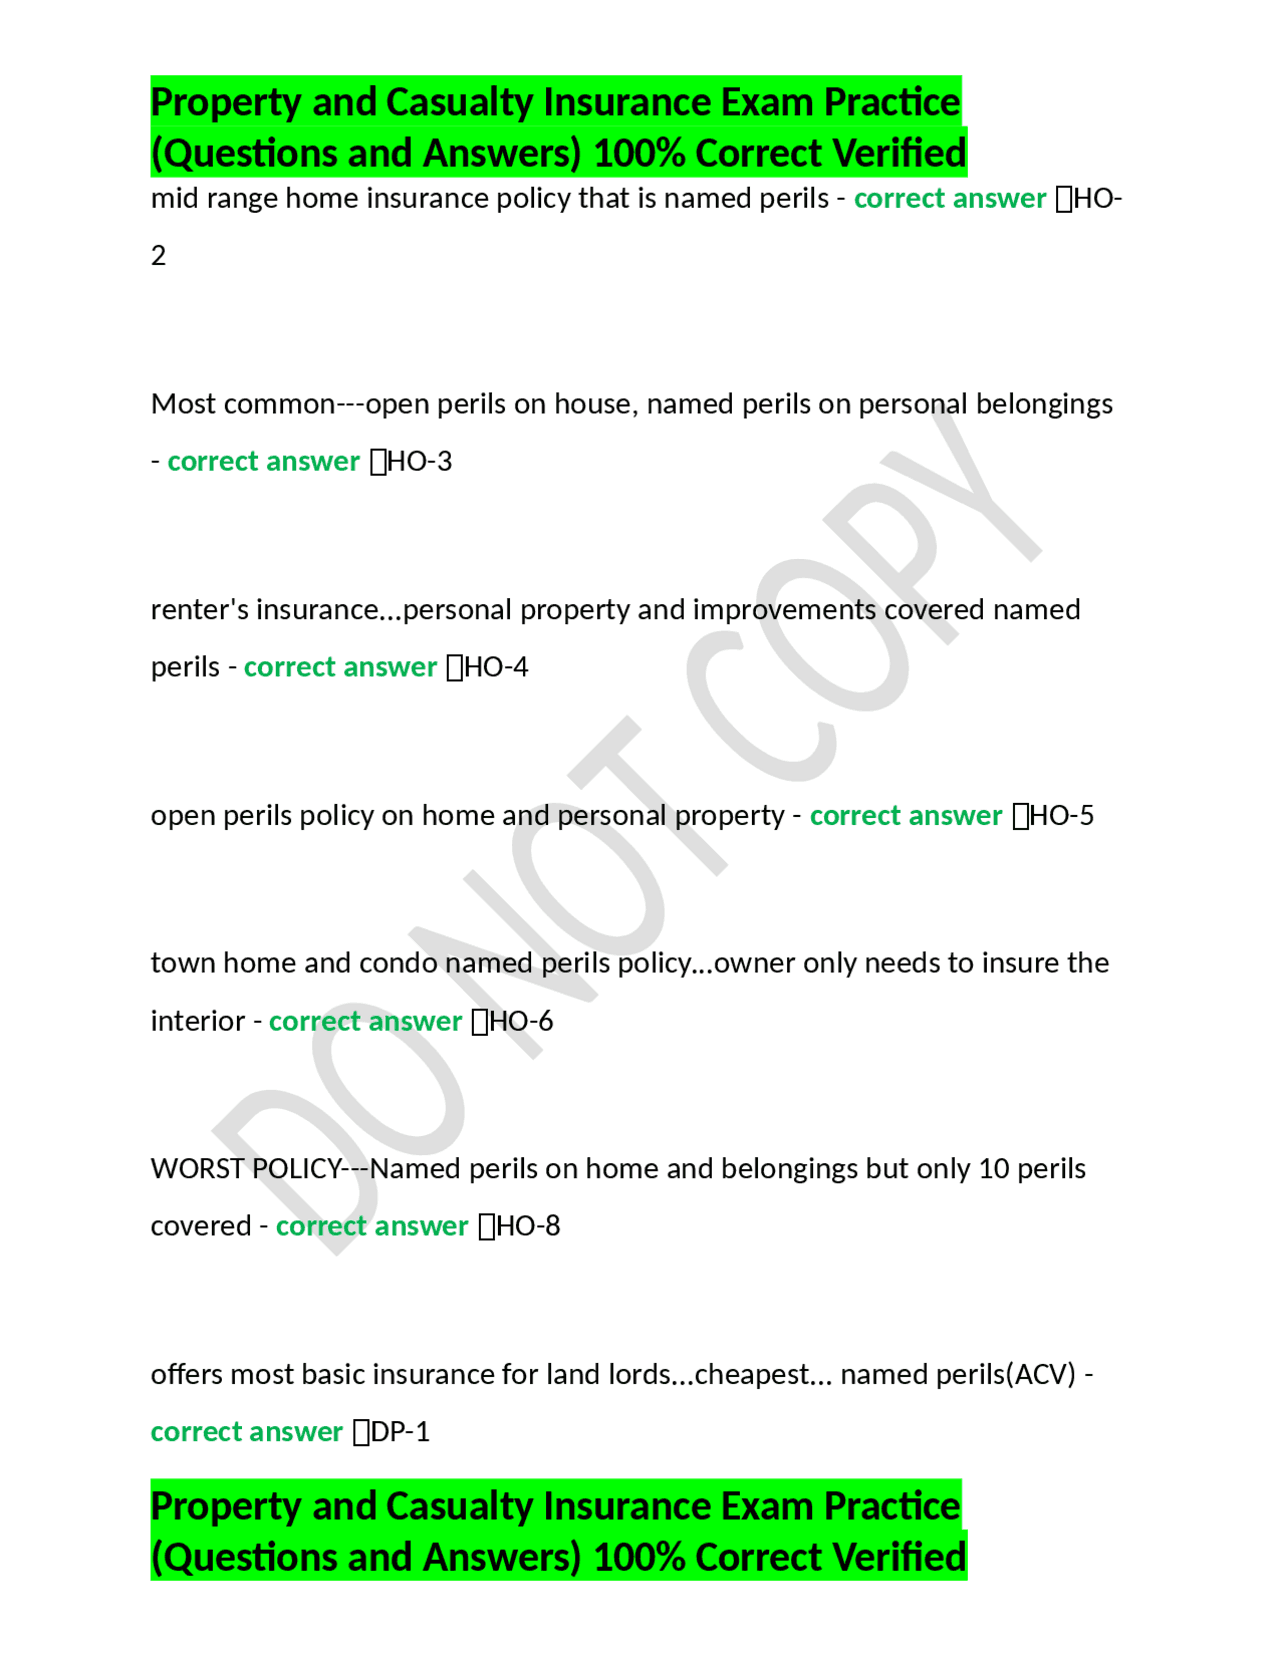
The exam itself is computer adaptive in the sense that the question bank is randomized. Two people taking the test on the same day will see different questions in different orders. The content domains break down roughly like this: property insurance covers about forty percent of the exam, liability covers thirty-five percent, the remaining twenty-five percent is split between ethics, state laws, and general insurance concepts. The property section leans heavily on ISO forms, particularly the HO series for homeowners and the DP series for dwellings. You need to know the difference between HO-3 and HO-6 cold. Not just the names. The actual coverage gaps. An HO-3 covers the dwelling on an open-perils basis while the HO-6 only covers the walls-in and personal property. That distinction comes up repeatedly.
A Specific Edge Case That Almost Cost Me a Client
Here is something I learned the hard way and it has nothing to do with the exam itself but it will save you a headache. Massachusetts has a specific endorsement requirement for windstorm and hail coverage on certain residential properties near the coast. The exam mentions coastal barriers briefly. It does not drill into the practical reality. I was handling a policy renewal for a client in Ipswich whose home sat just inland of the coastal barrier. The system auto-renewed the policy without the windstorm endorsement because the property was not technically in the flood zone. Massachusetts law requires that endorsement to be offered explicitly to coastal zone properties regardless of flood zone status. The examiner would not have caught the nuance. The system did not catch it either. I caught it only because I had dealt with a denied claim from the same neighborhood three years earlier where a tree blown onto a roof had been denied under a standard HO-3 without the endorsement. The workaround is straightforward once you know it. Run every coastal-adjacent address through the Massachusetts coastal barrier map before you bind or renew. It is a free map published by the state. It takes about ninety seconds per address and it will flag properties where the windstorm endorsement is legally required to be offered. If you skip this step you will get complaints. You will get complaints that turn into audits.
Get the Full Details
Counter-Intuitive Things About This Exam
First, memorizing definitions will not get you a passing score. The questions are designed to test application, not recall. You might see a question that asks which coverage form applies to a vacant vacation home in Cape Cod. The answer is not the standard HO-3. It is likely a DP-1 or DP-2 with specific vacancy endorsements because most standard homeowners forms contain a vacancy clause that limits coverage after thirty or sixty days of unoccupancy. If the question does not specify that the home is occupied, you assume it is vacant and the standard form drops out of consideration. This is a trap that catches people who study definitions but do not study the conditional triggers embedded in policy language. Second, the ethics and compliance section is where most candidates underperform. Massachusetts puts a heavy emphasis on the Unfair Claims Settlement Practices Act as adopted by the state. You need to know the specific timelines. Thirty days to acknowledge a claim. Forty-five days to accept or reject it. These numbers appear in multiple formats across the exam. Some questions give you a scenario with dates and ask whether the adjuster violated the statute. Others ask you to identify which practice is prohibited from a list. The prohibited practices include misrepresenting policy provisions, failing to communicate final disposition decisions, and compelling insureds to pursue litigation by offering settlements at arbitrarily low amounts. If you can list those out from memory you will handle that entire subsection comfortably.
Study Strategy That Actually Works
Take practice exams under timed conditions. Not casual practice. Sit down, set a timer for ninety minutes, and do not look at your notes. Most prep providers offer mock exams for a fee. Buy one. The questions on commercial lines endorsements are particularly brutal because the answer choices look plausible. An ISO Commercial General Liability form with a completed operations exclusion will have answer choices that differ by a single word. That single word changes whether the coverage applies. Learn to read slowly here. Underline the exclusion language in each choice before eliminating answers. Focus extra time on Massachusetts-specific content. The national portion of the exam is generic. The state portion is where you earn or lose points. Review the Massachusetts insurance code sections on licensing, producer obligations, and rate filing requirements. Do not skip the section on the Massachusetts Automobile Bill of Rights. It is a long document and it feels irrelevant to property and casualty, but it shows up. Questions aboutPIP coverage limits, medical payment thresholds, and vehicle repair standards all come from that statute.
When the Standard Approach Fails
Some people need more than forty hours of coursework. If you are coming from a completely unrelated field, or if you rely heavily on quick answers from online forums without verifying them against primary sources, the standard study path might not be enough. In that case, supplement with the official Massachusetts Insurance Department study materials and the ISO form manuals. The manuals are dry and over three hundred pages each. But the exam writes questions directly from them. A practice question about the Broad Form Dwelling policy will pull its language verbatim from the DP-1 manual. Reading the manual is not optional if you want to understand why a particular answer is correct beyond just memorizing it. The biggest limitation of this exam is that it tests knowledge but not judgment. Passing it means you know the rules. It does not mean you can handle a complex commercial risk assessment or navigate a contested liability claim. I have seen license holders who scored in the high nineties still struggle with basic endorsement selection because the exam never simulated the decision-making pressure of an actual binding scenario. The exam is a gate, not a guarantee. Treat it as such and you will be fine.