Simple Interest Is One of the Most Understood Yet Misused Concepts in Finance
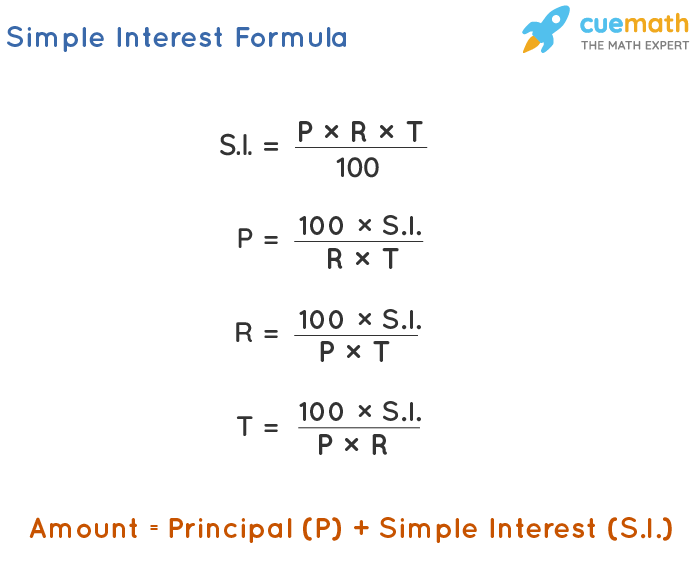
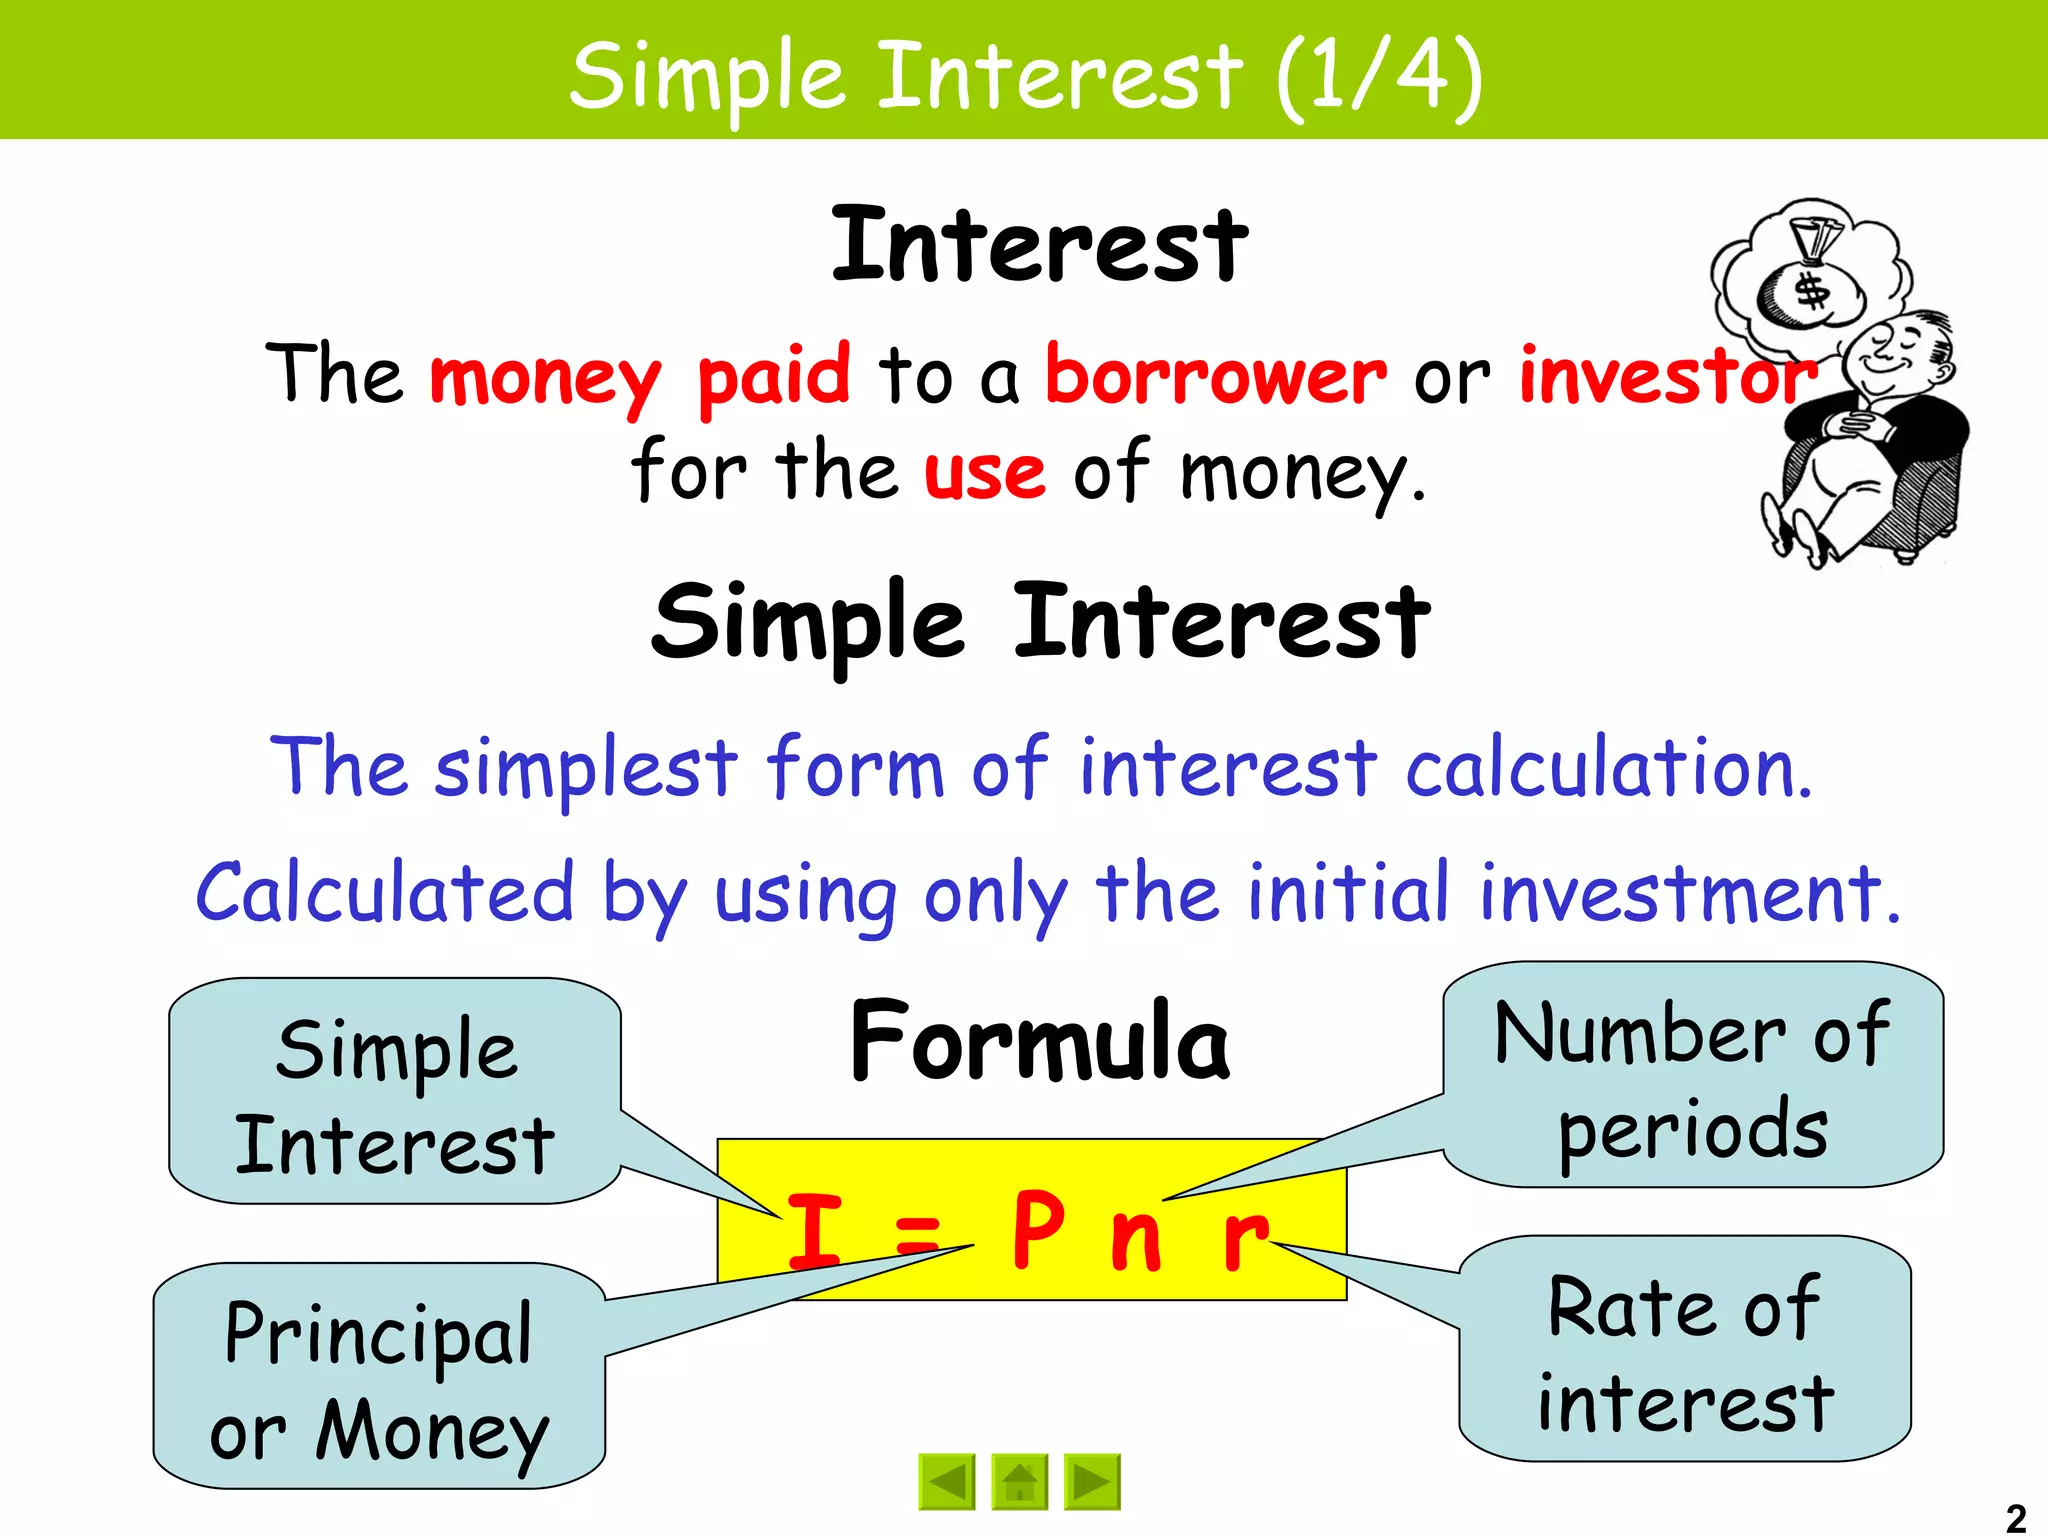
The formula itself is stupidly simple. You multiply principal by rate by time. That is it. I = P × r × t. Everyone learns this in high school or an introductory finance class, and most people never really understand what the formula is actually telling you until they have to apply it to something real. The mathematics of investment simple interest breaks down when you try to use it for anything beyond textbook problems. The formula assumes that the interest earned does not get added back to the principal at any point during the term. That is the whole premise. Interest accrues linearly, not exponentially, which means the investment never grows faster than a flat line with a positive slope.
Understanding the Mathematics Of Investment Simple Interest
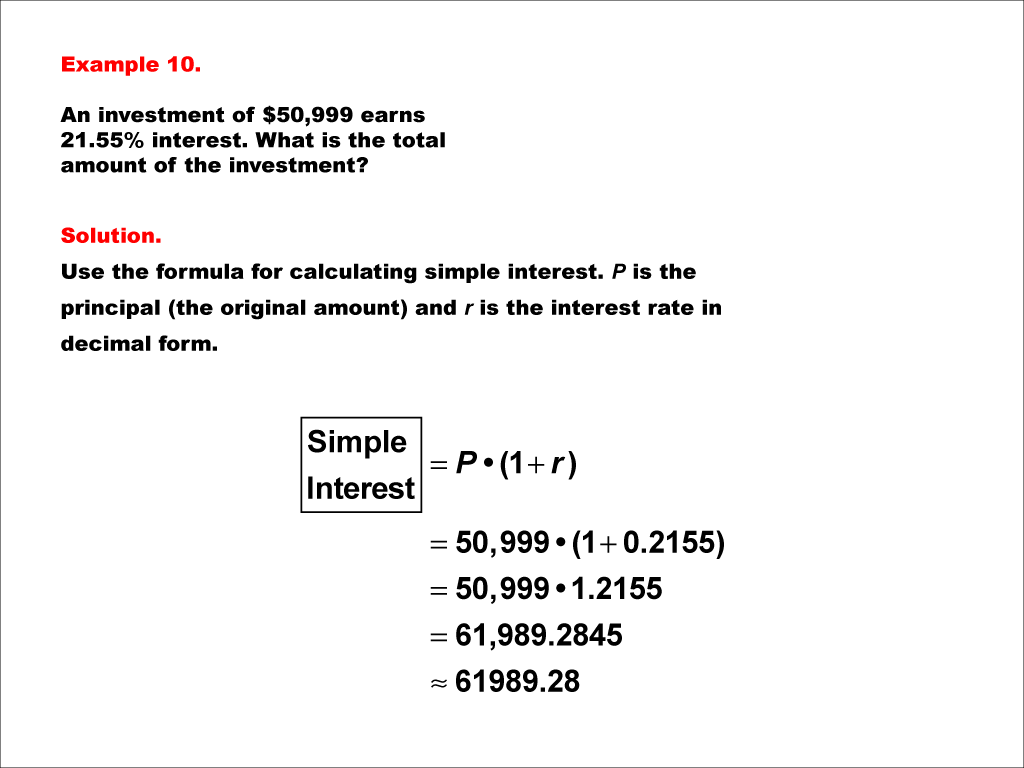
Let me walk through how this actually works before we get into where it breaks down. Say you invest $10,000 at 6% annual simple interest for 3 years. Each year you earn exactly $600. Not $600 plus a little more each year because the previous year's interest got folded in. Just $600. After three years, you have $11,800 total. The math is straightforward. What most people miss is that the rate and time units need to match. If the rate is annual but you are investing for 9 months, you do not just plug in 9. You use 9/12 or 0.75. I have seen people plug in 9 directly and then wonder why their answer was three times what it should have been. It happens more often than you would think, especially on certification exams where they deliberately test this. When dealing with days instead of months or years, the convention matters. Some instruments use a 360-day year while others use 365. The difference is small on short-term notes but it compounds, literally, over larger principals. I worked on a commercial loan file once where the borrower and the bank disagreed on the day-count convention for a 45-day treasury bill equivalent, and the dispute came down to roughly $18 on a $500,000 principal. Nobody wanted to fight about $18, so we just split the difference and moved on, but it was a good reminder that the fine print on day-count conventions is not just paperwork.
The actual calculation steps are minimal. First, identify the principal amount. Second, convert the interest rate to decimal form by dividing by 100. Third, express the time period in the same unit the rate is based on. Fourth, multiply them together. That gives you the interest. Add that to the principal for the total maturity value. Here is a practical example that comes up fairly often. You lend someone $2,500 at 4% simple interest for 180 days using a 360-day year convention. The rate in decimal is 0.04. The time is 180/360, which is 0.5 years. The interest is $2,500 × 0.04 × 0.5 = $50. The total repayment is $2,550. That is all there is to it. Now let us talk about where this gets complicated. Simple interest is fundamentally linear, and that linearity is both its greatest strength and its biggest limitation. For short-term loans and certain bonds, it works fine. For anything stretching beyond a year or two where the goal is wealth accumulation, it is a poor choice because it ignores compounding entirely. You are leaving money on the table every single period that interest could have been reinvested.
Get the Full Details

One counter-intuitive point that trips people up: a simple interest rate and a compound interest rate can appear identical on paper but produce very different outcomes. If someone offers you 8% simple interest versus 8% compounded annually, the compound version pulls ahead immediately in year two and the gap widens every year after. The simple interest version stays flat. The nominal rate is the same but the effective yield is completely different. Another thing beginners rarely grasp is how simple interest behaves with partial payments. If you make a payment partway through the term, the interest recalculates on the remaining principal from that point forward. This is called the United States Rule for partial payments, and it is the standard method taught in business mathematics courses. You calculate interest on the original principal up to the payment date, subtract the payment from the accumulated amount, and then carry the new balance forward. It is not as clean as the basic formula, but it is still manageable. I ran into an edge case a few years back involving a simple interest note that had been discounted before maturity. The holder wanted to sell it to another party, and the question was what price would give the buyer a yield equivalent to a certain discount rate. The straightforward approach of just applying the simple interest formula to the remaining time and then discounting backwards gave a result that felt slightly off. The issue was that the discount was being applied to the maturity value rather than treating the remaining cash flow properly. I resolved it by calculating the maturity value first using the simple interest formula, then applying the discount factor to the present value of that maturity amount. The difference was about $3.42 on a $12,000 note, which sounds small but mattered to the client. It was a good reminder that simple interest calculations can sit inside more complex scenarios and you need to be careful about which value you are discounting.
There are also situations where simple interest is explicitly mandated or standard practice. Banker's acceptances, some types of commercial paper, and certain short-term government instruments use simple interest by convention. In those cases, you are not choosing the method. You are just applying it correctly. The key is knowing when you are in one of those frameworks versus when you are dealing with an investment that should be evaluated on a compound basis. Common pitfalls worth noting. The first is confusing the annual rate with the periodic rate. If interest is stated as 12% per annum but calculated monthly, the monthly rate is 1% not 12%. Plugging 12 in as the monthly rate is a classic error that inflates the answer twelvefold. The second is forgetting to convert the time to the correct unit. The third is assuming that simple interest and compound interest are interchangeable for comparison purposes. They are not. A 7% simple interest rate over 5 years is not the same as a 7% compound interest rate over 5 years. The compound version will always be higher, and the difference becomes significant the longer the horizon. If you need to calculate this manually, grab a calculator and work through the steps in order. Do not skip converting the rate to a decimal or adjusting the time to match the rate's period. If you are doing this repeatedly, a spreadsheet with the formula =principal * rate * (days/360) will save you from making arithmetic errors, though you still need to verify your inputs.
The mathematics of investment simple interest is not going away. It is embedded in a lot of short-term financial products and it appears in virtually every introductory finance curriculum. Understanding it deeply means knowing not just the formula but when it applies, when it fails, and how to adjust it for the realities of partial payments, day-count conventions, and pre-maturity discounting. The formula is easy. Using it correctly in practice is what takes the work.