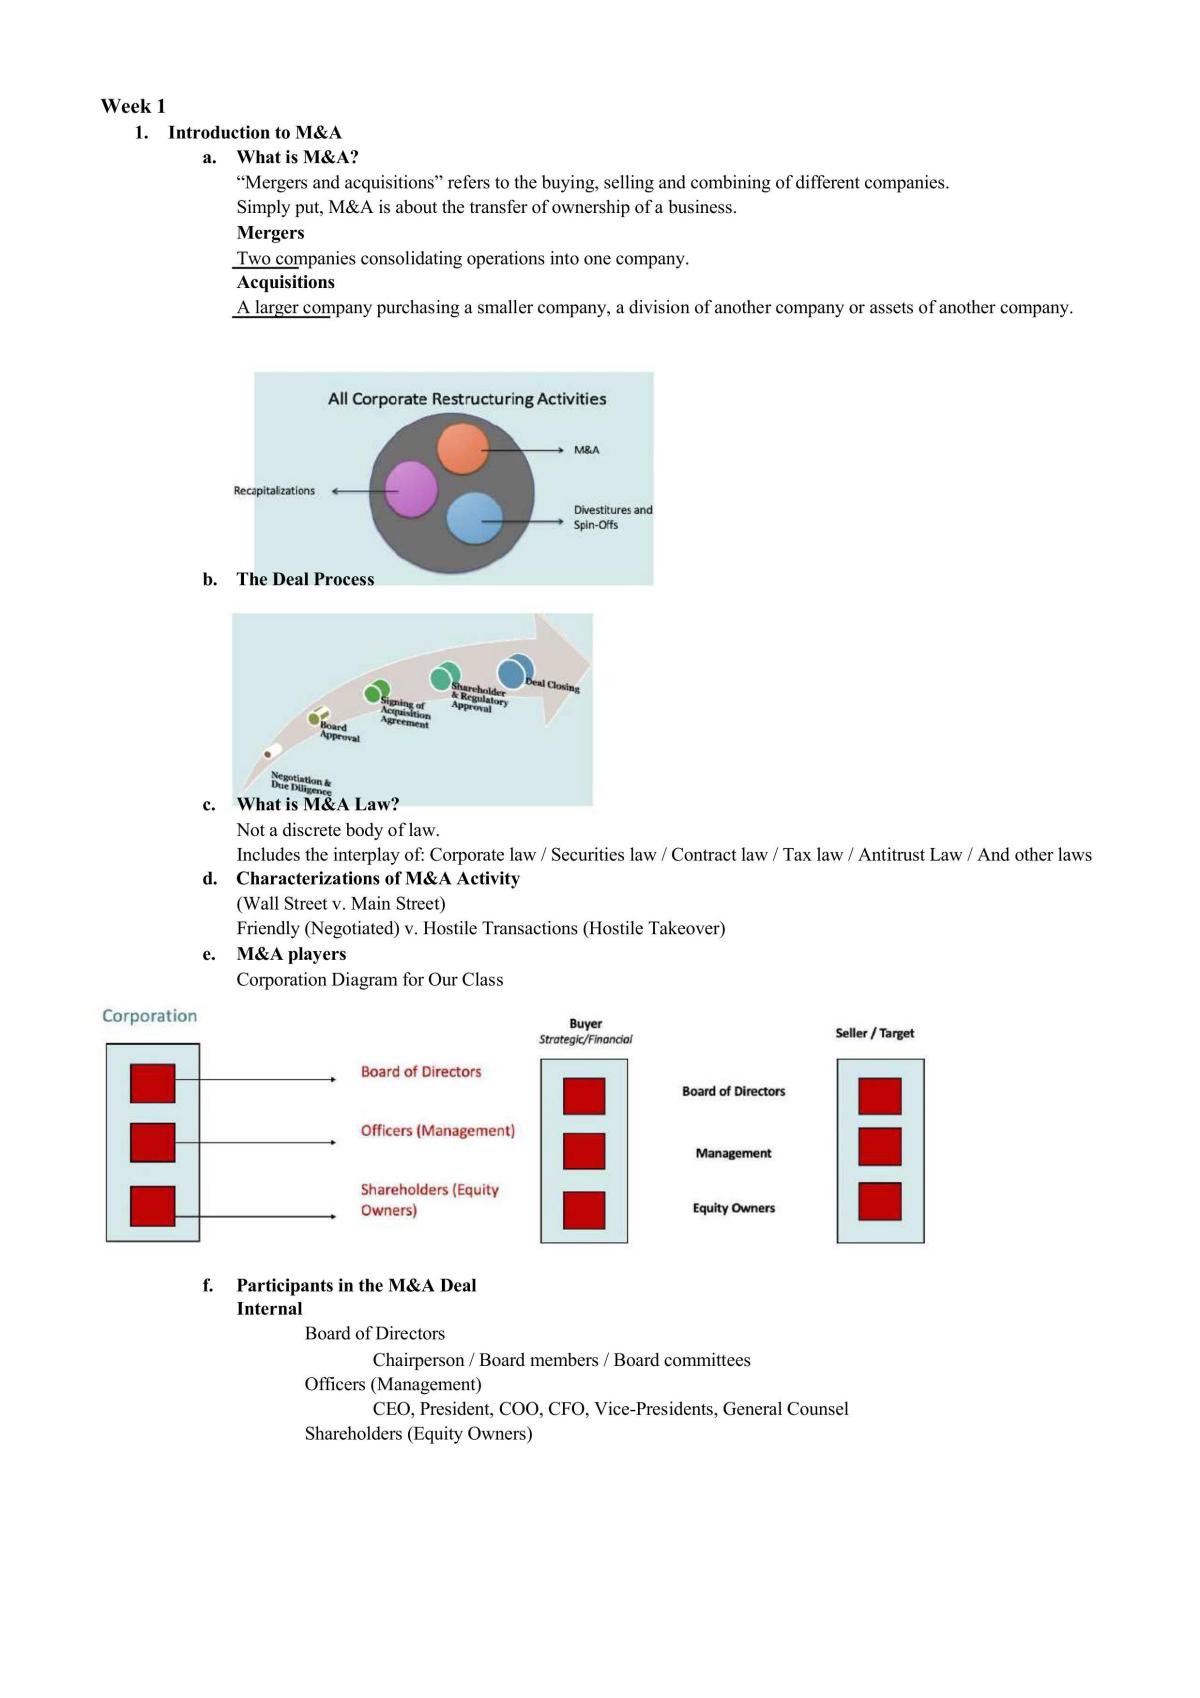
What Actually Matters When Studying M&A for Law School
Most students waste weeks on M&A because they try to memorize every case instead of learning the framework. The doctrine is deceptively narrow once you strip away the 300-page textbook chapters. You need to understand three things: what standard of review applies, when it applies, and what the plaintiff's counsel will allege to trigger it. Everything else is support. I built my Mergers And Acquisitions Outline Law School notes around that framework, and they cut my revision time from roughly a full week down to about three days. Not because the cases got simpler, but because I stopped treating every case as equally important. Most of them just restate the same test with different facts.Mergers And Acquisitions Outline Law School: Core Structure
Start with the Revlon duty. That is your anchor point. When a company is changing control, the board shifts from preserving corporate longevity to maximizing shareholder value. The entire section on director liability in change-of-control transactions flows from that single principle. Everything before Revlon is business judgment rule stuff. Everything after it is enhanced scrutiny. The key cases you actually need to know are Revlon itself, Unocal, Trans Union, and Weinberger. Those four cases cover about 80 percent of exam questions. The rest are variations or applications. If you can explain Unocal's two-prong test without looking at your notes, you are in good shape. The first prong requires a legitimate threat. The second prong requires the response to be reasonable relative to the threat. That second prong is where most students lose points because they conflate reasonableness with proportionality or just describe the board's motive instead of measuring the response against the threat. For transactions, you need to distinguish between a statutory merger, a stock purchase, and a tender offer. The procedural requirements differ. A merger requires board approval and shareholder vote. A stock purchase can sometimes happen without a shareholder vote depending on state law and the certificate of incorporation. A tender offer has its own disclosure regime under Section 14(d) of the Securities Exchange Act and Rule 14d-9. Professors love to mix these on exams and ask what happens when a board tries to use a poison pill to block a tender offer that would have triggered Revlon duties. That happened in reality with Moran v. Household International, and the Delaware Supreme Court upheld the pill's use pre-bid but made clear it cannot be used to permanently block a value-maximizing transaction.
I ran into a specific problem when compiling case summaries. Many treatises describe the exact same facts in different ways, and the subtle differences matter on exams. I had a professor who liked to test on whether the board in Unocal had actually considered the adequacy of the tender offer price, not just whether it was a coercive threat. The opinion mentions the price inquiry but does not resolve it definitively. Students who memorized the broad strokes missed that nuance entirely. I went back to the full transcript and court records to pin down exactly what the board did and did not consider at each step. That took about four extra hours but saved me from presenting a flattened version of the case that would have been legally inaccurate. Here is a counter-intuitive point that rarely gets emphasized: the business judgment rule is not the default at every stage of a transaction. It only applies when the board is not under Revlon pressure and has not created a defensive situation that requires Unocal review. A board that adopted a poison pill without a credible threat does not get business judgment deference on subsequent decisions about the pill's redemption. That distinction shows up in questions about whether a board can switch from Revlon mode back to ordinary business judgment after a deal falls through. The answer is yes, but only if the change-of-control event has genuinely been abandoned, not just paused. I found this in MacMillan, Inc. v. Edison Holdings Corp., where the court described the shift as possible but noted it is not automatic and depends on the factual record. Another thing beginners consistently miss is the difference between entire fairness review and enhanced scrutiny. They are not the same. Enhanced scrutiny under Unocal or Revlon means the board bears the burden of proving reasonableness. Entire fairness means the board bears the burden of proving both fair dealing and fair price. Entire fairness is the higher standard and applies in conflicts of interest situations, not just change-of-control transactions. If a controlling shareholder is on both sides of a merger, you get entire fairness, not just Revlon review. Students confuse these constantly, and exam graders notice.
The disclosure side is another area that deserves more attention than it gets. Section 14(a) of the Exchange Act and Rule 10b-5 create liability for materially misleading statements in proxy materials. Mills v. Electric Auto-Lite is the leading case, and it established that the correctness of the valuation analysis in a merger proxy is not the issue. The issue is whether the proxy contained a material omission. That distinction matters because it means even a perfectly reasoned merger can violate disclosure obligations if the proxy omits key information. I spent too long early on trying to reconcile valuation fairness with disclosure liability, and my professor pointed out that they are separate legal questions. The reconciliation is that one governs the economic terms and the other governs the information environment. Both can fail independently. If you are preparing for an exam, I would recommend building your outline in this order: Revlon duty first, then Unocal standard, then transaction types and procedures, then disclosure claims, then entire fairness conflicts. That mirrors how the cases actually build on each other. Going backwards through that sequence makes the doctrine feel disjointed because later cases assume you already know the earlier ones. One limitation of the Delaware approach is that it does not account well for multi-jurisdictional deals. If the target is incorporated in one state, listed on an exchange in another, and the acquiring firm is headquartered in a third, the applicable fiduciary standards can diverge. Delaware courts generally apply their own law to fiduciary duty questions for Delaware corporations, but federal securities claims are a different story. This comes up in practice and occasionally on exams. If your course covers this, know that federal claims survive state law preemption analysis and can proceed independently.
Get the Full Details
A practical study method that works: take each major case and write one sentence answering who won, what standard applied, and why. If you cannot do that, you have not internalized the holding. Then take the next case and do the same, noting whether it applies the same standard or a different one. You will quickly see that roughly half the cases are applying Revlon and the other half are applying Unocal, with a few throwing in entire fairness for conflict situations. That pattern recognition is what separates students who cram from students who actually understand the doctrine.