What the Missouri Property And Casualty Exam Actually Tests
The Missouri P&C exam covers a broad range of topics, but it isn't as scattered as it looks on the surface. There are really four buckets: property coverage, casualty coverage, insurance contract basics, and Missouri-specific insurance law. The exam pulls questions from each, and the ratio shifts slightly depending on which version of the test you get on exam day. You're looking at around 100 scored questions, though a few unscored items might be mixed in. You have somewhere between 120 and 150 minutes depending on Prometric's scheduling. The passing score is 70 percent, which means you need roughly 70 right answers out of 100. One thing most people don't realize is that the exam doesn't test whether you can recite policy language word for word. It tests whether you can apply coverage provisions to a fact pattern. A typical question will describe a scenario — a kitchen fire in a rental unit, a slip-and-fall at a small retail shop, a flood damage claim on a homeowner's policy — and then ask what applies. If you memorize definitions without practicing application, you'll struggle with the wording. The questions deliberately use tricky phrasing like "most likely" or "under the standard ISO form," and they expect you to pick the best answer, not a technically correct but irrelevant one.
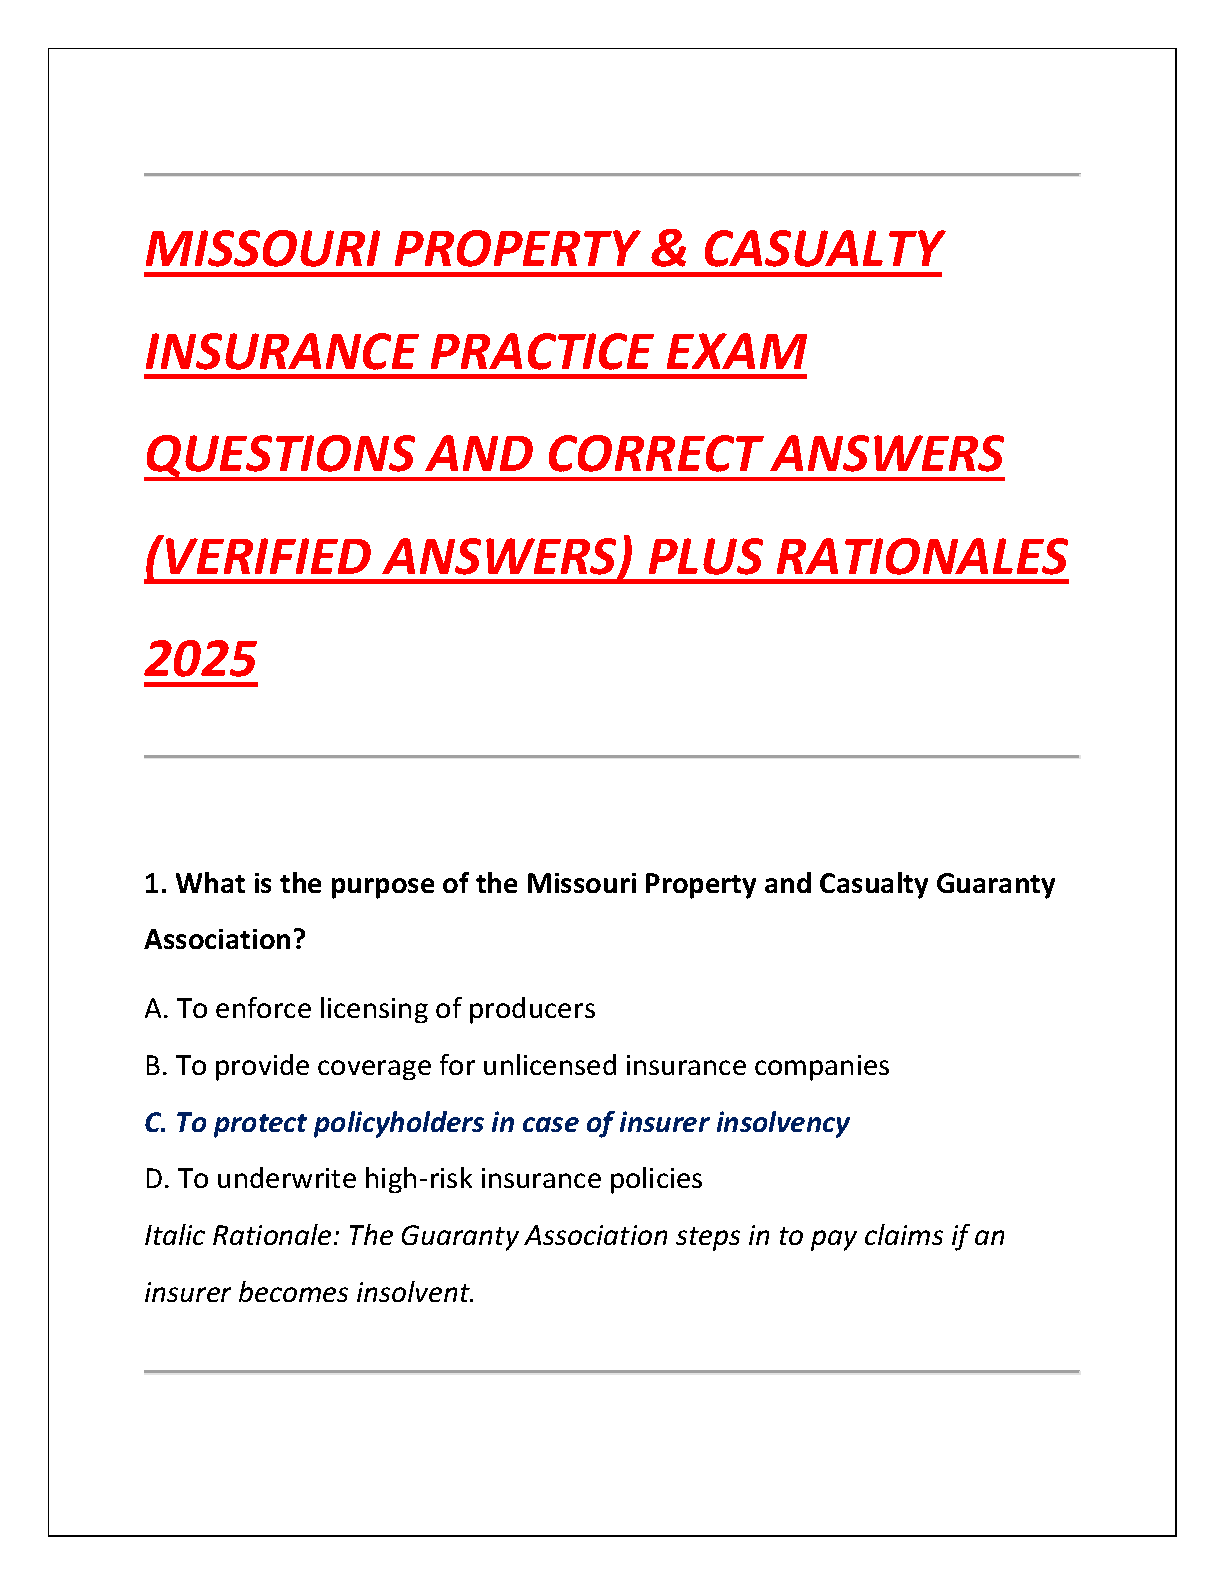
Missouri Property And Casualty Exam Questions You Should Practice With
When I was prepping for this, I went through three main sources: the pre-licensing course materials, the official exam prep book from the state-licensed provider, and a set of third-party practice questions. The practice exams matter more than anything else for building speed. The real exam has a lot of long stems with four answer choices that all look plausible at first glance. You need to train yourself to read past the distractors quickly. I timed myself on practice sessions and aimed for under 90 seconds per question. If you're taking more than two minutes on a single question during practice, you're not ready to walk into the testing center. There's a specific edge case that caught me off guard during my first practice run. The exam includes questions about the Missouri Insurance Guaranty Association and how it handles insolvent carriers. Most candidates skim over this because it's dry and not covered deeply in the pre-licensing class. I ran into a question where a policyholder's insurer became insolvent and the question asked about the coverage limits provided by the state guaranty association. The answer involved knowing that Missouri provides up to $300,000 per claimant for property and casualty claims, with a $1 million cap per insolvent company. I had marked that section lightly and got it wrong. After that, I went back and spent an afternoon specifically studying the guaranty association provisions and the state's unfair trade practices section, which also showed up more heavily than I expected. For the property side, focus heavily on HO forms. The difference between HO-3 and HO-5 is fair game, and so is the concept of extended replacement cost versus guaranteed replacement cost. These are easy points if you know them. One counter-intuitive detail: many people think guaranteed replacement cost is always the better coverage, but that's not true anymore. Most standard HO-3 policies now come with extended replacement cost as the default, and guaranteed replacement cost is usually an endorsement you have to specifically request. The exam will sometimes describe a situation where extended replacement cost would be insufficient for a severely damaged home in a area with rising construction costs, and the answer choices will test whether you know which coverage tier actually solves that problem. It's a nuance that separates candidates who have read the actual policy forms from those who just watched a video summary.
On the casualty side, the CGL form is where most of your questions will come from. Understand the coverage parts A, B, and C clearly — personal and advertising injury is something people consistently get wrong because it sounds similar to bodily injury but covers different harms like libel and slander. The examination doesn't ask you to quote ISO wording, but it does ask you to identify when coverage is triggered and when it isn't. A common trap question involves operations completed and ceased — if a contractor finishes a job and the property damage shows up two years later, the exam wants to know whether the policy in effect at the time of the work or the policy in effect when the damage was discovered responds. The answer depends on whether it's occurrences-based or claims-made coverage, and the CGL is occurrences-based, so the policy on the risk at the time of the incident responds. This distinction comes up frequently and most people flip it. Another area that tends to trip people up is the relationship between the premium calculation and the classification of the business. In Missouri, property insurance premiums are adjusted based on construction type, occupancy, and protection class. The exam will give you a scenario with a specific construction classification and ask what rating factor applies. If you know the basic construction classes — frame, pre-engineered metal, masonry — and how they map to premium adjustments, you'll save time on those questions. I found that making a one-page reference sheet with the construction classes and their general rate impact helped me move through those questions faster than re-deriving the logic each time. There are practical limitations to keep in mind. The exam is computer-adaptive in the sense that the difficulty scales slightly based on your performance, but the pool of questions is large and randomized. You can't predict which topics will dominate your specific test form. The biggest bottleneck for most people isn't knowledge — it's reading speed and question management. Some of the longer stem questions contain redundant information that you have to filter through. I've seen candidates leave the last ten questions unanswered because they ran out of time. That's not a knowledge problem. It's a pacing problem. During practice, work on flagging questions you're unsure about and moving on. The testing system lets you return to flagged questions, so you don't have to lock in an answer immediately.
Get the Full Details
Some prep materials oversell themselves. A few of the cheaper question banks I looked at contained outdated policy references that no longer match current ISO forms. Check the publication date on whatever study guide you buy. If it's older than two years, verify the answers against current material before trusting them. The Missouri Department of Insurance regulates these forms and they do update periodically, particularly around property valuation methods and liability limits. An outdated answer key will mislead you on a topic that's actively tested. The registration process for the exam goes through the state's licensing portal and you need to complete the pre-licensing education requirement before you can schedule. Most people finish the course, wait for the confirmation to appear in the system, then book the Prometric appointment. The whole timeline from course completion to exam date is usually one to two weeks depending on seat availability in your area. If you're trying to schedule for a week when lots of other new agents are also testing, book early. Seats fill up fast in late summer and early fall when a lot of new agents are pushing through. For the actual exam day, bring two forms of ID. One has to be photo identification. The testing center will confiscate anything electronic, including your phone and smartwatch. They also don't allow notes or reference materials at the desk. If you wear glasses, they'll let you keep them on. The testing room is quiet and partitioned, which helps but also makes it feel a bit sterile. The timer is visible on screen. You can request a break, but the clock keeps running during breaks, so short water breaks are the only practical choice unless you genuinely need to reset your focus.
If you don't pass, you can retake the exam after seven days. There's no limit on attempts, but each retake requires a new fee and a new scheduling action through the same system. Most people who fail do so because they underprepared on the Missouri law section or because they let the pacing collapse in the second half of the exam. Both are fixable with targeted review and timed practice sets. I've seen candidates go from a 58 on a practice exam to a 76 on the real thing after switching to a mix of longer practice sets and shorter topic-specific quizzes for their weak areas. The exam itself is a standard multiple-choice format. No essays, no calculations beyond basic premium and deductible math, and no scenario-based open-ended questions. It's straight A through D selection. The content is heavy on application rather than pure recall. You'll encounter questions about named perils versus open perils, additional insured endorsements, subrogation rights, deductible structures, and how the various policy forms interact with each other in a layered claim situation. The trickiest questions combine two or more concepts in a single stem, so you have to hold multiple pieces of information in mind at once while reading. That's why practice under timed conditions is non-negotiable. Reading slowly and carefully during the exam is fine. Reading slowly during practice is the habit you want to break before test day. If you're currently studying, prioritize the areas where you get questions wrong on practice exams rather than reinforcing what you already know. I tracked my errors across three full practice exams and spent the remaining prep time exclusively on the topics where my accuracy dropped below 60 percent. My property coverage score went from about 55 percent to 82 percent in the final week before the exam. My casualty score was already above 70 and barely moved. Concentrating effort where it actually improves your total score matters more than a balanced review approach. The exam rewards weighted preparation.
After passing, your license comes through the state's e-licensing system and typically takes a few business days to appear in active status. You'll need to complete your appointment paperwork with a sponsoring company before the license can be fully activated for producing business. That's a separate step from the exam itself, but it's part of the full licensing workflow. Make sure you know which company you're appointed with and have your fingerprints cleared if that hasn't happened yet, since the background check can delay activation even after you pass the exam. The whole process is straightforward if you treat it like a practical skill rather than a memorization exercise. The exam is designed to verify that you understand basic policy concepts and can apply them, not that you can recite statutes. Focus on the application questions, pace yourself, and make sure you're using current study material. That's what separates people who pass on the first attempt from the ones who spend another week going back through the books.