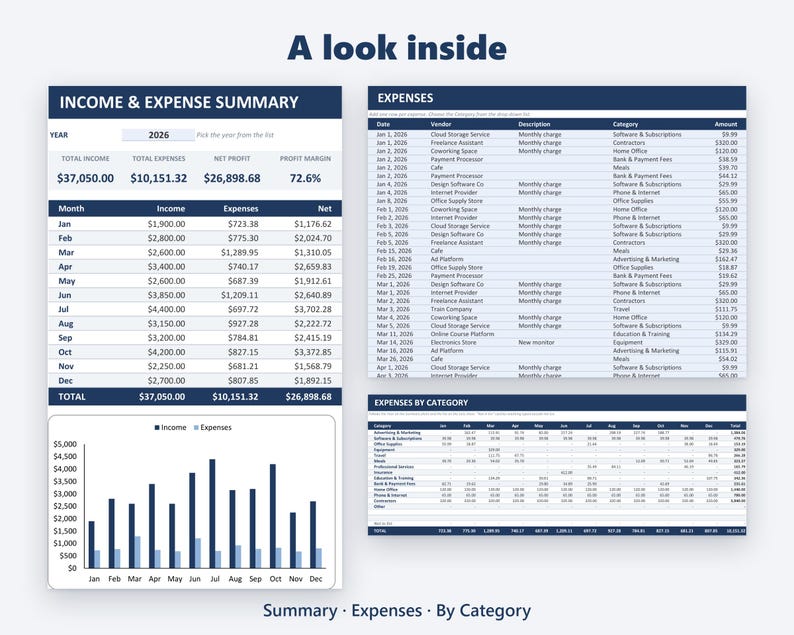
The Spreadsheet I Actually Use Every Month
I stopped trying to budget with apps around 2019. They either demanded too much daily data entry or they guessed wrong about how my irregular income would land. So I built a simple spreadsheet that sits on my desktop and takes about twelve minutes to update each month. It has two sheets: income and expenses. That is it. A Monthly Income And Expenses Worksheet is just a structured table where you record what came in and what went out during a calendar month. Nothing fancy. The trick is making it actually reflect reality instead of your optimism about next month.
How to Set Up a Monthly Income And Expenses Worksheet
Create columns for date, description, category, amount, and payment method. Keep the categories fixed so you are not inventing new ones every time you enter a transaction. I use about twenty-five categories across housing, transportation, food, healthcare, debt, savings, and discretionary spending. On the income side, list salary, freelance payments, investment returns, and any other cash inflows. If your income is unpredictable, add a column for projected versus actual and note the variance. That variance column saved me last March when a freelance client paid forty percent late and I had already allocated that money to a bill. For expenses, categorize fixed costs first. Rent, insurance, loan payments. Then variable costs. Groceries, gas, utilities. Finally, irregular expenses that you must amortize yourself because your bank statement will not show them coming. car registration, annual subscriptions, holiday gifts. I divide each by twelve and subtract a small buffer, usually five percent, to account for timing differences.
The math is straightforward. Total income minus total expenses gives you your net for the month. If the number is negative, you identify which category ate the most and adjust next month. If the number is positive, route it into savings or debt paydown. Repeat.
Get the Full Details
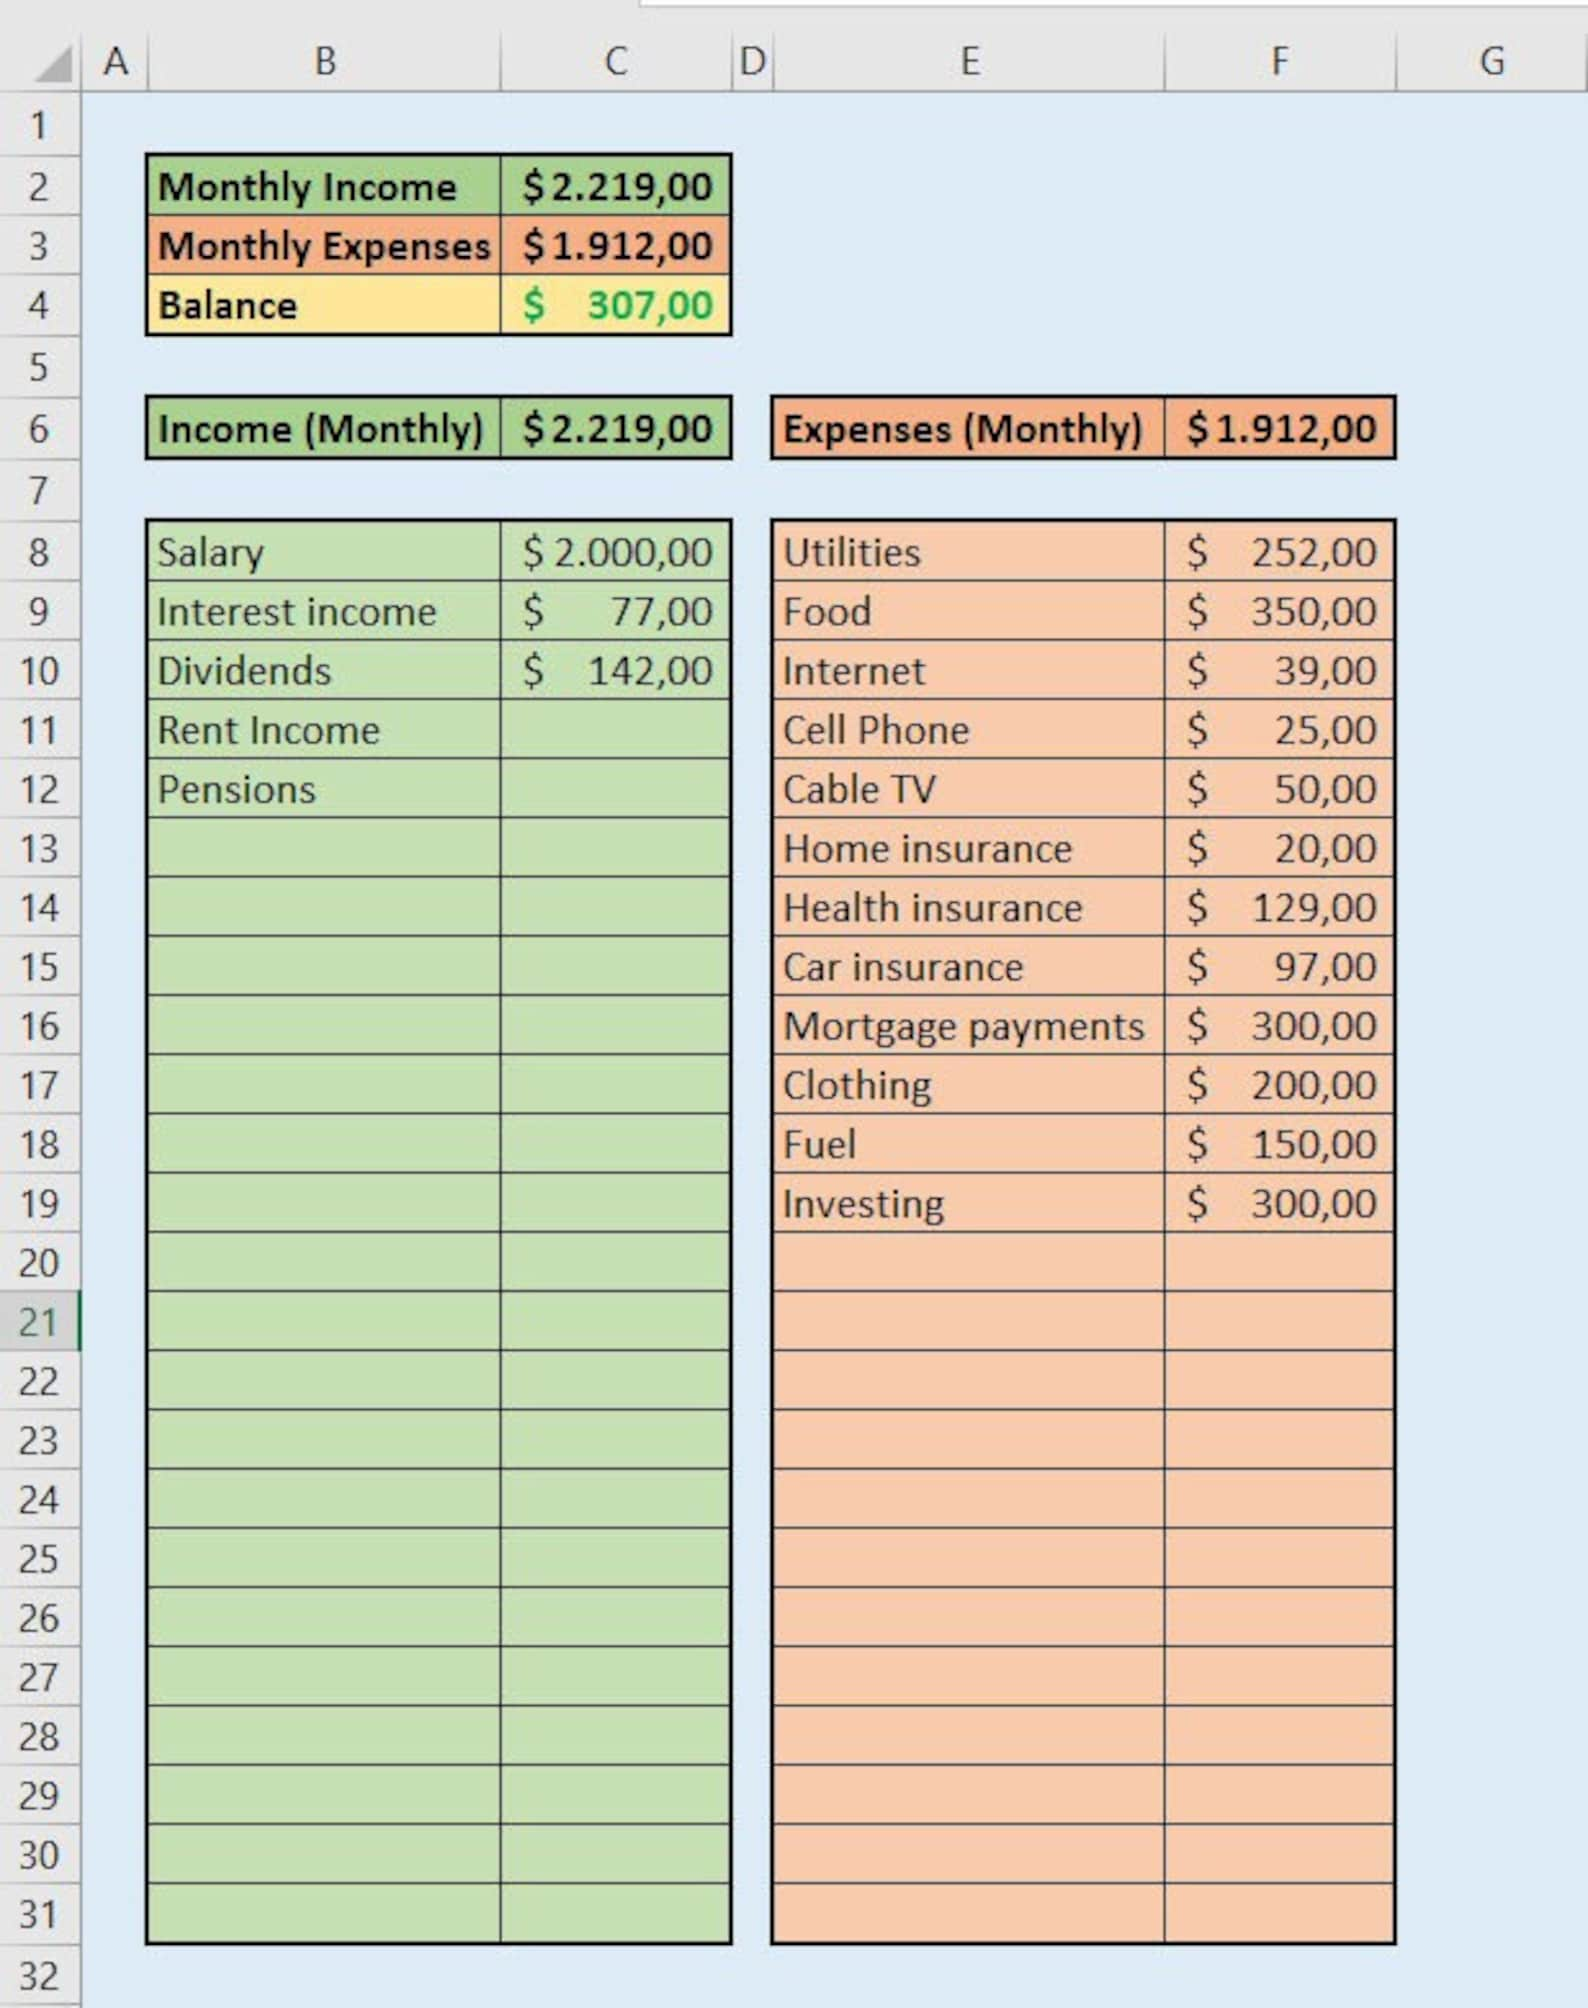
What People Get Wrong About This Worksheet
Most beginners treat the income section as a receipt of expected money. That is a mistake. Income on a budget should be recorded as what you have already received or what is contractually guaranteed. If a bonus has not landed, it does not exist yet. I learned this the hard way when I budgeted for a tax refund that was delayed by six weeks, overdrafted my checking account, and spent three months paying off the resulting fees. Another common error is rounding everything to neat numbers. Rounding hides patterns. When I tracked actual dollar amounts, I noticed I was spending roughly eighty dollars more per month on coffee shop purchases than I remembered. The rounding erased it. Keep the decimals if your tool lets you. Most budgeting spreadsheets do not force you to round, so there is no excuse. A third pitfall is ignoring small recurring charges. Streaming services, app subscriptions, membership fees. They add up quietly. I found seventeen of them when I did a full scan of my statements one October. Canceling five of them saved me about ninety dollars a month without changing my lifestyle.
My Edge Case Workaround
Last fall I hit a weird situation. My wife and I share one joint checking account but keep separate savings accounts. Our income deposits went into the joint account, and our bills were paid from there, but her medical expenses and my gym memberships were tracked differently in our heads. The single worksheet could not capture that split cleanly. I added a sub-account tag to each row. The tag was either J for joint, W for wife, or M for mine. At the end of the month I used a simple filter to sum by tag. This did not change how we lived, but it gave us clear visibility into who was responsible for what. Without that tag, I would have never known that medical expenses had climbed twelve percent from the previous quarter.
Download a Monthly Income And Expenses Worksheet
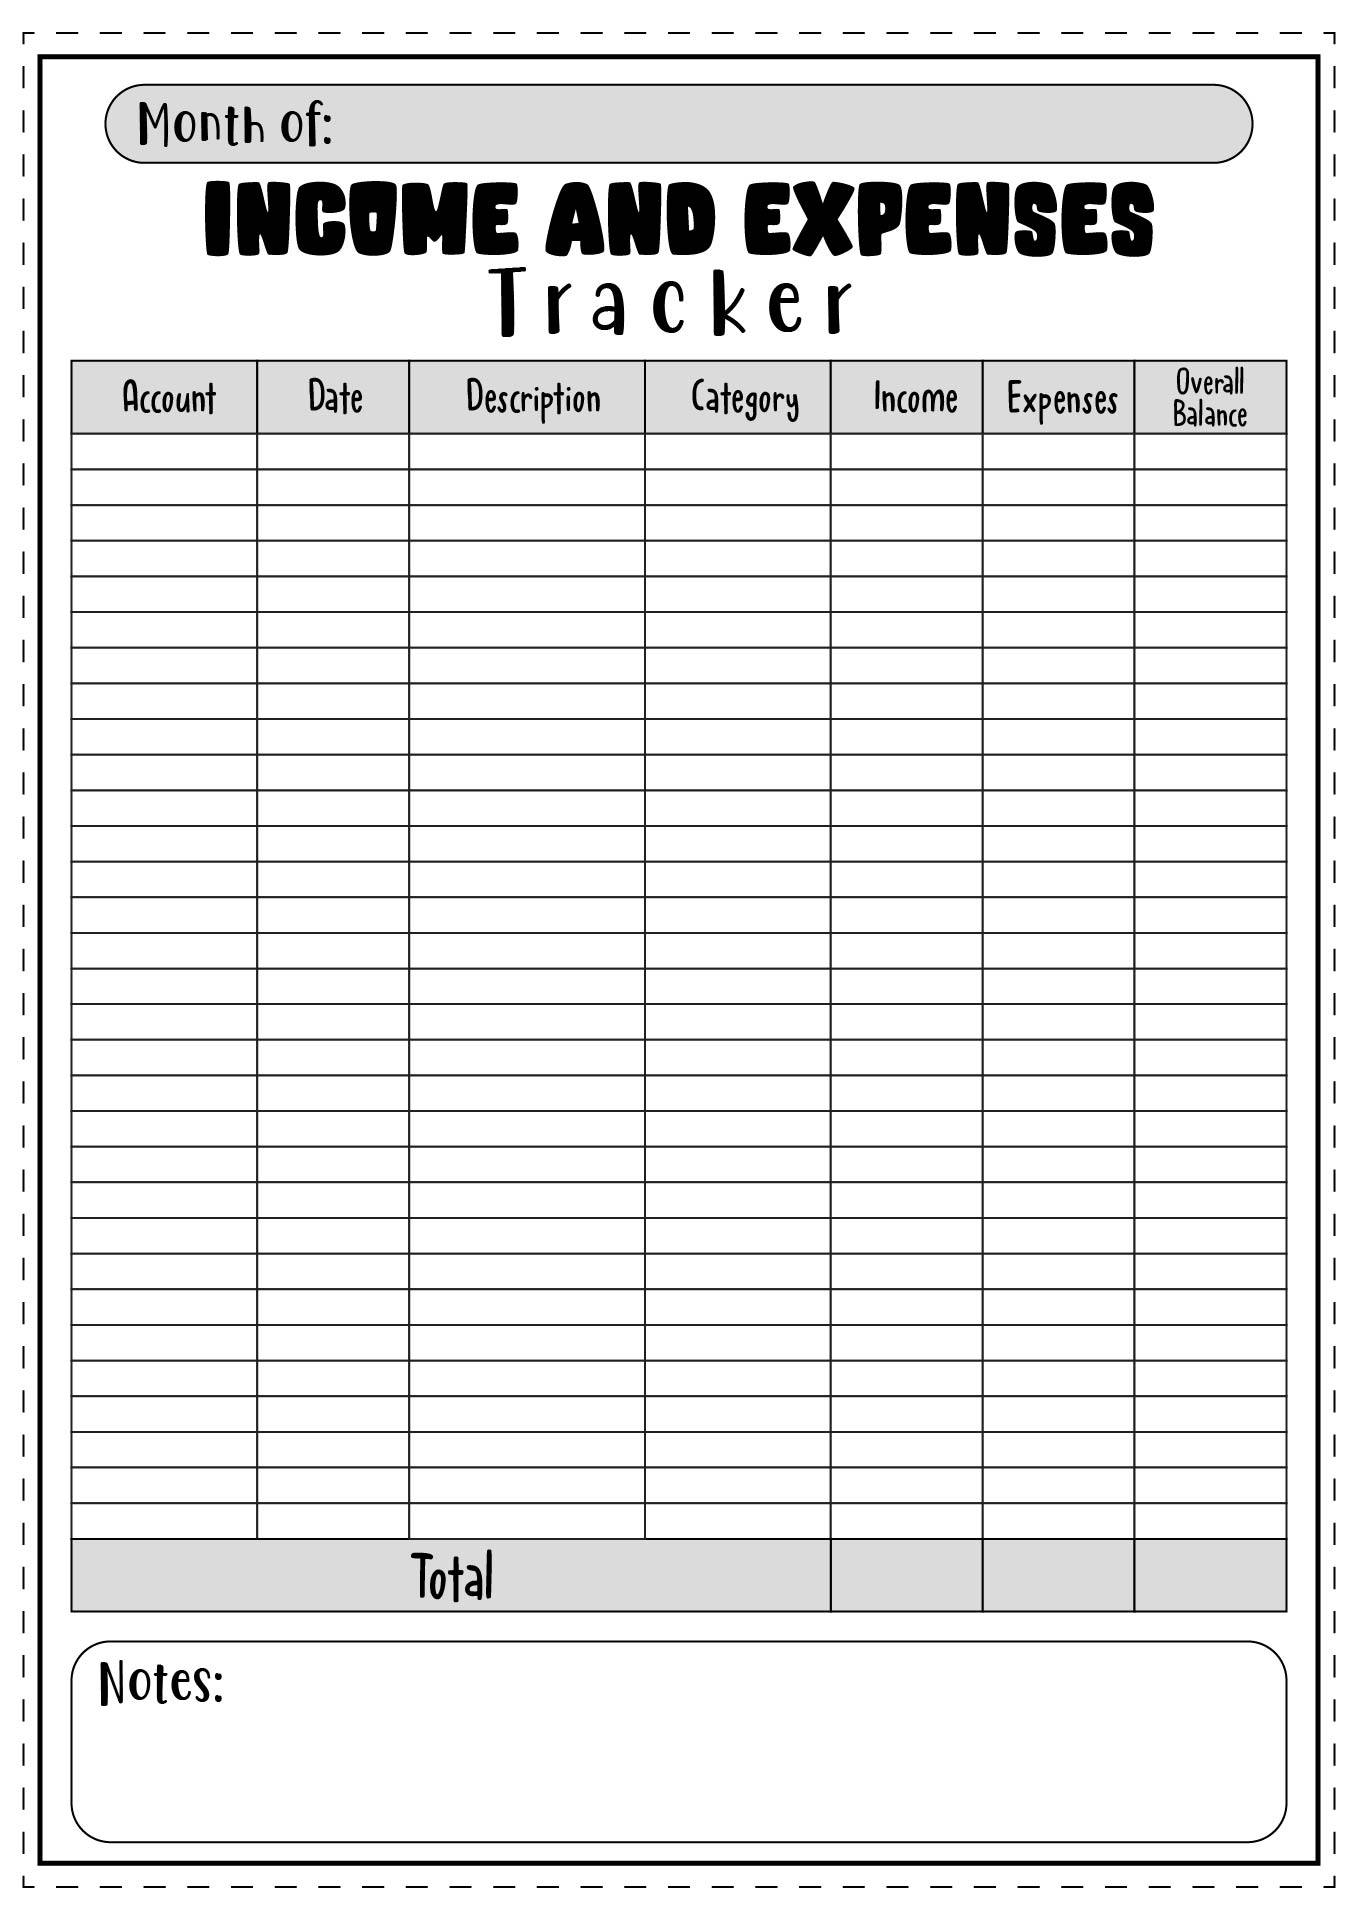
I keep a clean copy of my current template at this link: Monthly Income And Expenses Worksheet. It includes the income sheet, the expense sheet, the category list I use, and a notes section for anything that does not fit neatly into a cell. The formulas are locked so you cannot accidentally break the totals, but you can edit the category names if your expenses look different from mine. It breaks down when you have multiple income streams that vary wildly from month to month and you also carry high-interest debt. In that case, the static spreadsheet becomes a game of musical chairs where the music stops too often. I tried it for about four months after I consolidated debt and the variance between months made the plan feel pointless. The workaround was to switch to a zero-based system where every dollar gets assigned a job before the month starts. I stopped forecasting income and started working from confirmed deposits only. Any unexpected income went straight into a separate bucket labeled extra debt payment. This removed the guesswork and reduced my monthly planning time from about twenty minutes down to eight.
If your situation involves complex investments, freelance taxes, or joint accounts across multiple banks, a spreadsheet alone will not keep everything synchronized. You may need to supplement it with a simple reconciliation step once a week. Open each bank statement, match transactions to the worksheet, and mark any discrepancies. This weekly check prevents the end-of-month panic where you realize half your transactions were logged twice. The bottom line is that the worksheet works because it is boring. It does not gamify your spending. It does not send you push notifications. It just records what happened and lets you see the shape of your month. That shape is enough to make better decisions next time.