How a 5/1 ARM Actually Works in Practice
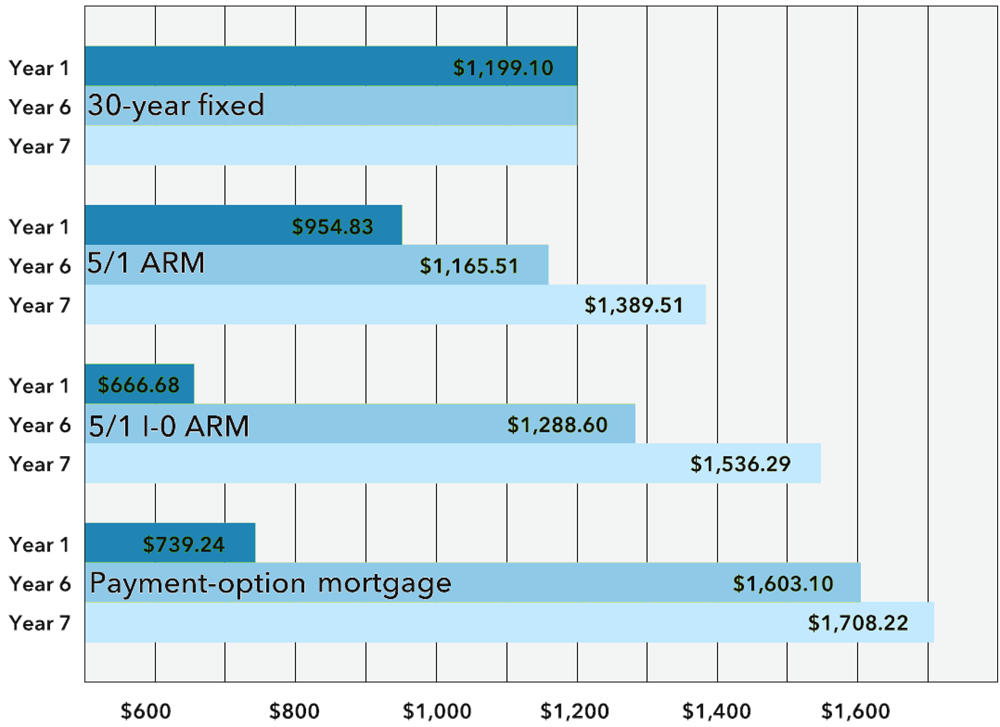
A 5/1 ARM is an adjustable-rate mortgage where your interest rate stays fixed for the first five years, then adjusts once a year afterward for the life of the loan. Most people I talk to are drawn to these because the initial rate is noticeably lower than what you get on a 30-year fixed. That front-end discount is real, usually running 0.5 to 0.75 percent below fixed rates, which translates to a few hundred bucks a month during the introductory period. It sounds generous until year six arrives. Pull up any decent calculator and plug in your loan amount, the current start rate, the margin the lender charges, the index it's tied to, and your caps. The most critical inputs most people skip are the adjustment caps and the index itself. A 5/1 ARM typically has a 2 percent periodic cap, meaning your rate can only move 2 percentage points up or down per adjustment after year five. There is also a lifetime cap, often 5 or 6 percent above the start rate, that acts as the hard ceiling no matter how wild the market gets. I ran into a specific problem last year when a client was comparing two lenders on a $420,000 loan at 6.25 percent start rate. One lender quoted a 2.375 percent margin and tied to the SOFR index with quarterly adjustments. The other quoted 2.125 percent margin but used a custom composite index that was slower to move. The calculator showed the second option was cheaper in every single scenario through year twelve, but the margin difference was only 0.25 percent, which looked tiny on paper. What the calculator didn't surface fast enough was that the slower-moving index meant the rate wouldn't drop even if the market dropped, so the 0.25 percent margin advantage eroded over time as rates fell. I had her model a scenario where SOFR dropped two full percentage points over eighteen months and recalculated both options under that assumption. The second lender actually ended up costing more because their index lag kept the rate artificially high while the first lender's rate adjusted downward normally.
This is the thing most people don't realize about these calculators: they show you the payment tomorrow. They do not show you whether the underlying index is fast or slow, whether your lender is adding a complication like a yield-spread premium that inflates the margin without warning, or whether the loan has negative amortization clauses buried in the fine print. I have seen loans where the rate adjusts monthly instead of annually and the calculator defaults to annual because the user did not check the settings. That alone can throw off the entire projection by thousands of dollars over the life of the loan. The biggest limitation I run into is that calculators assume the index will behave predictably, which it never does. If rates spike in year six, your payment could jump significantly and stay elevated for years. There is no reset button. If you are considering one of these, run at least three scenarios: rates flat, rates rising two points, and rates falling one point. If the rising scenario still keeps you comfortably within budget, you are in a reasonable position to proceed. Otherwise, a 30-year fixed or a 7/1 ARM gives you more runway with minimal cost difference in most current markets.