Building a mortgage calculator in Excel
Most people who try to build a mortgage calculator in Excel end up with something that looks right but breaks when they change the loan term or forget to handle leap years. I spent about three years doing this for clients before I stopped making the same mistakes. The problem isn't hard. It's the edge cases that eat you alive.The PMT function is your starting point. It takes the interest rate, the number of periods, and the present value, then spits out a monthly payment. Negative because Excel treats cash outflows as negative by default. Most people don't account for that and get confused when their result shows as a minus number. Just wrap it in ABS if you want it pretty. That's not the hard part though. The hard part is building the amortization schedule underneath it. I once had a client who was calculating a 30-year jumbo loan at 6.125% and noticed the final payment was $3.47 off from what the amortization table predicted. Traced it back to how Excel handles the PMT function internally. PMT rounds to the nearest cent at each calculation, but the actual bank applies interest to the unrounded balance. So after 360 months you end up with a small discrepancy. The workaround is to use the IPMT and PPMT functions for each individual period instead of just PMT, then manually set the final payment to equal whatever the remaining balance is. Takes about twelve extra lines but it's accurate. Here's something most tutorials skip. The rate parameter in PMT needs to be periodic, not annual. That means if you have a 7% annual rate and monthly payments, you divide by 12. But if your loan has biweekly payments, you divide by 26. I've seen people use the annual rate directly and wonder why their numbers are wildly off. Also, the nper parameter assumes payments are made at the end of each period unless you specify otherwise with the type argument. Most mortgages are end-of-period, so leave it as zero, but don't assume everyone knows that.
What your spreadsheet needs to handle
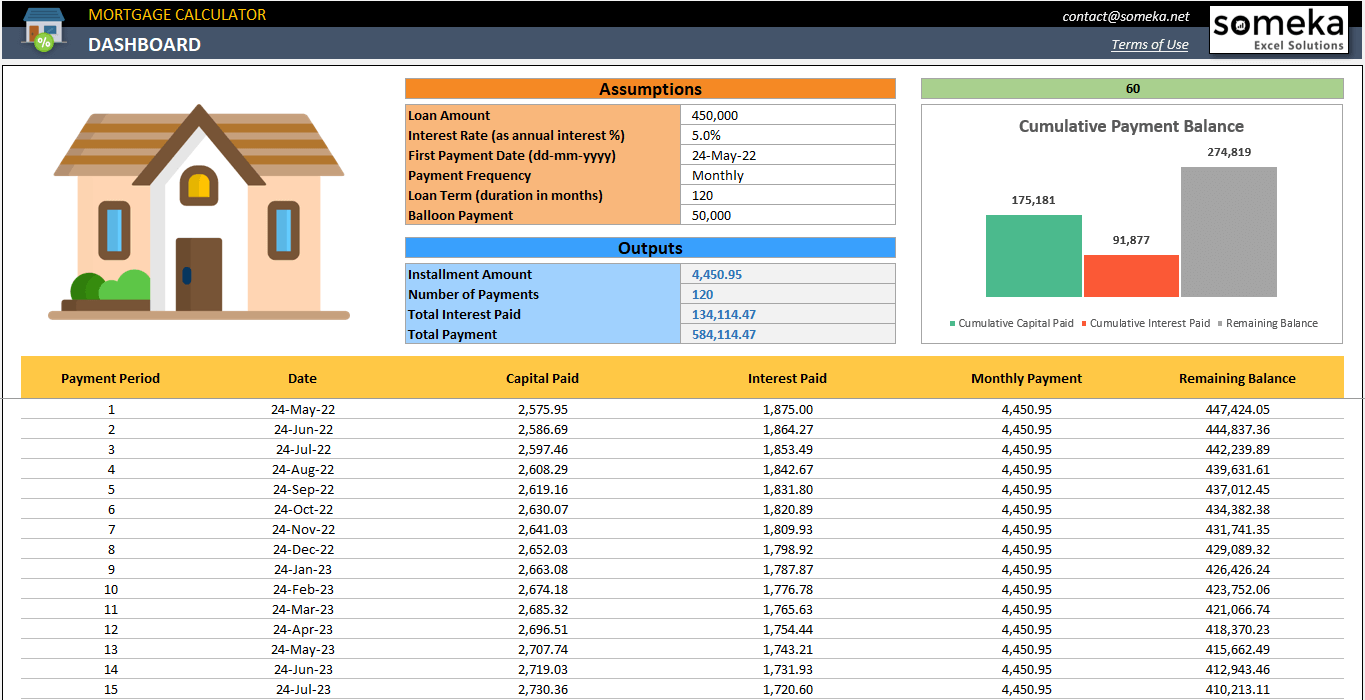
A basic calculator gives you the monthly payment. A usable one gives you the payment, the total interest paid over the life of the loan, the principal-to-interest ratio at different points, and a full amortization schedule. The schedule is where the real value sits. That's what people actually need when they're comparing loan terms or deciding whether to refinance.You should also factor in property taxes and insurance if the borrower wants a PITI payment, not just P&I. That means pulling in escrow amounts from somewhere or letting the user input them. Don't hardcode those values. Make them input cells so the calculator stays flexible. I usually put all the variable inputs at the top in a clearly separated block and reference them throughout with named ranges. Named ranges make the formulas readable. If you're looking at a cell that says =-PMT(B4/12,B5,B3) you have no idea what those letters mean five months later. If you name B4 as AnnualRate, B5 as NumberOfPayments, and B3 as LoanAmount, suddenly your sheet reads like actual documentation. Another thing people get wrong is how they handle extra payments. A lot of calculators let you add a lump sum but then fail to recalculate the remaining schedule properly. The fix is straightforward: whenever an extra payment occurs, the next period's beginning balance drops, which reduces the interest for that period and accelerates the payoff. But you need to decide whether the extra payment goes toward principal immediately or is applied at the end of the period. Different lenders handle this differently. Build in a toggle for that choice and label it clearly. I learned this the hard way when a client sent me back a spreadsheet three times because their lender applied prepayments at period end and their model assumed immediate application. For people who need ARM calculations or want to compare dozens of loan scenarios side by side, I usually recommend switching to a dedicated tool or at least building a scenario matrix with data tables. Excel's Data Table feature under What-If Analysis can vary two inputs simultaneously and generate a grid of results. I've used it to compare payment amounts across different interest rates and loan terms in one view. Much faster than manually changing cells and recording results.
There's also the issue of long-term accuracy. Excel's floating point arithmetic can introduce tiny errors in the final payment of a 360-period schedule. Usually it's a fraction of a cent but it adds up if you're building a calculator for a lending company that needs perfect reconciliation. In those cases you want to add a rounding step that forces the last payment to absorb any discrepancy. A simple IF statement checking whether the remaining balance is below a threshold and adjusting the final payment accordingly handles this.
Get the Full Details

Where to actually get a working spreadsheet
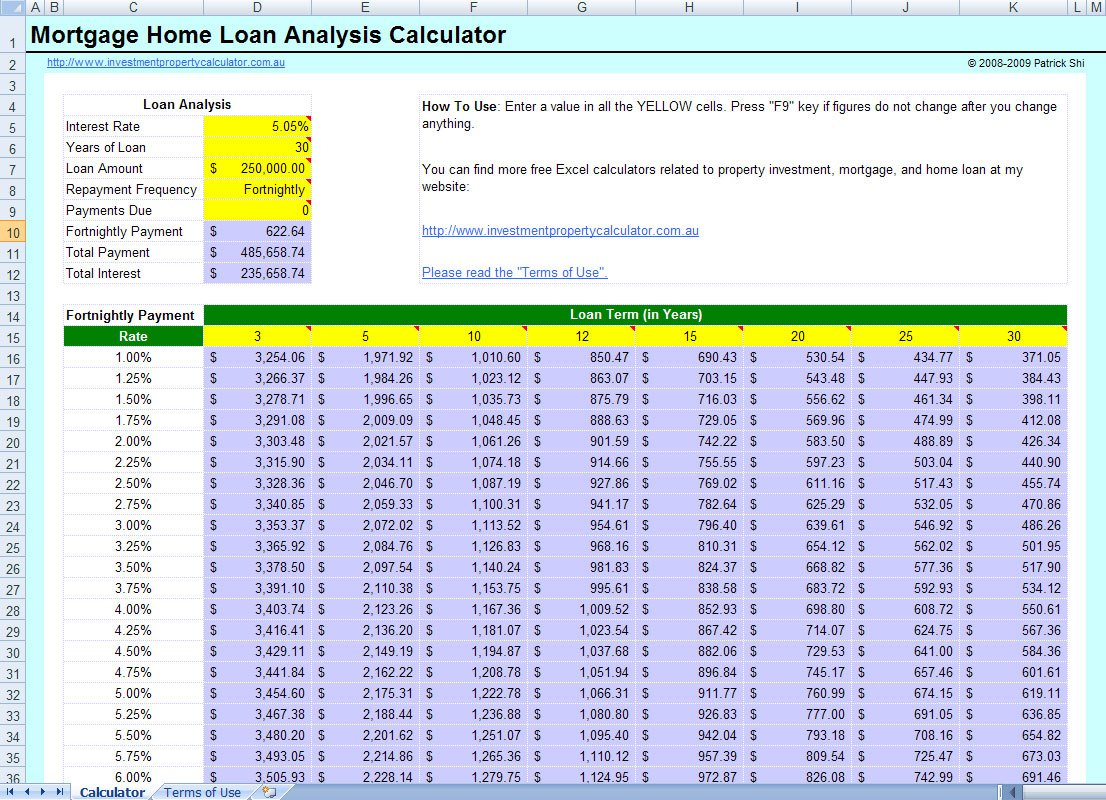
You can find free Mortgage Calculator Excel Spreadsheet templates everywhere online. Most of them are fine for casual use but they often skip the things that matter when you're doing serious analysis. The ones from university extensions or government housing sites tend to be more accurate because they're built by people who actually understand the math. The ones from real estate blogs are usually slapped together with broken formulas and outdated functions. I've opened a lot of those.If you want something solid and you're willing to spend a few hours building it yourself, I'd suggest starting with a blank sheet, setting up your input block, writing out the amortization schedule row by row, then adding the summary calculations on a separate tab. It'll take about forty-five minutes if you know what you're doing and maybe two hours if you're doing it for the first time. The payoff is a calculator that does exactly what you need it to do without hidden assumptions or broken edge cases. That's worth the time. One last thing. If you share this spreadsheet with other people, protect the formula cells. Lock them and password-protect the sheet. I've had versions of my own calculators get mangled because someone changed a cell reference or deleted a row and didn't realize it until three weeks later when the numbers no longer made sense. A two-minute protection step saves you from that headache.