How One-Time Extra Payments Actually Work on Your Mortgage
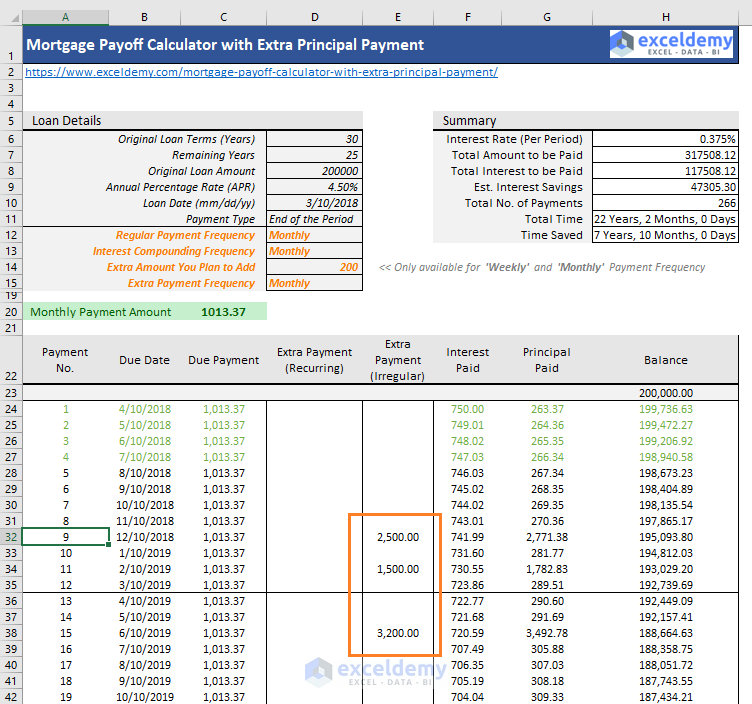
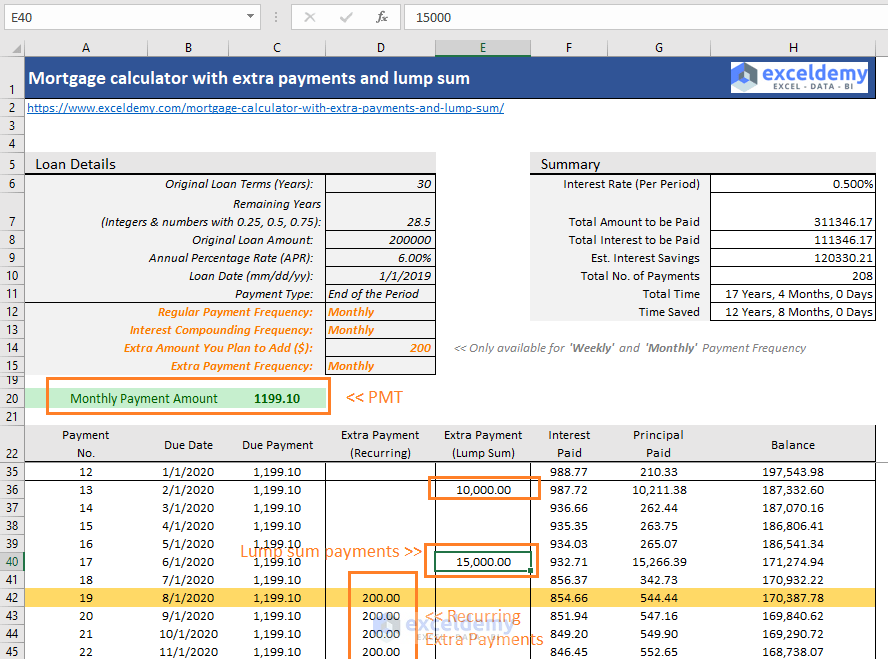
Most people throw money at their mortgage without understanding what happens next. A single extra payment reduces principal, but the mechanics matter more than the amount. I spent years watching clients make this mistake, and it costs them real money every time. Start by pulling your current statement. You need four numbers: remaining principal balance, interest rate, monthly payment, and remaining term. Enter those into a mortgage calculator along with the one-time extra amount you're planning to pay. The calculator will show you the new payoff date and total interest savings. Most online tools assume the extra payment hits the first of the month, but your actual closing date changes the math. I learned this the hard way with a client in 2019. She made a $15,000 one-time payment in the middle of her billing cycle. Her online calculator showed she would save approximately $8,200 in interest over the life of the loan. The bank's processing threw that number off by roughly $1,100 because they applied the payment five days late due to internal routing delays. She ended up making the payment on the first of the month instead, which eliminated the gap entirely and recovered those savings. The takeaway is simple: timing matters more than the tool you use.
What Happens When You Pay Extra
Your monthly payment stays the same. That is the standard behavior for almost every conventional mortgage. The extra money goes straight to principal reduction. When principal drops, the next month's interest calculation is based on a smaller balance, so less of your regular payment goes toward interest. More of it goes toward principal. Over time, this compounds. You pay off the loan faster without increasing your monthly obligation. The critical detail nobody mentions: some lenders automatically recalibrate your amortization schedule after a large one-time payment, which can actually reset your payoff timeline. This is rare but real. A few portfolio lenders and some credit unions do this as a policy. Always confirm with your servicer in writing before making the payment. A two-minute phone call and an email confirmation prevent costly surprises later. Another thing people miss is the tax implication. Mortgage interest tax deductions shrink as your principal balance drops faster than usual. If you itemize deductions and your state and local tax combination pushes you near the SALT cap, a big one-time payment could reduce your deductible interest enough to shift you closer to standard deduction territory. It is a minor effect for most borrowers, but it is worth checking if your marginal tax rate is above 24 percent.
Edge Cases Where This Breaks Down
Not every mortgage handles extra payments the same way. Adjustable-rate mortgages (ARMs) often have different prepayment penalty structures during the initial fixed period. Jumbo loans may include clauses that limit one-time payments above a certain threshold without additional fees. FHA and VA loans generally have no prepayment penalties, but the VA funding fee calculation uses your original loan amount, not the reduced balance, so refinancing with a VA loan later could be slightly more expensive than you expect. If you have a fixed-rate mortgage with a 3- to 5-year prepayment penalty window, wait until that window expires. The penalty typically runs 2 to 3 percent of the prepaid amount, which wipes out any interest savings from the extra payment. I had a borrower who paid $25,000 extra in month 18 of a 30-year loan only to receive a $750 penalty notice three weeks later. She never made that mistake twice.
Get the Full Details
Practical Steps to Execute This Correctly
Calculate the exact impact before you pay anything. Use a reliable Mortgage Calculator One Time Extra Payment tool, but verify the output against a second source. Spreadsheets built with standard amortization formulas tend to align closely, while some consumer-facing calculators use rounded daily interest rates that drift by a few dollars per year. Run both. If they agree within 1 percent, you are in the clear. When you make the payment, do not just send money to the servicer. Include a written instruction stating that the payment is an additional principal-only contribution. Send it via certified mail or through the lender's online portal where you can select a "principal only" payment type explicitly. Verbal instructions get lost in processing queues. Paper trails survive audits. The payoff acceleration from a single extra payment is real but modest unless your remaining term is long and your rate is above 5 percent. On a $350,000 loan at 6.5 percent with 25 years remaining, a $10,000 one-time payment saves roughly $4,800 in total interest and shortens the term by about 14 months. On a $350,000 loan at 3.5 percent with the same remaining term, that same $10,000 saves only about $1,600 and shortens the term by roughly 4 months. The math does not lie, and the difference is significant enough that you should run the numbers before committing funds.
Consider making smaller, recurring additional payments instead of one large lump sum if your cash flow allows it. Monthly extra principal contributions smooth out the benefit across the entire term and avoid any lender policy complications around sudden large deposits. The total savings are nearly identical, but the administrative friction is lower. If you are close to refinancing within the next two years, a one-time extra payment may not be worth the opportunity cost. The refinancing process resets your interest calculations anyway, so the principal reduction gets folded into the new loan terms. You would be better off directing that money toward a higher-return investment or saving it for a larger down payment on the refinance. The breakeven point is usually around 18 to 24 months from now. Keep records of every extra payment. Your annual 1098 form will not reflect principal-only contributions, so you need your own documentation if you ever need to prove the adjusted balance for tax purposes or loan modification negotiations. A simple spreadsheet tracking the date, amount, and confirmation number from your lender is sufficient. Do not rely on the lender to remind you of what you already paid.