Comparing Mortgage Loans Without Losing Your Mind
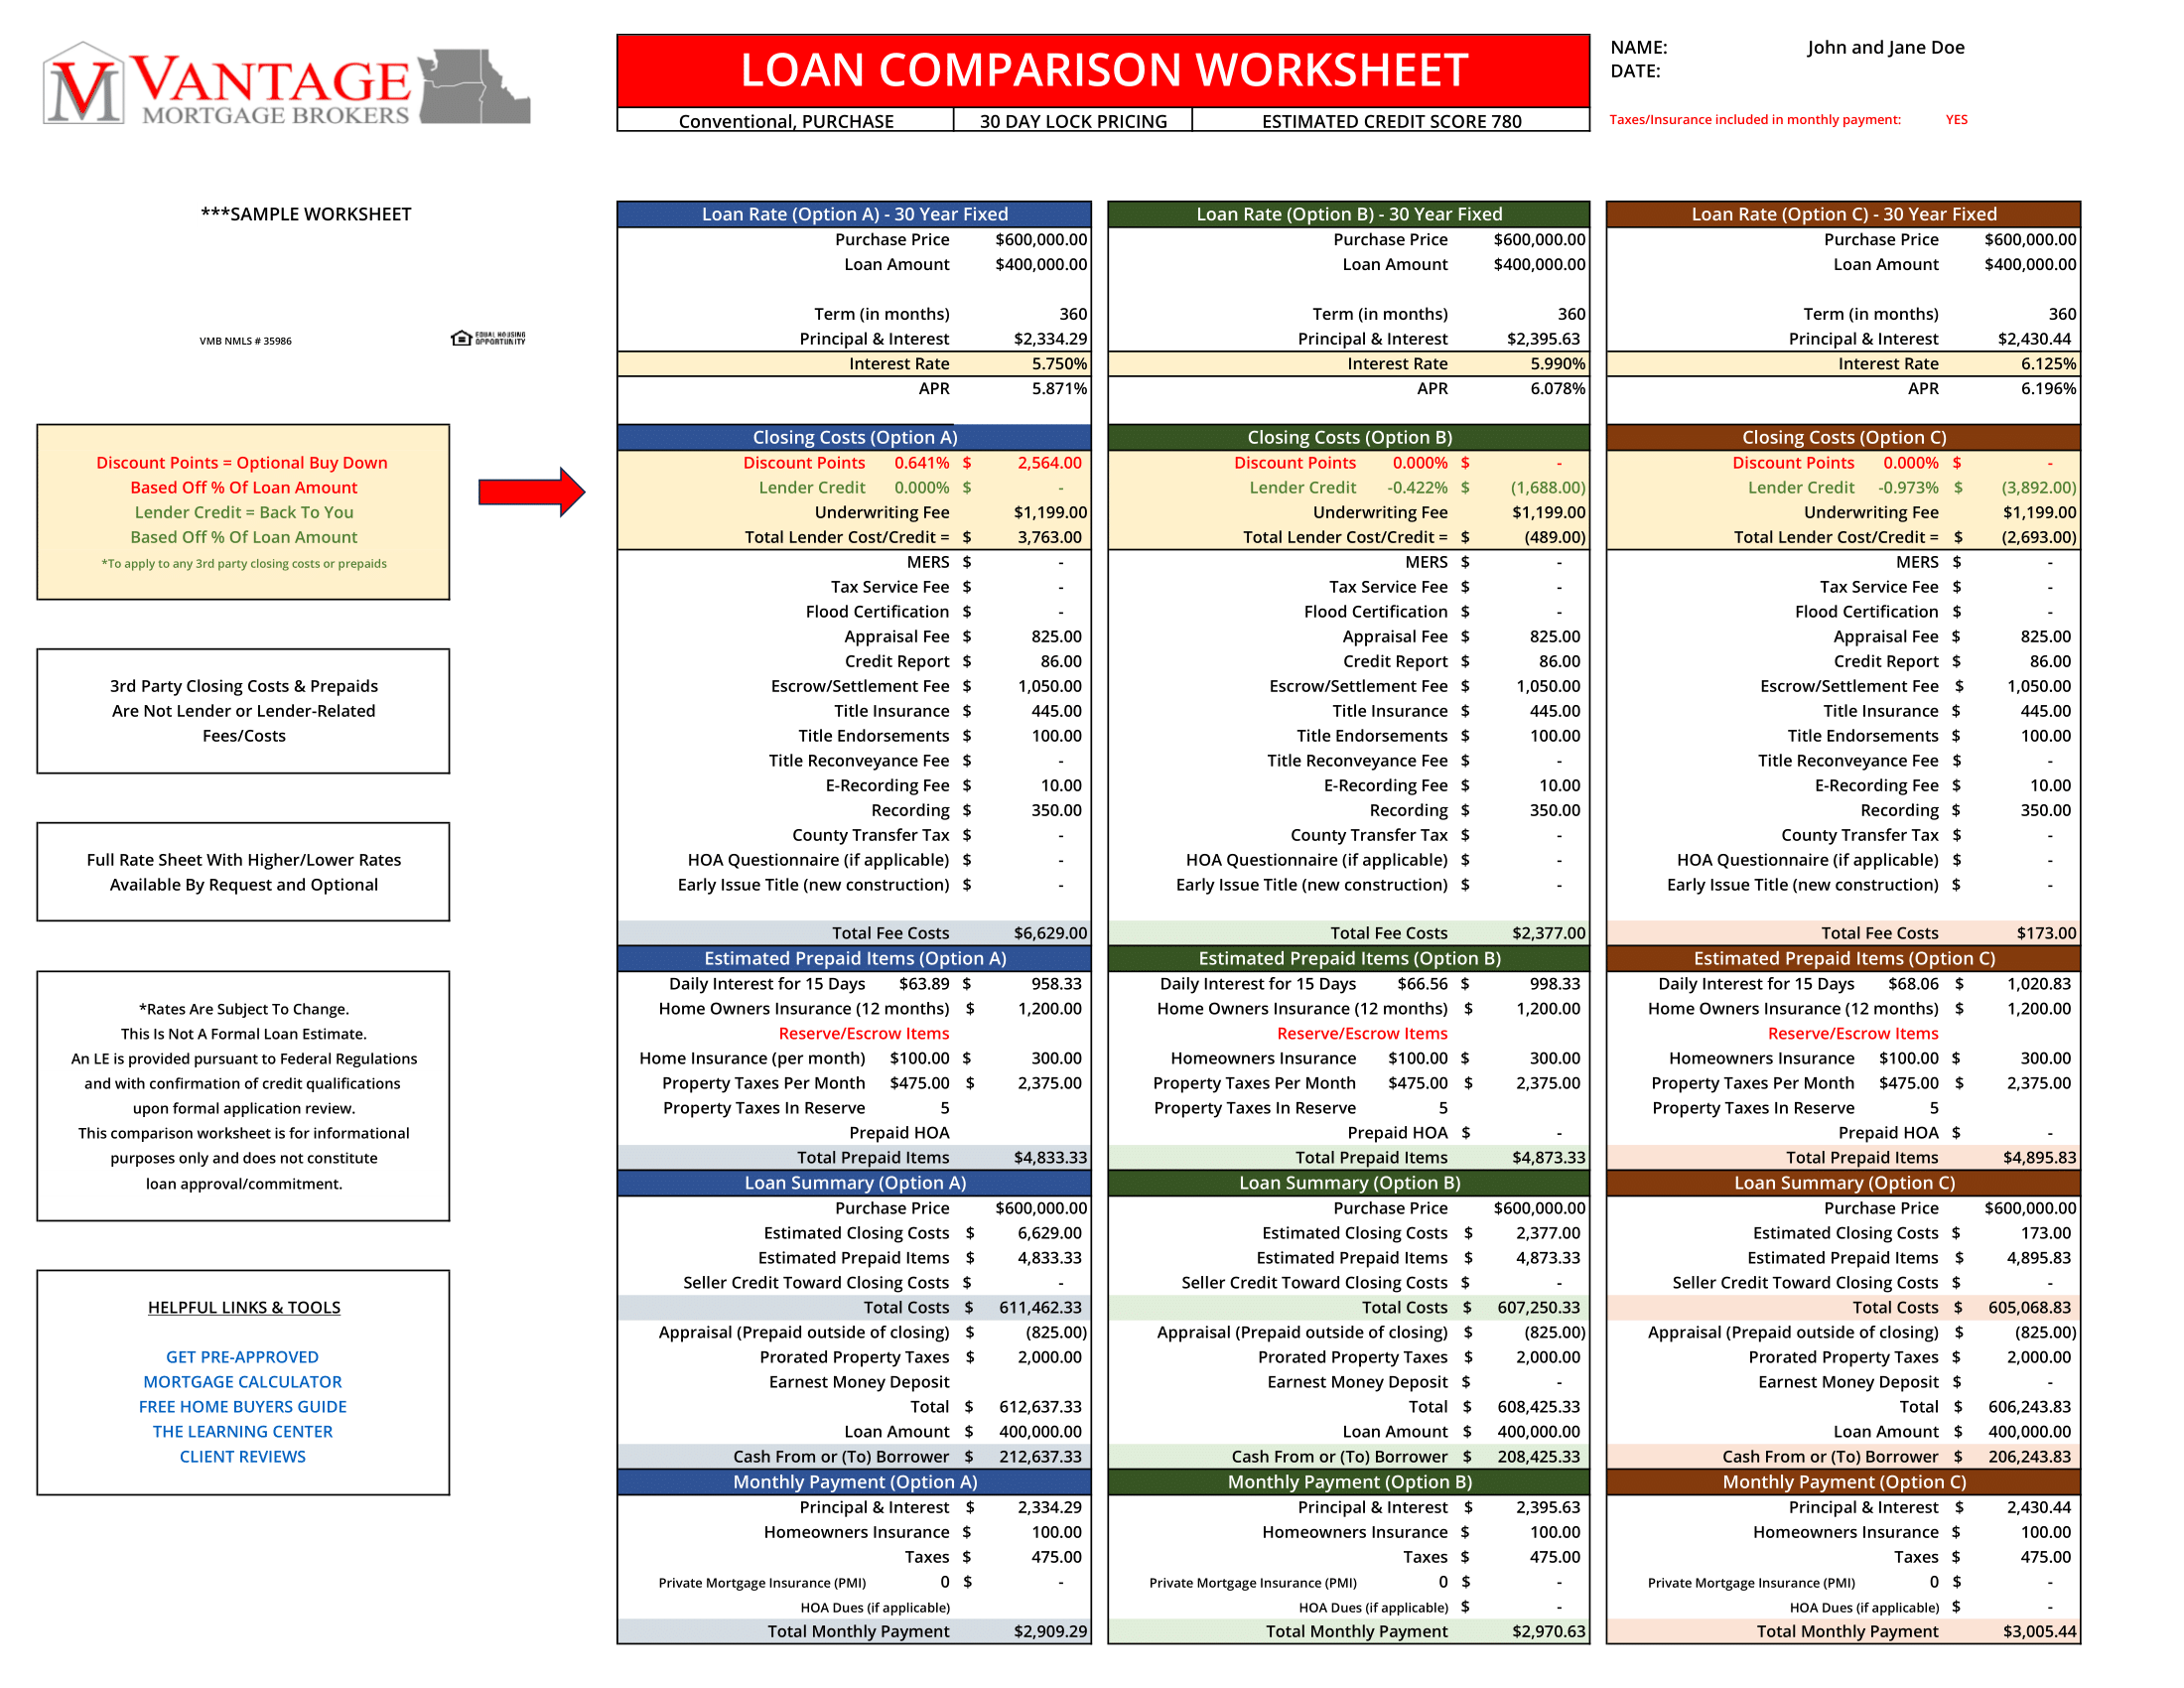
Most people dump every loan estimate they have into a spreadsheet and call it a day. It works, until you realize you forgot to include the closing costs on one loan and the discount points on another, and now your comparison is skewed by thousands of dollars. I learned that the hard way about three years ago when I was helping a client sort through five different conforming loan offers for a refinance. Two of the loans had lender credits that offset closing costs, one had an aggressive rate buydown, and the other two were plain vanilla 30-year fixed. The "cheapest" loan on paper turned out to be the most expensive once I pulled the full Good Faith Estimate and added up the actual out-of-pocket costs at closing. The core of a solid Mortgage Loan Compare setup is building a worksheet that tracks comparable metrics across every offer you receive. You need the interest rate, the loan type, the term, the monthly principal and interest, the total closing costs, any discount points paid, any lender credits, the APR, and the break-even timeline if you're buying down the rate. Those eight or nine data points will tell you more than any sales pitch the loan officer gives you. Everything else is mostly noise.
Mortgage Loan Compare Spreadsheet Setup
Set up columns for each loan offer. Row by row, fill in the data points I mentioned above. Add a column for the monthly PITI payment by including estimated taxes, insurance, and HOA if applicable. Then add a calculated field for total cash to close, which is the loan amount plus closing costs minus any lender credits. Finally, calculate the effective rate or the break-even point for any rate buydown by dividing the cost of the points by the monthly savings they generate. This takes maybe twenty minutes to set up properly, and it saves you from making decisions based on incomplete information. One thing most people miss is the difference between the note rate and the APR. The APR includes certain fees and gives you a broader picture, but it is not a perfect measure either. Some lenders stuff closing costs into the loan structure in ways that inflate the APR without necessarily making the loan more expensive overall. I had a case where a loan with a slightly higher note rate actually had a lower true cost because the lender offered generous credits that reduced cash to close by over four thousand dollars. The borrower would have picked the lower APR loan if they had only looked at that number. Another overlooked detail is how prepayment penalties are structured. Not every loan has one, but the ones that do can vary significantly. Some penalize you for refinancing within three years, others for selling the home within five, and a few have a declining penalty schedule that drops year by year. If you plan to move or refinance again within a few years, a prepayment penalty can erase any savings you thought you were locking in. Factor it into your comparison matrix or discard those loan offers entirely if the penalty terms are restrictive enough to matter.
Where the Comparison Breaks Down
This method works well for standard conforming loans on primary residences. It starts to fall apart when you deal with jumbo loans, construction-to-permanent loans, or foreign income self-employed borrowers. Jumbo loans often have variable pricing structures where the rate and fees don't follow the same patterns as conforming products. Construction loans require you to compare draw schedules and interest-only periods, which adds layers of complexity a simple spreadsheet doesn't handle cleanly. And when borrower income is unconventional, the qualifying ratios change enough that the monthly payment on paper might not reflect what the lender actually underwrites. If you are in one of those edge cases, the spreadsheet approach still gives you a starting point, but you should supplement it with a direct talk to a second loan officer from a different lender. Sometimes the pricing algorithms differ enough between banks and credit unions that the cheaper option on paper becomes the more expensive one after underwriting adjustments are applied. I once saw a credit union quote look worse than a bank quote by fifty basis points. After underwriting, the credit union loan came out cheaper because the bank added fee overlays that the credit union did not have. Also worth noting: this comparison tool is only as good as the data you put into it. Loan estimates can change. Rates float. Fee structures get adjusted before final disclosure. If you are comparing offers that are more than ten days old, recalculate everything before making a decision. A rate lock expiring mid-comparison is a common way people accidentally commit to a worse loan because they stopped updating their spreadsheet halfway through the process.
Get the Full Details
The practical output of all this is a single line at the bottom of your sheet that shows total cost over your expected holding period. If you plan to stay seven years, run the numbers for seven years including refinancing costs if relevant. If you plan to sell in three, stop there. The right loan depends entirely on how long you actually keep it, and nobody factors that in early enough.