Why You'd Want to Model Early Payments Before Actually Making Them
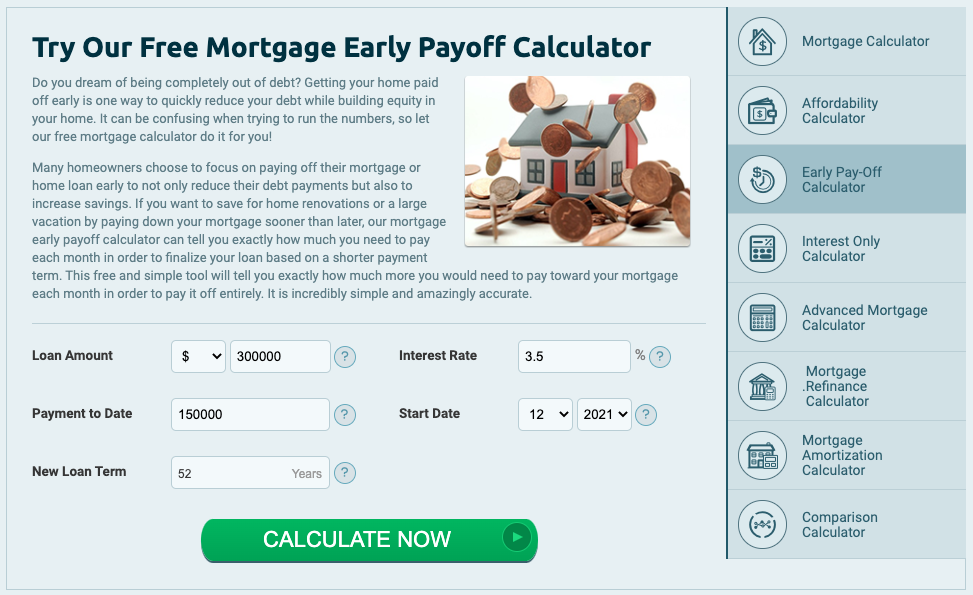
Mortgage payments are structured so that the early years are almost entirely interest. If you throw extra money at the loan, it can change the trajectory significantly, but not in the way most people assume. A Mortgage Loan Early Payment Calculator helps you see exactly what happens when you pay ahead of schedule, rather than guessing. The basic mechanics are straightforward. You input your remaining principal, your interest rate, your current monthly payment, and the extra amount you plan to pay. The calculator then replays the amortization schedule with those additional funds applied. What changes depends on whether the payment is applied to principal reduction or to shortening the term. Most lenders default to keeping the payment the same and reducing the number of months, which is usually the better move mathematically. I learned this the hard way a few years back when I was helping a client who had just refinanced into a 30-year fixed at 6.2 percent. She wanted to pay an extra $400 a month and expected to slash roughly eight years off the loan. The calculator showed a different number entirely. The model predicted about five and a half years saved. The discrepancy came from the fact that her original loan had already gone seven years into its term, meaning the principal balance was lower than she remembered and the interest component of each payment had shifted. Once we pulled the actual payoff statement from her servicer and entered the real remaining balance instead of the original loan amount, the calculator's output matched reality. Input error is the single biggest reason these tools give misleading results.
Using a Mortgage Loan Early Payment Calculator Correctly
Start by gathering the numbers your lender has on file. The original loan amount, the current interest rate, the current monthly principal and interest payment, and most importantly the current outstanding principal balance. The last one is the number most people get wrong. They plug in the original $350,000 when the actual balance might be $312,000 after two years of payments. That error skews every result downstream. Next, decide how you want the extra payment structured. One-time lump sums behave differently from recurring monthly overpayments. A lump sum applied mid-cycle will mostly reduce the next month's interest charge because the principal balance drops before the next payment date. A recurring $200 added to every monthly payment compounds across the entire schedule. The calculator should let you model both. If it doesn't, find another tool. Pay attention to whether the calculator accounts for escrow. Most basic versions ignore taxes and insurance and only model the principal and interest portion. That's fine for comparing scenarios, but it means your total monthly outlay isn't fully represented. Factor that in separately if you're budgeting around the extra payment.
Here's something most calculators don't warn you about: some loans have prepayment penalties. A significant number of conventional loans don't, but government-backed refinances and certain adjustable-rate products, particularly those taken out within the first three years of a refinance, sometimes carry a yield-maintenance clause or a six-to-twelve-month interest penalty. Running the numbers on a calculator won't tell you this. You have to read the original promissory note or call the servicer. I once had a borrower who calculated she'd save $47,000 in interest by paying off her loan early, only to discover a $12,000 prepayment penalty that wiped out nearly a quarter of the projected savings. She ended up paying in monthly installments over eighteen months instead of clearing it in one shot, which minimized the penalty while still reducing the balance faster than the original schedule. Another counter-intuitive point that trips people up involves the interaction between extra payments and loan recasting. Some lenders allow you to make a large lump-sum payment and then officially recast the loan, which recalculates the monthly payment based on the new lower balance while keeping the original term. This can free up cash flow significantly. A standard early payment calculator won't model recasting because it's a lender-specific option. If your loan qualifies, the real savings might come from lowering the monthly obligation rather than just shrinking the term. Run both scenarios through the calculator to compare. The biggest limitation of these calculators is that they assume a fixed-rate loan with predictable payments. If you have an ARM, an interest-only period, or a hybrid loan, the output becomes unreliable once the rate adjusts. The calculator can show you what happens under current conditions, but it can't model a future rate reset. For ARM holders, the useful timeframe for these calculations is usually capped at the end of the initial fixed period.
Get the Full Details

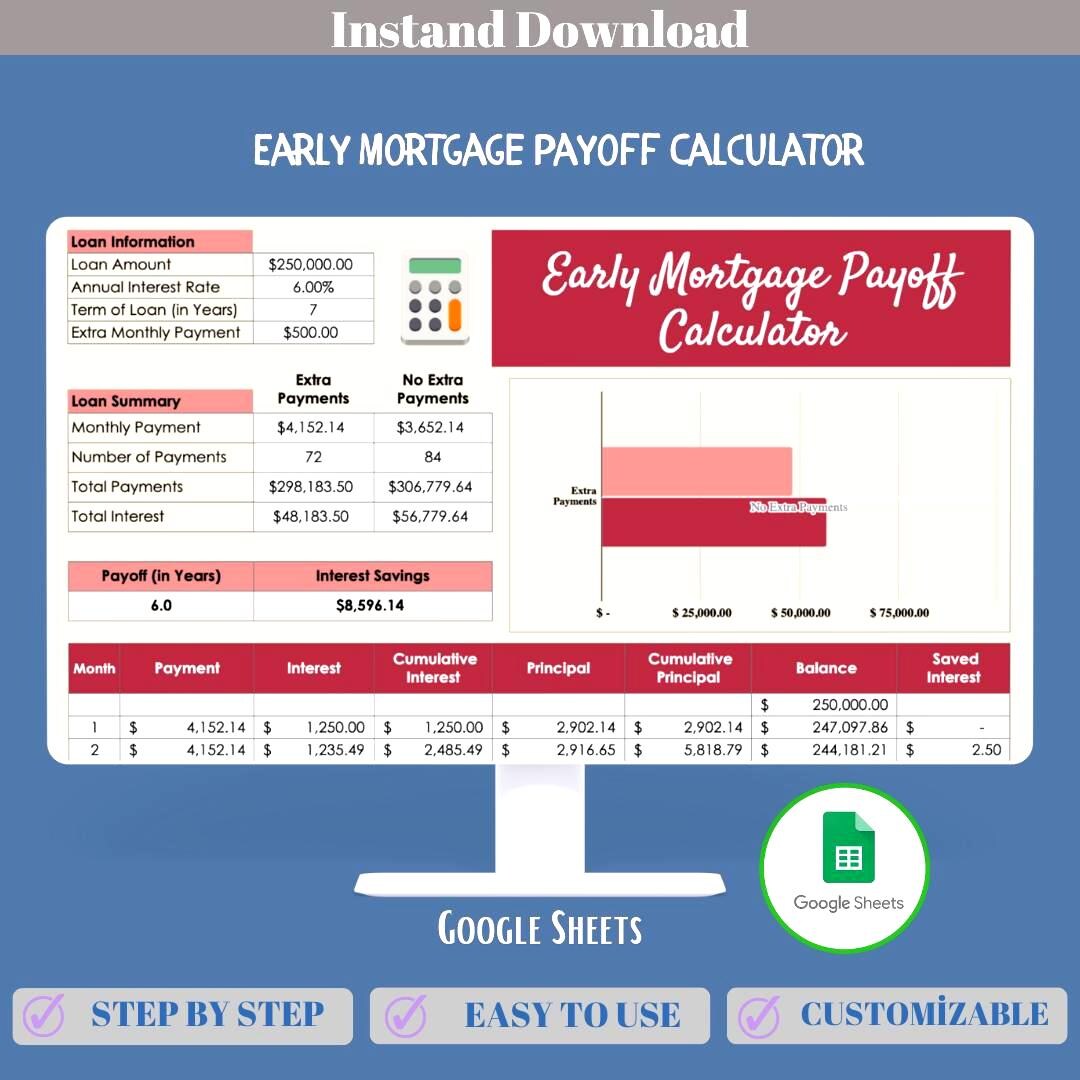
There's also the tax angle. Mortgage interest deductions on Schedule A are still available for qualified residence loans, though the SALT cap and other TCJA changes have narrowed who benefits. Paying off your mortgage faster reduces the interest you can deduct each year. If you're in a high bracket and itemize, the after-tax cost of your mortgage is lower than the nominal rate suggests. A fully comprehensive calculator would factor in your marginal tax rate and show the net cost, but most free online tools don't. Do the adjustment yourself if the deduction is material to your situation. The best use of a Mortgage Loan Early Payment Calculator is to compare specific strategies against each other rather than to treat any single output as gospel. Run the scenario where you pay an extra $300 monthly. Run the scenario where you make one lump sum payment equal to that same total annual amount. Run the scenario where you Bi-weekly payments instead. The differences between them are usually smaller than people expect, and seeing those deltas in front of you prevents you from picking the strategy that sounds best without knowing the actual math. One practical workflow I recommend: set up your baseline scenario with current loan details and note the total interest paid over the full term. Then layer in each extra payment strategy one at a time, recording the interest savings and the new payoff date for each. The gap between scenarios tells you whether the administrative hassle of setting up automatic extra payments is worth the marginal gain, especially when you're dealing with smaller dollar amounts where the difference might be a few hundred dollars in interest over several years.
Keep in mind that these calculators also don't account for opportunity cost. If you can earn six percent in a taxable investment account, paying down a mortgage at five point five percent might not be the optimal use of that cash, depending on your risk tolerance and tax situation. The calculator shows you the mortgage side of the equation in isolation. The decision about whether to prepay or invest requires the other side of the comparison, which is yours to calculate separately.