How to Build and Use a 7/1 ARM Mortgage Payment Calculator
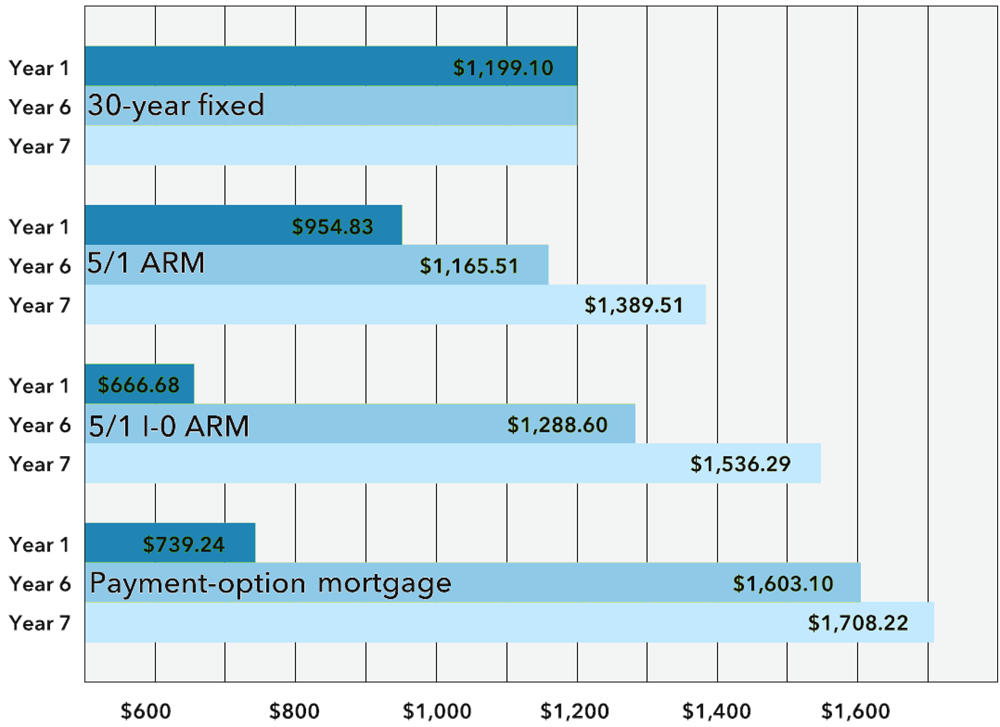
A 7/1 ARM is an adjustable-rate mortgage where the interest rate stays fixed for the first seven years, then resets once a year for the remainder of the loan term. Most people encounter these when the initial rate is significantly below what a 30-year fixed offers. The payment doesn't jump all at once — it shifts every year after year seven based on an index, a margin, and a set of caps. That structure means you need a calculator that can handle recurring recalculation, not just one static payment estimate.Mortgage Payment Calculator 7 1 Arm
A basic online calculator will give you the initial monthly payment. That is useful if you only care about months one through eighty-four. But the real question is what the payment looks like after each annual adjustment, and most free tools don't show that. You need a spreadsheet or a tool that rebuilds the amortization schedule every time the rate changes. The fixed-rate portion of a 7/1 ARM uses the standard amortization formula. Input your loan amount, the starting interest rate, and the total number of payments. For a $350,000 loan at 5.75% over 360 months, the monthly payment is approximately $2,046. This is straightforward. Where it gets complicated is after the rate adjusts. At the first adjustment, the new rate is determined by adding the margin to the current index value. Say the index is the 1-Year CMT, the margin is 2.25%, and the index reads 4.50%. The fully indexed rate would be 6.75%. But the rate cannot exceed the periodic cap. Most 7/1 ARMs have a 2% periodic cap and a 5% lifetime cap. If the previous rate was 5.75% and the new fully indexed rate would be 8.25%, the 2% periodic cap kicks in and the rate is limited to 7.75%. The payment is then recalculated from scratch using the remaining balance and the remaining number of payments.
This recalculation is the part most people miss. The payment does not simply increase by the same percentage as the rate. The new payment is computed on the remaining balance over the remaining term. As the balance drops each year, the same rate increase produces a smaller dollar increase in the monthly payment over time, even though the rate may be climbing.
Building the spreadsheet
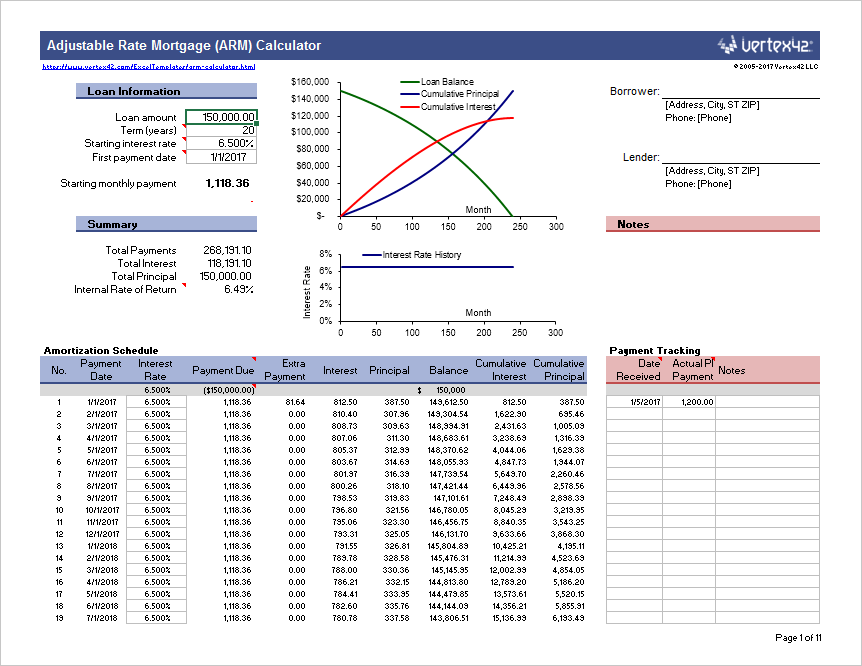
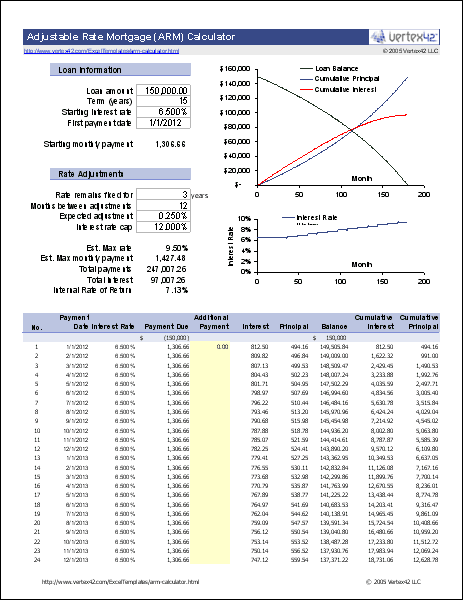
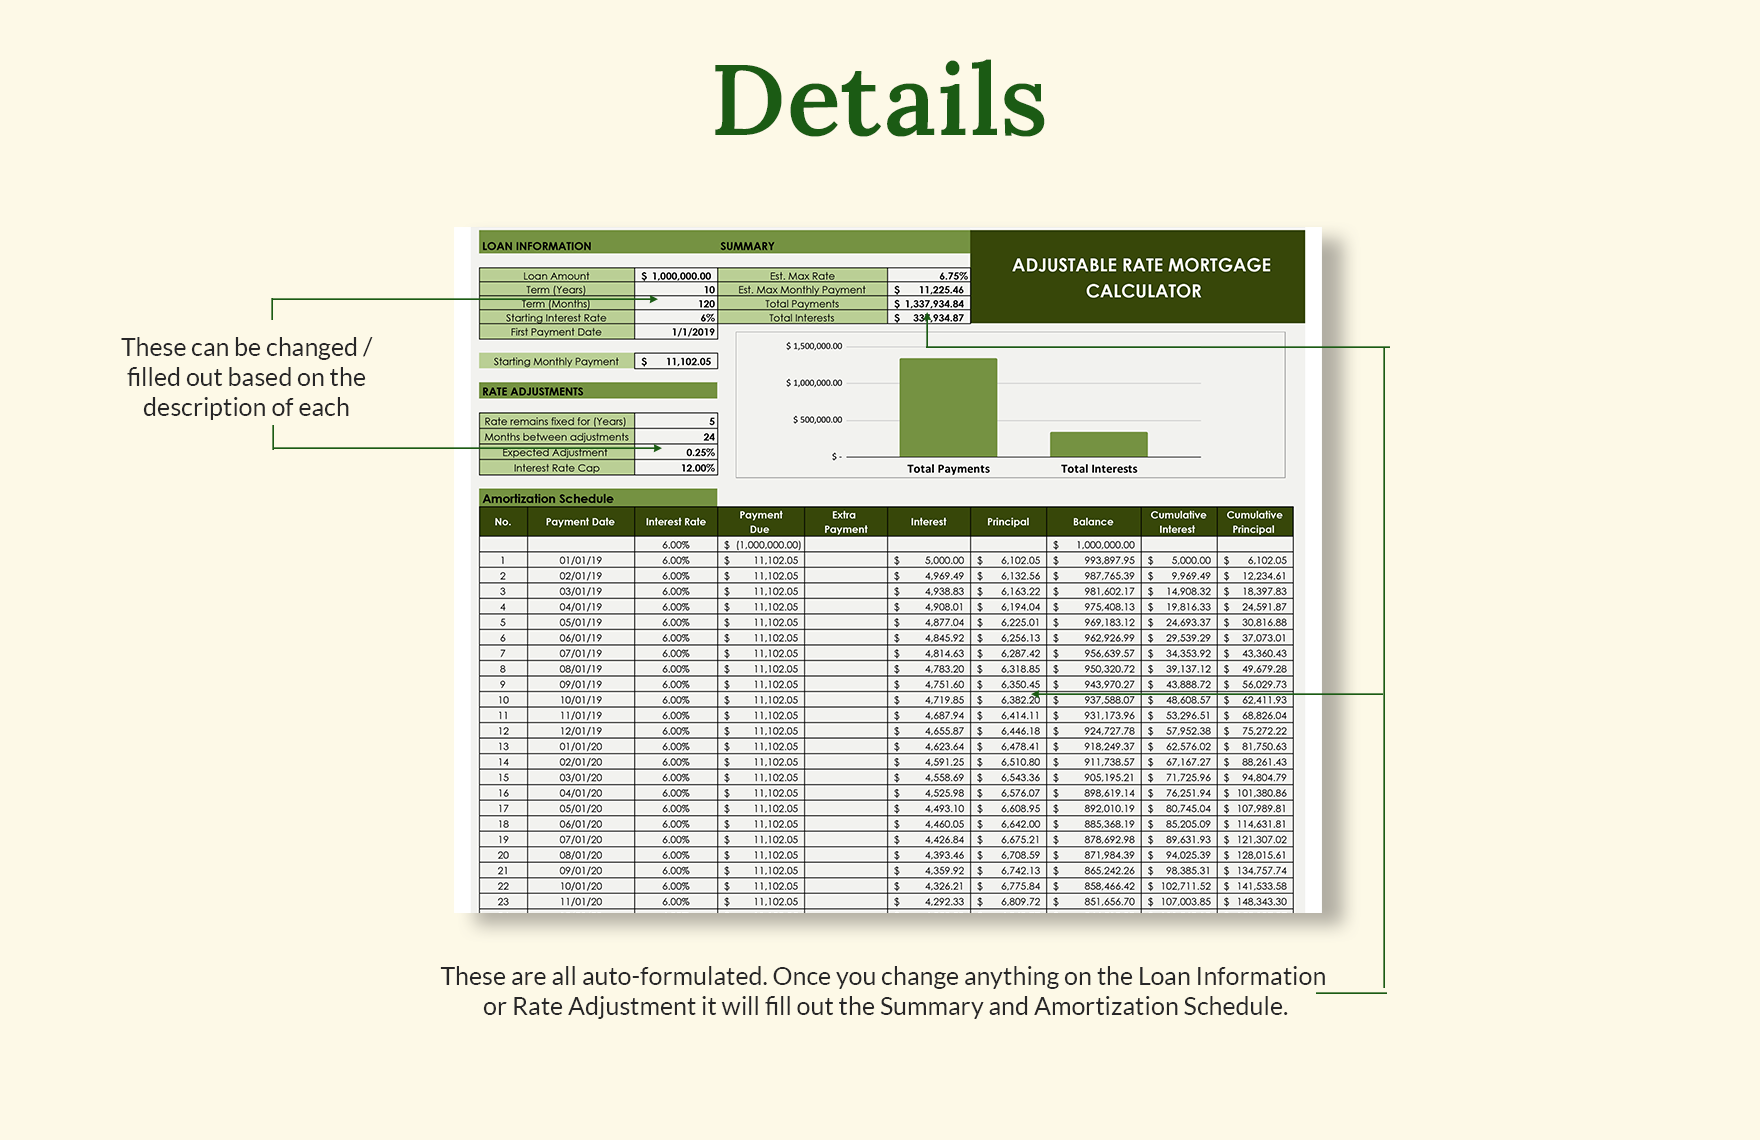
Set up columns for month number, starting balance, current rate, monthly payment, interest portion, principal portion, and ending balance. For the first 84 months, use the initial rate. After that, enter a formula that pulls the index value, adds the margin, applies the periodic and lifetime caps, and then recalculates the payment using the PMT function in Excel. The PMT formula for the new payment is: =PMT(adjusted_rate/12, remaining_payments, -current_balance) The tricky part is tracking remaining payments correctly. It is simply the original total number of payments minus the current month number. Every time the rate changes, you recalculate using that formula with the updated balance and updated remaining term.
Get the Full Details

A real problem I ran into
I was building a calculator for a client who had a 7/1 ARM from a regional lender. The servicer's amortization schedule didn't match anything the client's loan officer or any online calculator produced. The discrepancy was exactly $34 per month. After walking through the documents line by line, I found that the lender used a 360-day year for interest accrual but a 30-day month for payment calculation, while also applying a day-count convention that rounded the accrued interest to the nearest cent at each adjustment. Standard calculators assume a simple daily interest model without that rounding step. The workaround was to build a month-by-month interest accrual that used the lender's actual day count between the last payment date and the current payment date, applied the 360/30 convention, and then rounded before subtracting from principal. That $34 difference compounded to over $2,000 over the first adjustment period alone. One issue is assuming the rate adjustment date is exactly one year from closing. Some ARMs use an anniversary date that is offset by the loan's payment cycle. If your close date is the 15th and your payment is due on the 1st, the first adjustment could fall on the 1st of the month, not the 15th. Check the promissory note. The adjustment date governs when the new rate takes effect and when the new payment is due. Another pitfall is ignoring the index lag. Most indices, including the CMT and SOFR, are published with a one-business-day lag. The rate adjustment is typically based on the index value from a specific lookback period defined in the note. If you are using a calculator that pulls today's index value, the projected rate will be wrong because the actual adjustment uses last month's number. Build the lookback into your calculator or pull the historical index data before running the projection.
Lifetime cost scenarios
With a 7/1 ARM, the worst-case scenario depends heavily on the lifetime cap. On a standard 5% lifetime cap, a loan starting at 5.75% can never exceed 10.75%. But the payment at that rate on a $350,000 balance with 25 years remaining is roughly $3,214 per month. That is a $1,168 increase from the initial payment. If rates spike early in the adjustment period, the payment jump hits hard before the borrower has had time to sell or refinance. Conversely, if rates stay low, the borrower pays less each month after year seven compared to a fixed loan at the same initial rate. The variability is real and favors different outcomes depending on when you bought and when you sell.
What calculators cannot tell you
No spreadsheet captures every nuance of your specific loan. Some lenders include payment shock caps that limit the dollar increase in the monthly payment, regardless of the rate change. Others use a conversion factor or a different day-count method. If you are relying on a generic calculator for a decision, verify the output against your actual loan documents. Run the first adjustment through the lender's disclosure statement. If the numbers don't match, the calculator is using assumptions that don't apply to your loan.
When a 7/1 ARM makes sense
These loans work best when you plan to sell or refinance before the adjustment period begins. The rate is typically 0.5% to 0.75% below a 30-year fixed at origination. On a $350,000 loan, that saves roughly $200 to $250 per month during the fixed period, or about $16,800 over seven years. If you move before year eight, you keep the savings. If you stay past the adjustment window, you are exposed to rate volatility with limited ability to lock in a predictable payment.
Final note on accuracy
The closer you get to the actual loan terms, the more the calculator matters. Use the exact index, margin, caps, and adjustment frequency from your promissory note. Don't substitute industry averages. A calculator with the right inputs will project the payment path accurately. One with assumed values will give you a rough estimate that may miss significant details when the adjustment actually hits.