Why Your Extra Payment Doesn't Always Work Like You Expect
I spent years watching people blow past their mortgage payoff dates because they kept making the same mistake: they told their servicer to apply the extra money toward principal, but their servicer applied it to the next month's escrow and interest instead. It's not your fault the system makes it confusing. Most mortgage payment calculators online assume you want everything lumped into one clean monthly box. But the real world doesn't work that way, and if you're trying to use a Mortgage Payment Calculator Additional Payments feature, you need to understand exactly what each number is telling you before you move any money. Here's the core mechanic nobody puts in the help docs. When you make a regular monthly payment, it goes in this order: late fees first, then escrow (property taxes and insurance), then interest, then principal. That's how the law requires it. So when you throw an extra $500 or $1,000 at your mortgage, that payment hits the same pipeline. If you're not careful, your extra dollars get buried behind other charges and the calculator won't show you the savings you thought you'd get.
Using Mortgage Payment Calculator Additional Payments Without Getting Burned
The most important setting on any online calculator is what the extra payment is actually reducing. Some calculators let you toggle between "reduce term" and "reduce monthly payment." This matters enormously. If you choose to reduce the monthly payment, you're not saving on interest at all — you're just making your life easier every month while dragging the loan out longer. The interest savings from an additional payment only happen when you tell the calculator you're shortening the term. That's the difference between keeping an extra $3,200 in your pocket over the life of a standard 30-year loan at 6.5 percent and paying that money straight to the bank. Another thing that trips people up: most free calculators assume your extra payment arrives on the first of the month. It rarely does. If you make the extra payment on the 15th, half a month of interest has already accrued since your last payment. The calculator won't show you this gap unless it has a field for the actual date of the additional payment. I had a borrower once who ran the numbers, saw his loan would be paid off 14 months early, and then got confused when his servicer's actual statement showed only 9 months shaved off. The discrepancy came entirely from the timing mismatch between the calculator's assumption and his real-world payment date. He just needed a calculator that let him plug in the exact day.
The Mechanics Behind the Calculator Numbers
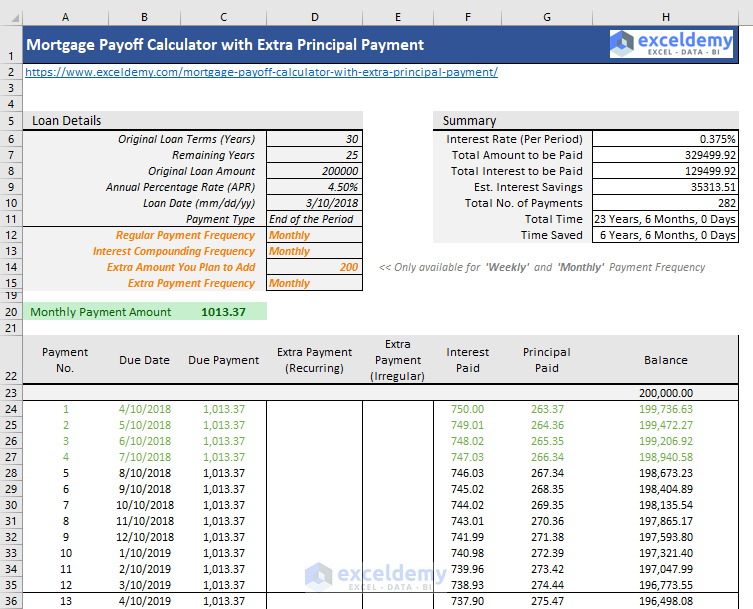
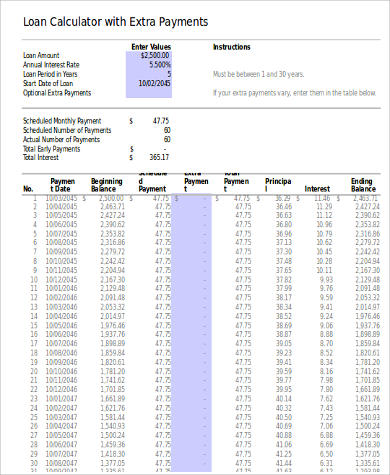
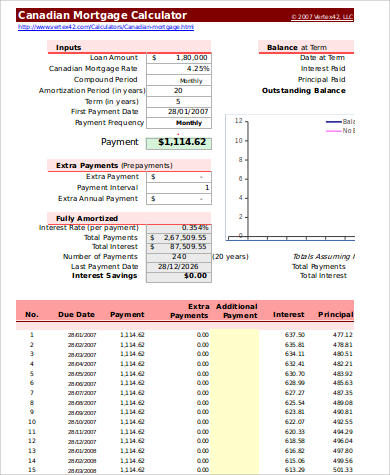
An amortization schedule is just a table that shows how each payment is split between interest and principal over the life of the loan. Early in the loan, most of your payment goes to interest because the principal balance is still high. As the balance shrinks, less interest accrues and more of your payment eats into principal. When you add an extra payment, you're forcing that balance down faster than the schedule planned for it. The interest for the next month is then calculated on a smaller number. That's literally all an additional payment does — it makes the next interest calculation start from a lower base. The rest of the math follows from there. Here's where most calculators mislead you. They show the total interest saved across the entire loan, which sounds impressive. But they don't always tell you how much principal you're actually reducing in each individual month, and that's the detail that matters for planning. If you're budgeting an extra $400 a month, you need to know whether that $400 wipes out $380 in principal or $200 in principal with $200 going to reduce the final interest cost. The two scenarios feel very different when you're managing your cash flow.
Get the Full Details

Common Pitfalls That Free Calculators Won't Warn You About
Escrow shortage traps. If your mortgage has an escrow account and you make frequent additional principal payments, your servicer may recalculate your escrow portion and adjust your total monthly payment up. The calculator won't show this. I've seen people add $2,000 a year in extra principal payments and then get hit with a $40-per-month escrow increase because property taxes went up. Their actual savings were smaller than the calculator projected. Prepayment penalties. Some loans, especially certain adjustable-rate mortgages and investor loans, carry a prepayment penalty clause for the first three to five years. A Mortgage Payment Calculator Additional Payments tool will happily crunch the numbers as if you can throw any amount at the loan anytime. Check your closing disclosure for a section labeled prepayment penalty. If you're within that window, your extra payments might cost you 2 to 3 percent of the amount you're paying early. Interest calculation method. Most residential mortgages use a simple daily interest calculation: principal balance times annual rate divided by 360. A few lenders use a 365-day year, and some commercial loans use compound daily interest. If your loan uses 360 days per year, your extra payment reduces your principal slightly less efficiently than a 365-day loan would. The difference is small but real — about 0.7 percent more interest accrues over a full year. If you're comparing loans, ask which method your servicer uses before you plan your extra payment strategy.
A Practical Workaround I Use
When I need to model additional payments accurately, I don't trust any single online calculator. I build a simple spreadsheet with three columns: payment date, regular payment amount, and extra payment amount. Each row calculates the remaining principal after that payment using the daily interest formula, then subtracts the new principal from the old to find the principal reduction. It takes me about 10 minutes to set up, and once it's built, I can plug in any extra payment on any date and see exactly how the balance changes month by month. If you want a simpler path, there are a few dedicated tools that handle date-specific additional payments without requiring a spreadsheet. The downside is that they usually only support 30-year fixed conforming loans. If you're on a 15-year, an ARM, or an interest-only phase, the calculator will give you wrong numbers. I ran into this with a client who had a 5/1 ARM during its adjustment year. Every calculator she tried assumed a fixed rate through 30 years. The results looked like a dream, but the loan was already resetting and her rate had jumped to 7.8 percent. The calculator's answer was useless for her situation. She ended up using the spreadsheet method I described, which at least let her input the actual rate and term for whatever period she was in.
What to Watch For Before You Commit
The biggest blind spot in every additional payment calculator is the assumption that your loan terms stay constant. They don't. Refinances happen. Rate adjustments happen. Your property tax assessment can change every year. A calculator that shows you paying off your loan in 22 years instead of 30 is giving you a snapshot, not a guarantee. I've seen more people get discouraged when their actual payoff date drifted away from the calculator's projection than I have seen people who were blindsided by bad outcomes. The calculators are useful for understanding the general direction, but they're not binding commitments from your lender. Another thing to check before you start making extra payments: your loan's negative amortization clause. Some adjustable-rate products let the minimum payment be less than the interest due, and the unpaid interest gets added to the principal. If you're on one of these loans, throwing extra money at the principal every month helps, but it won't eliminate the compounding negative amortization unless you also bring the loan current on the minimum payment side. It's an edge case, but it's the kind of detail that eats people who don't read their promissory notes closely. If you're considering using any Mortgage Payment Calculator Additional Payments tool, start with the calculator, then verify at least one result against a manual calculation or a spreadsheet. That one cross-check will catch most of the errors before you commit real money to it.