How to Actually Use a Mortgage Payment Calculator for Oregon Loans
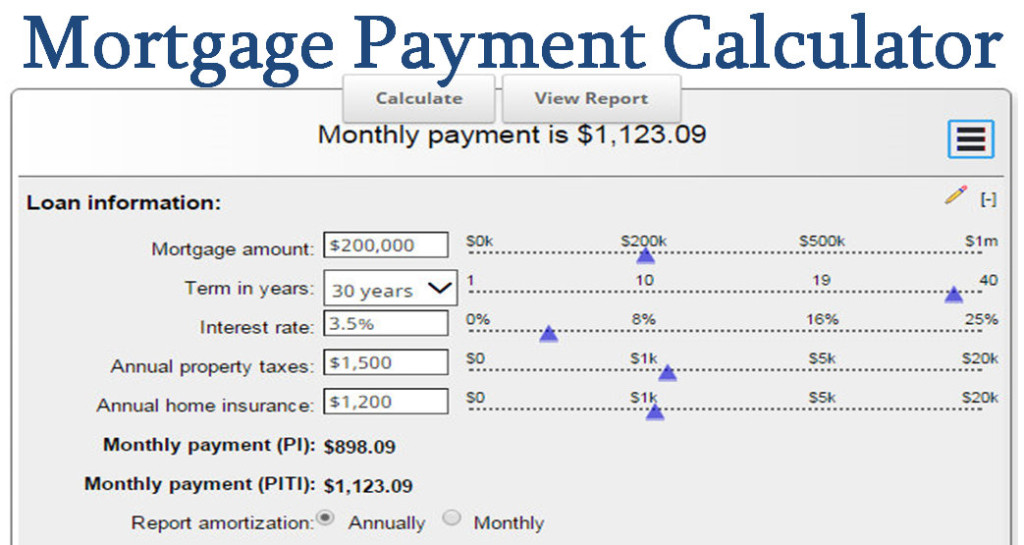
Most people treat mortgage calculators like they're magic boxes that spit out a number and suddenly you know your monthly payment. That's not how it works. You feed it data, it returns an estimate, and then you realize the estimate doesn't match what the lender quotes because something got left out. Here's how to do it right and avoid the gaps that mess up your budgeting.The core calculation is the standard amortization formula, but Oregon-specific adjustments matter more than most online calculators account for. Property taxes in Oregon vary wildly by county, and the state has no income tax but does have a Transfer Tax on sale. If you're buying rather than refinancing, that transfer tax eats into your available funds and changes how much you can comfortably pay monthly. To run the basic payment, you need four inputs: loan amount, interest rate, loan term, and property tax estimate. Everything else — homeowners insurance, PMI, HOA fees — is layered on top. Skip any of these and your number will be too low, usually by a meaningful margin. A $400,000 loan at 6.5% over 30 years gives you roughly $2,528 in principal and interest. Add Oregon's average effective property tax rate of about 0.97%, which comes to roughly $323 a month on that home value. Insurance runs another $100 to $180 depending on location. You're looking at $2,950 to $3,030 all-in, not $2,528. Here's a practical problem I ran into recently. A borrower was comparing two calculators and getting $400 differences between them for the same input numbers. Turns out one was using a 365-day year for daily interest accrual and the other was using a 360-day banker's year. Both are valid depending on the loan type. Conventional loans typically use 360-day accrual. FHA and VA loans sometimes use 365. If you're doing this yourself and need accuracy down to the cent, check which day-count convention your lender uses before you trust the number. The workaround is simple: take the calculator output, multiply by your loan's actual daily interest factor, and adjust. For a $400,000 loan at 6.5%, the difference between 360 and 365 days adds about $23 to your first payment. Over the life of the loan it compounds into roughly $200 in total additional interest.
Another thing calculators rarely handle correctly is Oregon's mortgage debt exemption. Oregon allows a homestead exemption of up to $50,000 in equity protection, but that doesn't reduce your payment. It only matters if you're facing creditor claims. What actually affects your payment is the property tax reform angle. Some Oregon counties have rolled assessments differently post-ballot measure changes, and your assessed value might not match what your property tax bill shows for the current year. Run your calculator using the current tax bill amount, not the assessed value divided by 100, or you'll be off by a significant chunk. If you want a downloadable tool, most state mortgage resources and lender sites offer Excel-based calculators that include Oregon tax fields. Search for the Oregon Department of Consumer and Business Services mortgage resources page, or use a standard financial calculator like the one on NerdWallet or Bankrate and manually override the tax and insurance fields with Oregon-specific numbers. Don't rely on a generic national calculator's built-in tax estimate — its default assumes a national average that understates Oregon costs in many counties. For those who need this offline or want to build their own, the formula in Excel or Google Sheets is straightforward. Use the PMT function for the principal and interest portion:
=PMT(rate/12, nper, -loan_amount) Where rate is your annual interest rate, nper is total number of payments, and loan_amount is the principal. Then add your monthly tax and insurance estimates as separate cells. Sum them all. Keep property tax and insurance in separate cells so you can swap in actual bill amounts when they come. Rates lock for 30 to 60 days typically, but your tax and insurance numbers can shift before closing. The biggest limitation of any mortgage payment calculator is that it cannot predict your actual closing costs or your final interest rate. It can show you the payment range, but if rates move between when you calculated and when you locked, your number changes. It also cannot account for special assessments, MUD district fees, or wildfire insurance surcharges that are becoming common in certain Oregon counties. Lenders will tell you these get baked into your escrow analysis at closing, but if you're budgeting ahead of time, add a $50 to $150 monthly buffer for items your calculator won't show you.
Get the Full Details

Another counter-intuitive point: a higher interest rate doesn't always mean a higher monthly payment compared to a lower rate with mortgage insurance. A 7% rate with no PMI on a conventional loan can sometimes result in a lower total payment than a 6% rate with PMI, depending on your down payment. The PMI drops off at 20% equity, but until it does, the combined cost can surprise people who only look at the rate and ignore the insurance line item. Always calculate the full PITI, not just P&I. Bottom line: run the calculator, verify your inputs against actual Oregon tax bills and insurance quotes, adjust for the day-count method your lender uses, and add a buffer for the things the calculator doesn't know about yet. It takes about 15 minutes to set up properly and saves you from a payment shock at closing.