The Spreadsheet Nobody Warns You About
The first time I ran a Mortgage Payment Comparison for a client, I thought I was done in twenty minutes. Two hours later I was still chasing a $4 difference between my Excel model and the lender's disclosure. The problem wasn't the math. It was the hidden line items nobody asks about until you're staring at a $287 discrepancy on a paper that supposedly explains everything. At its core, the calculation is just amortization math. You take the principal, apply the monthly interest rate, subtract the payment, and repeat for the life of the loan. But that's the skeleton. The real work happens in the soft tissue — escrow variances, annual interest recalculation windows, and the way different lenders handle escrow shortfalls at closing. I've seen three different payment schedules come back from the same underwriter on the same loan because they were using three different assumptions about when the escrow account gets capped. Here's the practical method I use now. I build a comparison sheet with four tabs. The first is the base amortization for each loan option using the fully-loaded note rate. The second is the escrow projection, pulling property tax and insurance from the local jurisdiction data — not the lender's estimate. The third is the cash-to-close reconciliation, because the comparison you care about is what actually leaves the borrower's bank account each month, not just the principal and interest figure. The fourth is the sensitivity analysis: what happens if rates adjust on an ARM, what happens if taxes jump 12 percent like they did in one county last year and nobody had budgeted for it.
The Trap With Biweekly Schedules
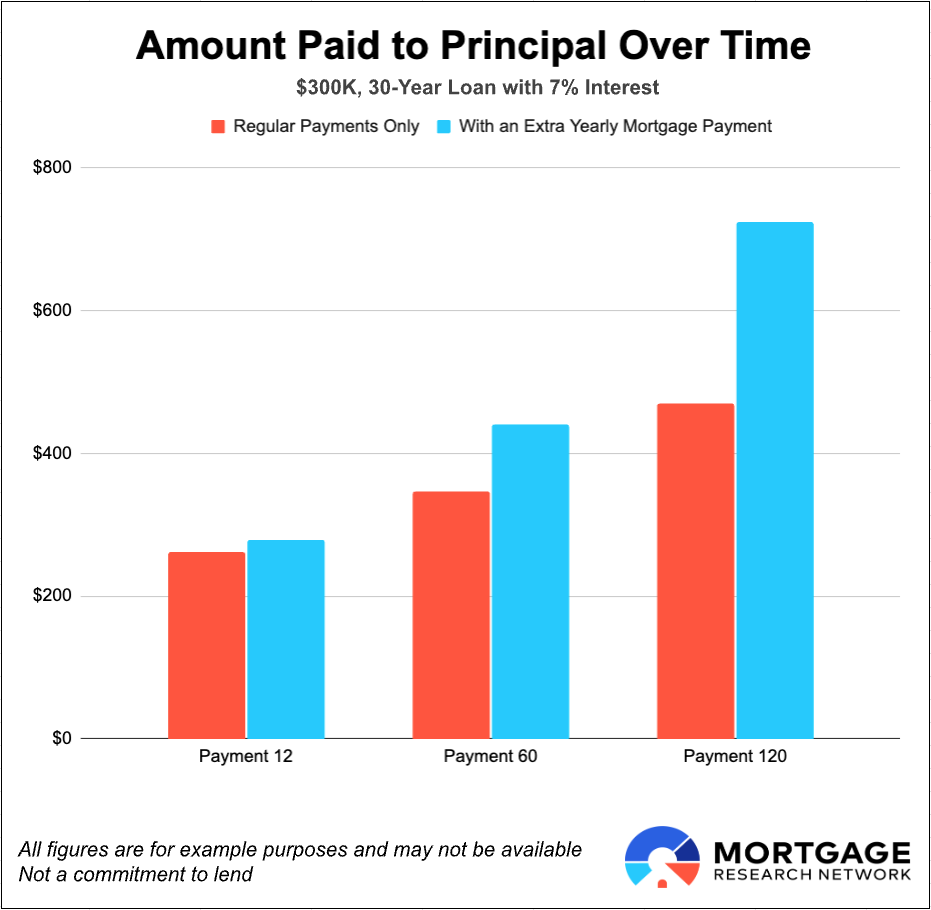
I ran into this with a client who was comparing a traditional monthly payment against a lender's biweekly program. The marketing materials claimed the borrower would save over four thousand dollars in interest over fifteen years. The numbers looked right at first glance. They weren't. The issue was that the biweekly program recalculated the interest portion at the end of each calendar year based on the remaining balance, and my spreadsheet was doing it monthly. That gap between annual recalculation and monthly amortization creates a compounding drift that becomes visible around year seven. Over the full term, it adds up to roughly two hundred dollars in unaccounted interest. The workaround was to model the biweekly schedule using the same annual recalculation logic — I just changed the frequency parameter in the amortization function and forced an annual balance reset at each December 31 cutoff. After that, the numbers aligned exactly with the lender's projection. It took me about ten minutes to set up once I'd figured out the pattern, and I haven't had to redo it since.
What Beginners Miss
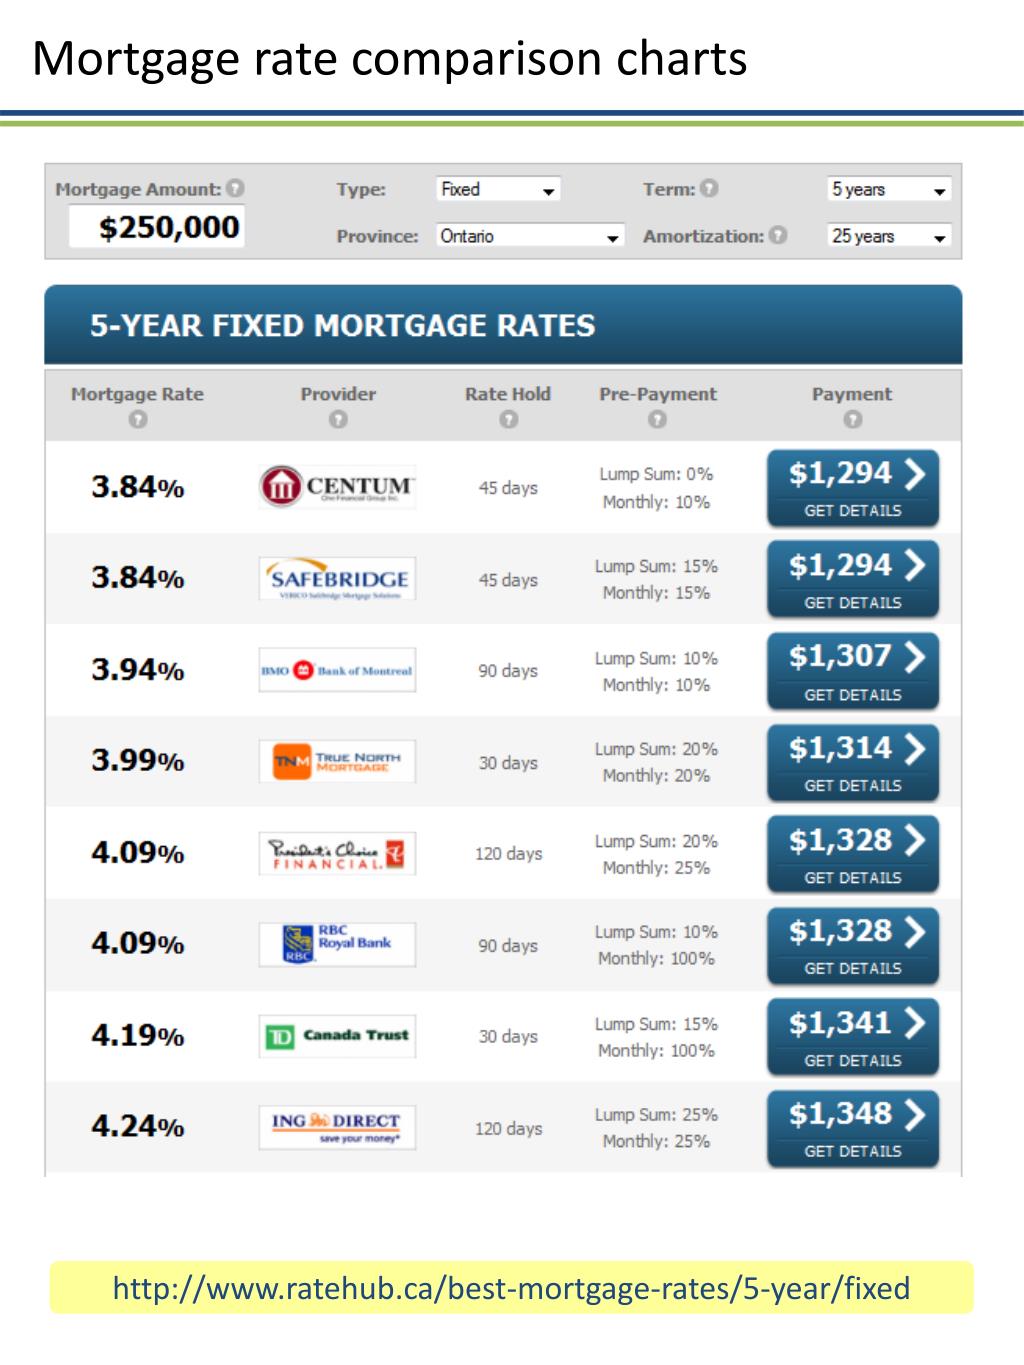
Most people compare monthly payments and stop there. The real cost lives in the breakage fee on refinances, the discount points versus rate buydown tradeoff, and the way an escrow shortage gets swept into the payment calculation for up to twenty-four months after it occurs. I've had borrowers choose the lower monthly payment only to discover their taxes were estimated at 2019 rates and their actual payment was going to double in eighteen months when the reassessment kicked in. That's not a mortgage comparison problem. That's a property tax forecasting problem wearing a mortgage costume. Another thing that trips people up: the front-loaded interest myth. Yes, early payments are mostly interest. But the speed of equity accumulation matters more than the interest ratio. A $30 per month higher payment on a 15-year versus a 30-year might feel worse each month, but the borrower is down to roughly twelve years of payments instead of thirty, and the total interest paid drops by about sixty-two percent on a typical loan. That sixty-two percent figure is the number that matters, not the monthly discomfort.
Get the Full Details

Limitations of This Approach
Spreadsheets are only as good as the assumptions baked into them. If you don't have current property tax data for the jurisdiction, your escrow projection is a guess. If the loan program has unusual prepayment penalties — like a 3 percent charge in year one that drops to 2 percent in year two and disappears in year three — you need to model that explicitly or your comparison will mislead you. I've seen people recommend a five-tool calculator approach, but half of those tools don't account for the yield spread premium that lenders slip into the rate. The other half use outdated amortization functions that round at the wrong interval. The honest answer is that no single tool does this perfectly. My spreadsheet handles the math, but the human work is in the data entry and the judgment calls about which numbers to trust. When I'm unsure about a lender's escrow projection, I pull the actual tax bills for the property from the county assessor's website instead of relying on the lender's estimate. That usually saves me from building a comparison on a false foundation.
Where to Find the Template
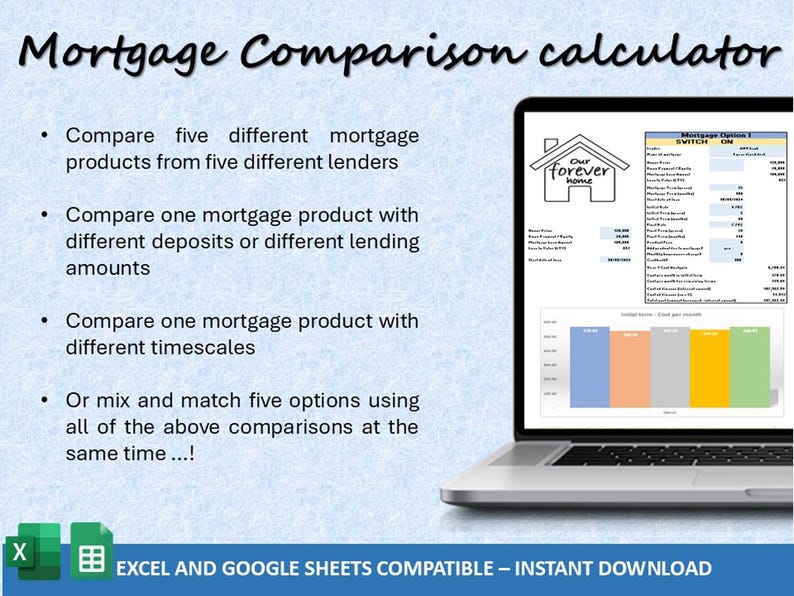
I've packaged my comparison spreadsheet into a .xlsx file. It includes the base amortization tab, the escrow projection tab with sample property tax rates for reference, the cash-to-close reconciliation, and the biweekly adjustment logic I described. The formulas are unlocked so you can adapt them to your own loans. You'll find the download at the link below.