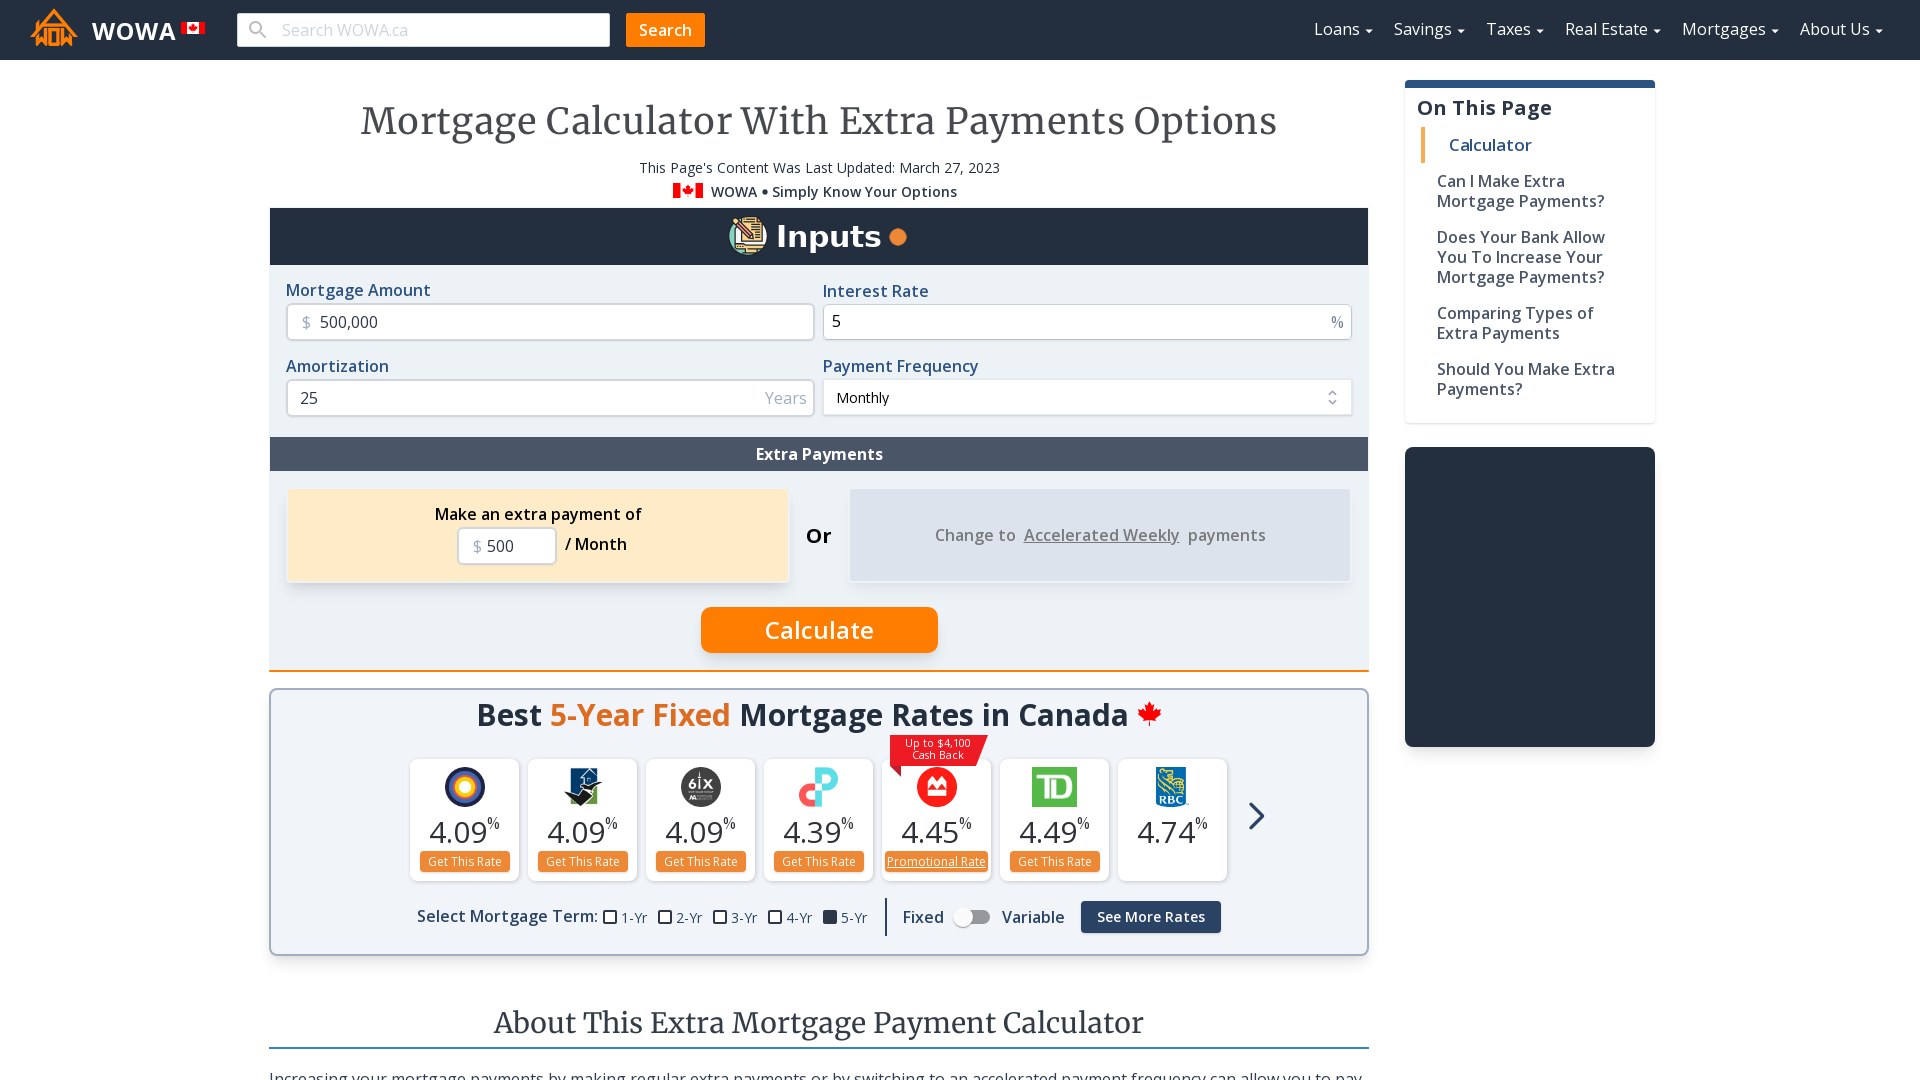
How Extra Payments Actually Work on Your Mortgage
Most people think throwing extra money at their mortgage is straightforward. It is, mostly. But the details matter, and if you skip them you might be making things harder than they need to be. I have seen too many borrowers do this wrong over the years, usually because their servicer makes it deliberately unclear. The basic mechanic is simple. You owe a monthly principal and interest payment. If you pay more than that amount, the surplus goes toward reducing your principal balance faster than scheduled. Less principal means less interest accrues each month going forward. Over time, this shortens the term and reduces total interest paid. That is the theory. The reality involves a few operational quirks.
Mortgage Payment With Extra Payments
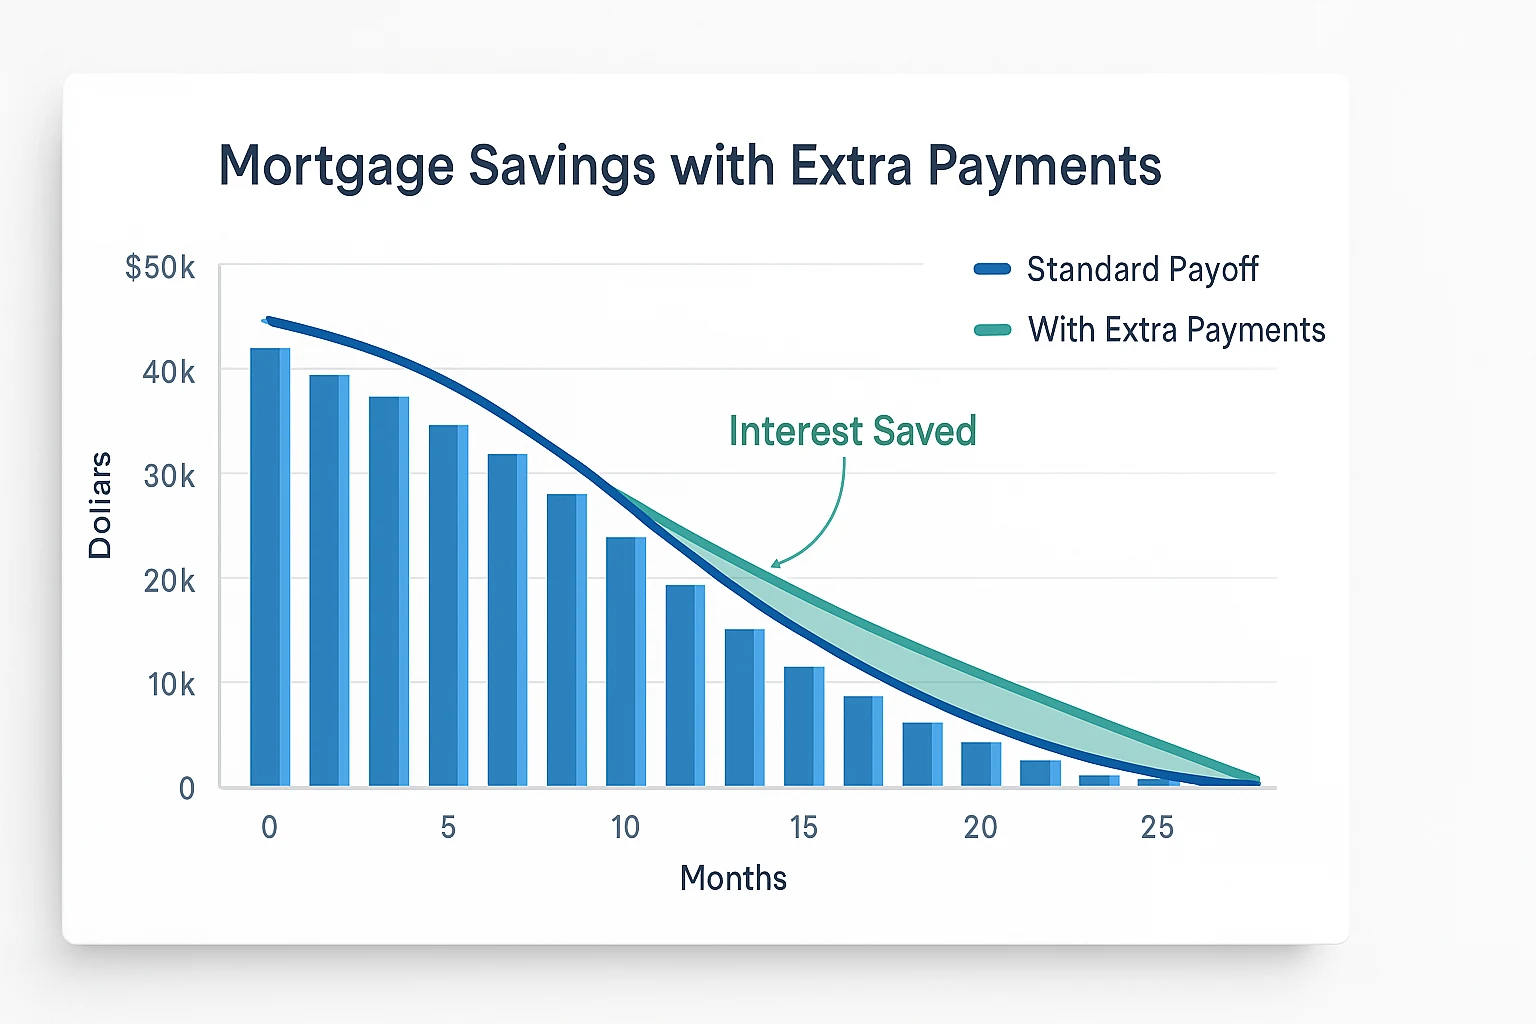
Here is how you actually do it. When you send in your payment, you need to specify how the extra amount should be applied. Some servicers automatically apply extra funds to principal. Most do not, at least not without you asking. You will typically see options during payment setup: apply to current balance, apply to principal, or hold as a reserve credit. Choose the principal application. If you are paying by check, write the principal amount on the memo line. If you are paying online, look for a checkbox or dropdown that says "principal only" or "additional principal payment." I learned this the hard way. A few years back I was helping a client who had been sending extra payments for nearly two years without realizing his servicer was treating every dollar above his monthly obligation as a credit toward next month's payment. Nothing was being applied to principal. He had no idea. The fix required a phone call, a written request to reclassify past payments, and three weeks of back-and-forth while they manually adjusted his ledger. It worked out, but he lost nearly two years of interest savings because nobody told him to specify. Get in writing from your servicer that extra payments are being applied to principal. Do not take their word for it over the phone. There is a structural advantage most people do not calculate correctly. When you make an extra principal payment, you are not just reducing the current balance. You are reducing the base upon which future interest is computed. This creates a compounding effect in your favor, in reverse. Each extra payment saves you interest on every remaining month of the loan. On a typical 30-year fixed at 6.5%, an extra payment of just $200 per month can shave roughly 4 to 5 years off the loan term and save somewhere between $30,000 and $50,000 in total interest, depending on where you are in the amortization schedule. The earlier you start, the bigger the impact. A $200 extra payment in year one is worth significantly more than the same $200 in year fifteen.
One counter-intuitive thing to understand: making one extra payment per year, often called a biweekly strategy, is mathematically different from paying half your monthly amount every two weeks. The biweekly approach forces 26 half-payments, which equals 13 full payments per year. That single additional payment is what does the heavy lifting. But if you simply double up your regular payment once a year, the result is nearly identical and easier to manage mentally. Pick whichever you can stick with consistently. Consistency beats complexity every time. Another nuance that trips people up involves escrow. Your total monthly mortgage payment usually includes principal, interest, taxes, and insurance. Extra payments only affect the principal and interest portion. If your servicer bundles everything together and you send a lump sum, you need to make clear that the excess is principal-only. Otherwise it might sit in your escrow account and do nothing for your loan balance. Escrow accounts are regulated, and lenders cannot freely apply funds there without purpose. But they also will not automatically route overflow to principal without your direction. I also ran into a case where a borrower sent an extra payment and the servicer applied it to a future due date instead of current principal. This happened because the payment arrived after their cutoff and the system defaulted to holding it. The borrower thought they had made progress. They had not. Always confirm the application date and the allocation breakdown on your next statement. Do not assume. A twelve-minute check on your online portal can prevent months of confusion.
Get the Full Details
There are scenarios where this approach fails or backfires. If your loan has a prepayment penalty clause, extra payments could trigger fees. Some loans, particularly certain adjustable-rate mortgages or loans originated during specific periods, carry these penalties for the first three to five years. Check your closing documents. If you have one, the penalty is usually capped at a percentage of the prepaid amount, but it can still erode your savings. Another limitation: if you are close to refinancing, making extra principal payments right before you apply may not make sense. You would be paying down a balance you are about to replace. In that case, the extra payment provides no benefit unless you are aiming for a specific debt-to-income ratio or hoping to remove private mortgage insurance sooner. Private mortgage insurance deserves a mention here. If you have PMI, accelerating your principal reduction can help you reach the 78% or 80% equity threshold faster, at which point you may qualify for automatic cancellation or can request removal. This is one of the most underutilized aspects of extra payments. The timeline varies by loan type and home value appreciation, but cutting your term by even a couple of years can meaningfully accelerate PMI elimination. For tracking, I recommend a simple spreadsheet. Column one: original loan balance and terms. Column two: monthly payment amount. Column three: extra payment amount each month. Column four: running principal balance after each payment. Column five: projected payoff date. Update it once a quarter. You do not need fancy software. A basic spreadsheet with standard amortization formulas will give you a clear picture within five minutes. If you want something automated, most servicer portals provide an amortization schedule you can download. Pull it annually and compare it against what you expect to see after your extra payments.
The biggest mistake I see is inconsistency. People get excited, ramp up extra payments for three or four months, then drop back because life happens. That is fine. Any principal payment helps, regardless of size or frequency. But if you want to see real acceleration, you need steady pressure over time. A modest extra payment made every single month beats a large lump sum made once a year, simply because the smaller principal balance is compounding fewer days each month. The math is not dramatic, but it is noticeable over a decade. If you cannot commit to monthly extras, consider redirecting tax refunds, bonuses, or other windfalls. Even irregular payments reduce your balance and the interest that flows from it. Just make sure each one is properly designated as principal. And if your servicer ever gives you grief about how to apply the funds, ask for their written policy. They are required to have one, and it is almost always simpler than they make it sound.