How to Actually Use a Mortgage Rate Comparison Calculator
A Mortgage Rate Comparison Calculator is a straightforward tool. You plug in the loan details from two or more lenders, and it shows you the difference in monthly payments, total interest paid, and sometimes the effective APR. It sounds simple. It mostly is. But the way people use it is where things go sideways. Most borrowers type in the interest rate and run the numbers, then pick the loan with the lowest rate. That is the wrong move. You need to compare apples to apples, and the calculator only helps you do that if you feed it the right inputs. What matters is not just the rate. It is the rate plus the points, the closing costs, the loan term, and how long you plan to hold the loan.
How the Mortgage Rate Comparison Calculator Actually Works
Here is the basic math the tool uses to compute your monthly principal and interest payment: M = P × [r(1+r)^n] / [(1+r)^n – 1] P is your loan amount. r is your monthly interest rate (annual rate divided by 12). n is the total number of monthly payments. This formula is standard for fixed-rate mortgages. Every comparison calculator on the market uses this same equation. The difference between two loans comes down to how P, r, and n change when you adjust the rate, the points, or the term.
I built a quick spreadsheet years ago to compare two loan offers I was evaluating. One lender quoted 6.5% with no points and $3,200 in fees. The other quoted 6.25% with one discount point and $4,800 in fees. On the surface, the second loan looks better. The rate is lower. But when I ran both through the calculator, here is what I found: Loan A at 6.5%: monthly payment of $1,733.68 on a $280,000 loan. Total interest over 30 years: $344,125. Loan B at 6.25% with one point: monthly payment of $1,723.04 on a $282,800 loan (the point cost was rolled into the balance). Total interest over 30 years: $336,294. But you also spent $4,800 upfront or rolled in, which eats part of that interest savings.
Get the Full Details
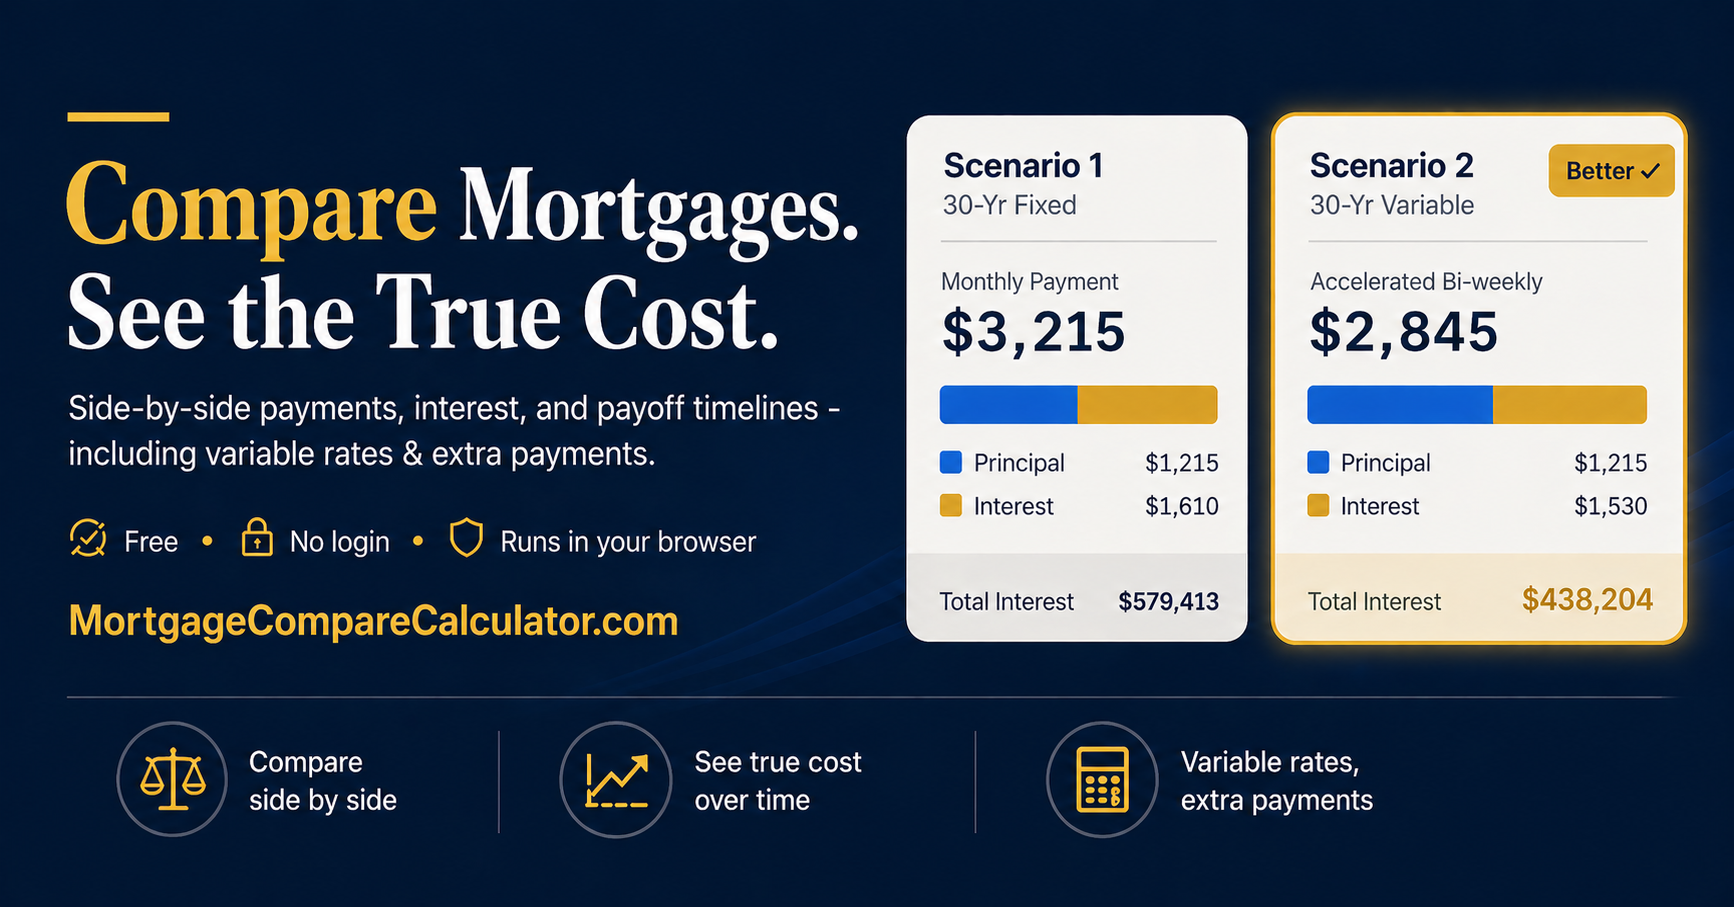
Over the full 30-year term, Loan B saves about $7,800 in interest. But if you sell or refinance within five years, the math flips. Loan B costs you more because you never recover the point you paid. This is the break-even calculation every comparison tool should show you, and not all of them do.
What the Calculator Gets Right
A good Mortgage Rate Comparison Calculator handles the core comparisons without forcing you to do the arithmetic yourself. The useful outputs are the monthly payment difference, the total interest difference, and the break-even period for any upfront costs. Some tools also calculate APR, which is the real cost number you should be looking at. APR factors in the points and most closing costs into an annualized rate. It is designed to let you compare loans that have different fee structures on a like-for-like basis. The thing people overlook is that APR is not the same as the interest rate. A loan with a slightly higher rate but lower fees can have a lower APR than a loan with a lower rate and heavy points. If you only look at the rate, you might pick the worse deal. Run both the rate and the APR through your comparison, and pay attention to which one tells the truer story for your situation.
Where the Calculator Fails You
Online calculators have real blind spots. They do not account for your specific tax situation. Property taxes and homeowner insurance are usually bundled into the escrow portion of a mortgage payment, but a basic rate comparison tool will not include those unless you manually enter them. Two homes in adjacent counties can have wildly different property tax bills. If you are comparing loans for different properties, this matters a lot. If you are comparing rates on the same property, it cancels out. Another gap is PMI. If your down payment is under 20%, private mortgage insurance gets added to your monthly payment. Some calculators include it. Most do not by default. I had a borrower once who compared two loans and picked the one with the lower payment, not realizing one included PMI and the other did not. The actual difference between the two was less than $40 a month, but it changed the whole decision. The biggest limitation is that these calculators give you estimated payments based on the numbers you enter. They do not replace a Loan Estimate from a lender. Your actual rate and fees will depend on your credit score, debt-to-income ratio, and the lender's pricing overlays. A 740 FICO score gets a different rate than a 680 score, even at the same lender. The calculator cannot know your score. It can only show you what the published rate means in dollar terms.
How to Use It Without Making a Mistake
Start by gathering Loan Estimates from at least three lenders. Do this within a 14-day window so the rate pulls from your credit report only once. Take the interest rate, points, and closing costs from each estimate and plug them into the calculator separately. Compare the monthly payment, the total interest, and the break-even point for each set of upfront costs. Pay attention to the loan amount too. Some lenders roll costs into the balance. Others require them to be paid at closing. A comparison tool will treat those scenarios differently, and the output changes. Make sure you are entering the same loan amount across all comparisons, or the numbers become meaningless. Also run a refinance scenario if you are already in a home. The break-even math works differently because you are comparing your current loan against a new one, not choosing between two purchase loans. You need to include your remaining balance, not the original loan amount, as the input. I learned this the hard way when I was helping a friend compare a refinance. She used the original loan amount instead of the remaining balance, and the calculator showed a savings that did not exist in reality. She ended up spending $600 on an appraisal and title search for a deal that barely moved the needle.
A Few Details People Miss
Jumbo loans do not always compare the same way as conforming loans. Lenders price jumbo loans differently, and the rate spread between lenders can be wider. A 0.25% difference on a conforming loan might look small. On a jumbo loan, that same spread can add up to thousands over the life of the loan because the principal is larger. Run the numbers explicitly. Do not assume a small rate gap is harmless. ARMs are another area where a simple comparison calculator can mislead you. The initial rate on an adjustable-rate mortgage is often much lower than a fixed rate. A basic calculator might show a dramatically lower monthly payment for the ARM. But that rate adjusts after the initial period. A proper comparison needs to model the adjustment scenarios, not just the introductory rate. If the tool you are using only compares fixed rates, it is not giving you the full picture for an ARM offer. There is also the question of loan length. A 15-year loan at a lower rate will have a higher monthly payment than a 30-year loan at a slightly higher rate, but the total interest paid is usually much lower. I have seen people skip the 15-year option because the monthly payment looked too high, not realizing the total savings over the life of the loan could exceed $80,000 on a typical loan. Plug both terms into the calculator. The number on the screen will tell you immediately whether the higher payment is worth it.
When a Calculator Is Not Enough
If you are working with a non-standard loan, a portfolio loan from a local bank, or a loan with unusual terms like interest-only or negative amortization, a standard Mortgage Rate Comparison Calculator will not give you reliable results. These tools are built for conventional fixed-rate and standard ARM products. They do not handle the math for everything else. In those cases, ask the lender for a written breakdown of the payment schedule and compare those documents directly. Also, if you are close to the 20% down payment threshold for PMI removal, the calculator will not automatically factor in the long-term savings from avoiding PMI. You might need to model that yourself by running the scenario with and without PMI and seeing how the total cost changes over time. A $50-per-month PMI difference sounds small until you multiply it by 60 months or more. The bottom line is that a rate comparison tool is a starting point, not a decision engine. It gives you clear numbers for the inputs you provide. It does not account for every variable that affects your actual cost. Feed it accurate data from real Loan Estimates. Check the break-even math. Look at the total cost, not just the monthly payment. And verify the results against your own situation before you sign anything.