Building a Mortgage Worksheet in Excel: What Actually Works
A mortgage worksheet in Excel is basically a spreadsheet that takes a loan amount, interest rate, and term, then breaks down the monthly payment into principal and interest while also showing how the balance pays down over time. That's the simple version. The real version is messier because lenders use different amortization methods, some loans include escrow, and private transactions often need extra fields for fees or points. I've built these for personal use, for clients, and for people who just wanted to verify their lender's numbers before signing. The common thread across all of them is that a basic amortization schedule alone doesn't tell you the whole story. Here's how I approach it now instead of starting from scratch every time.
Mortgage Worksheet Excel
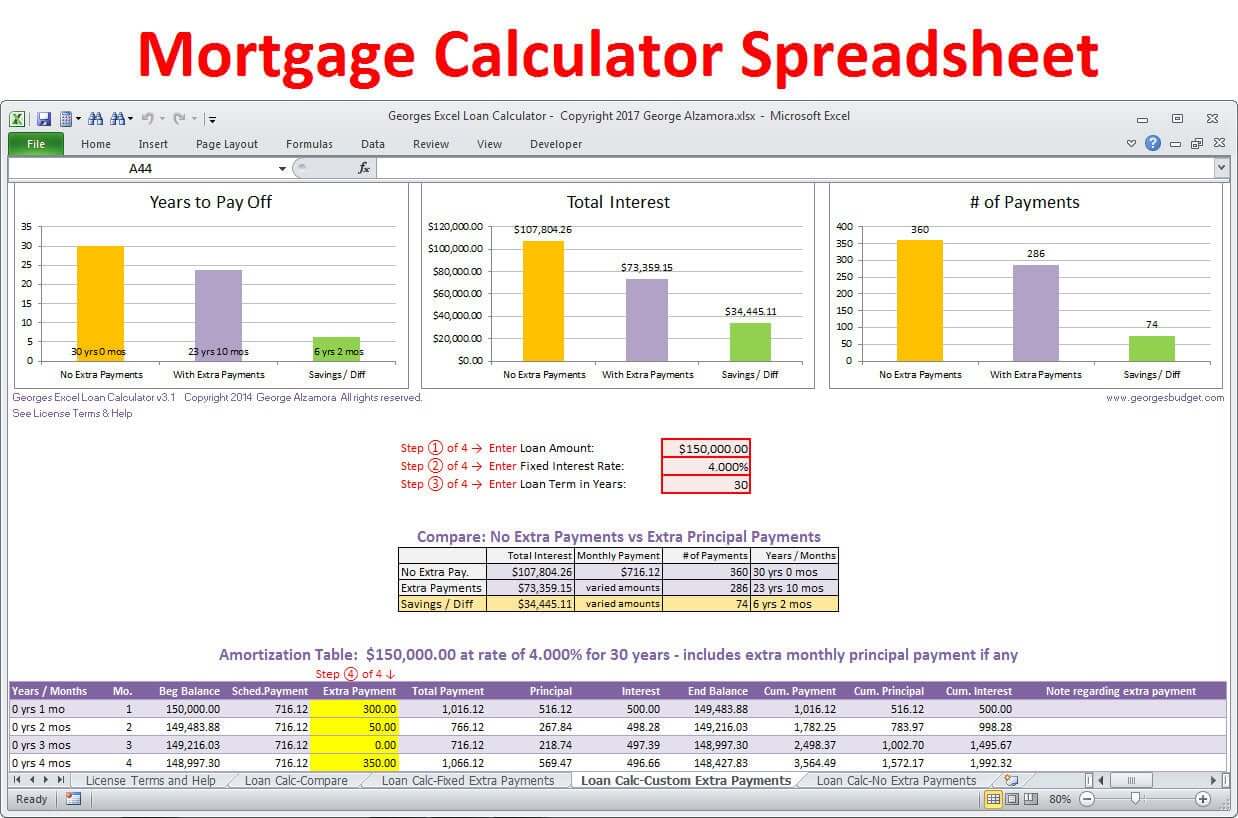
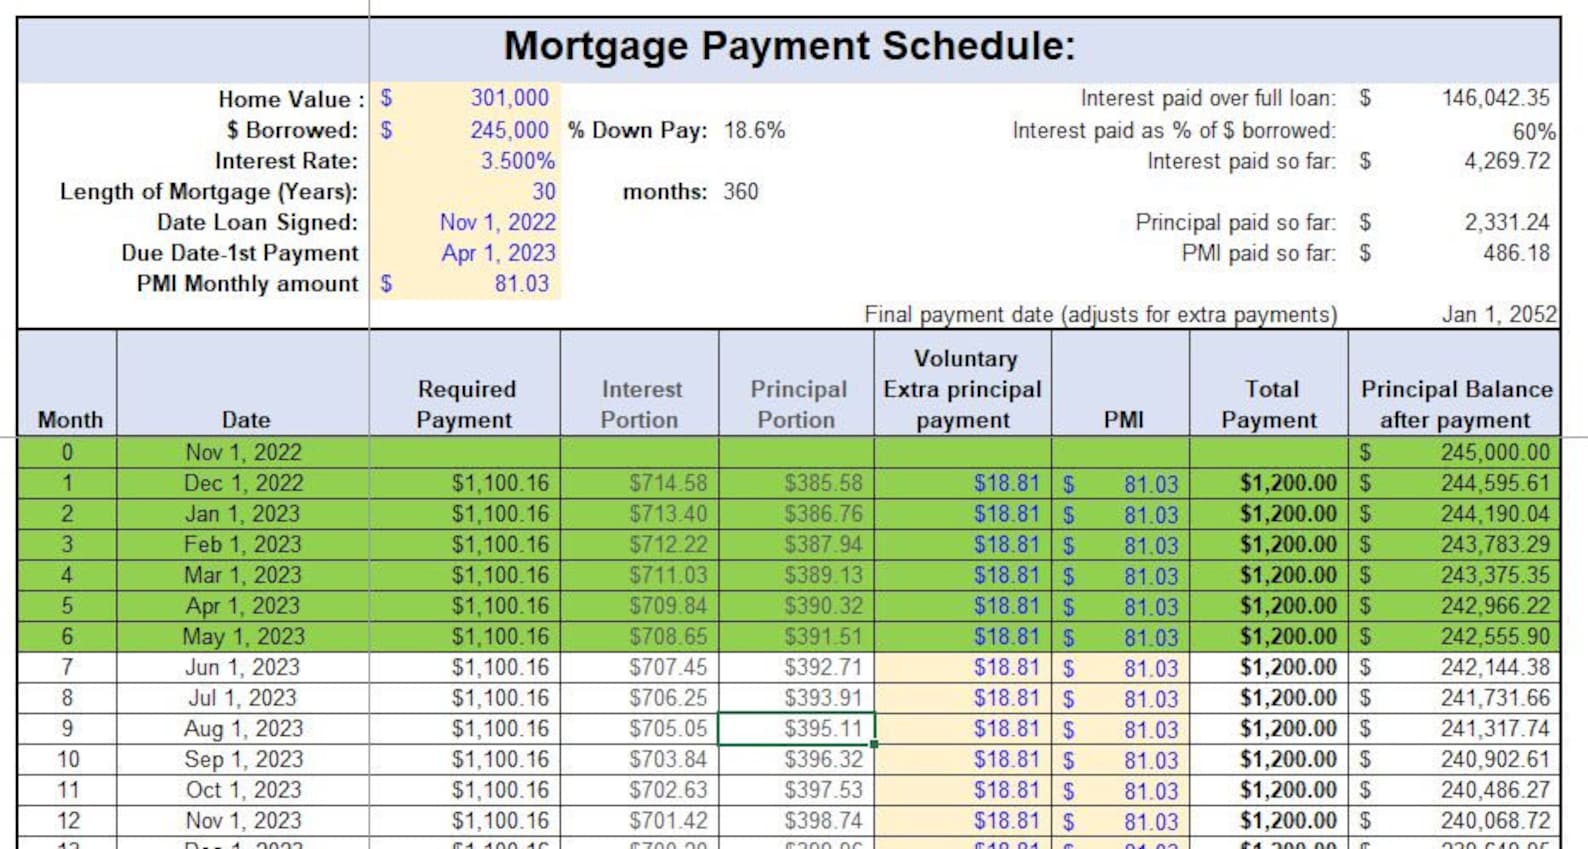
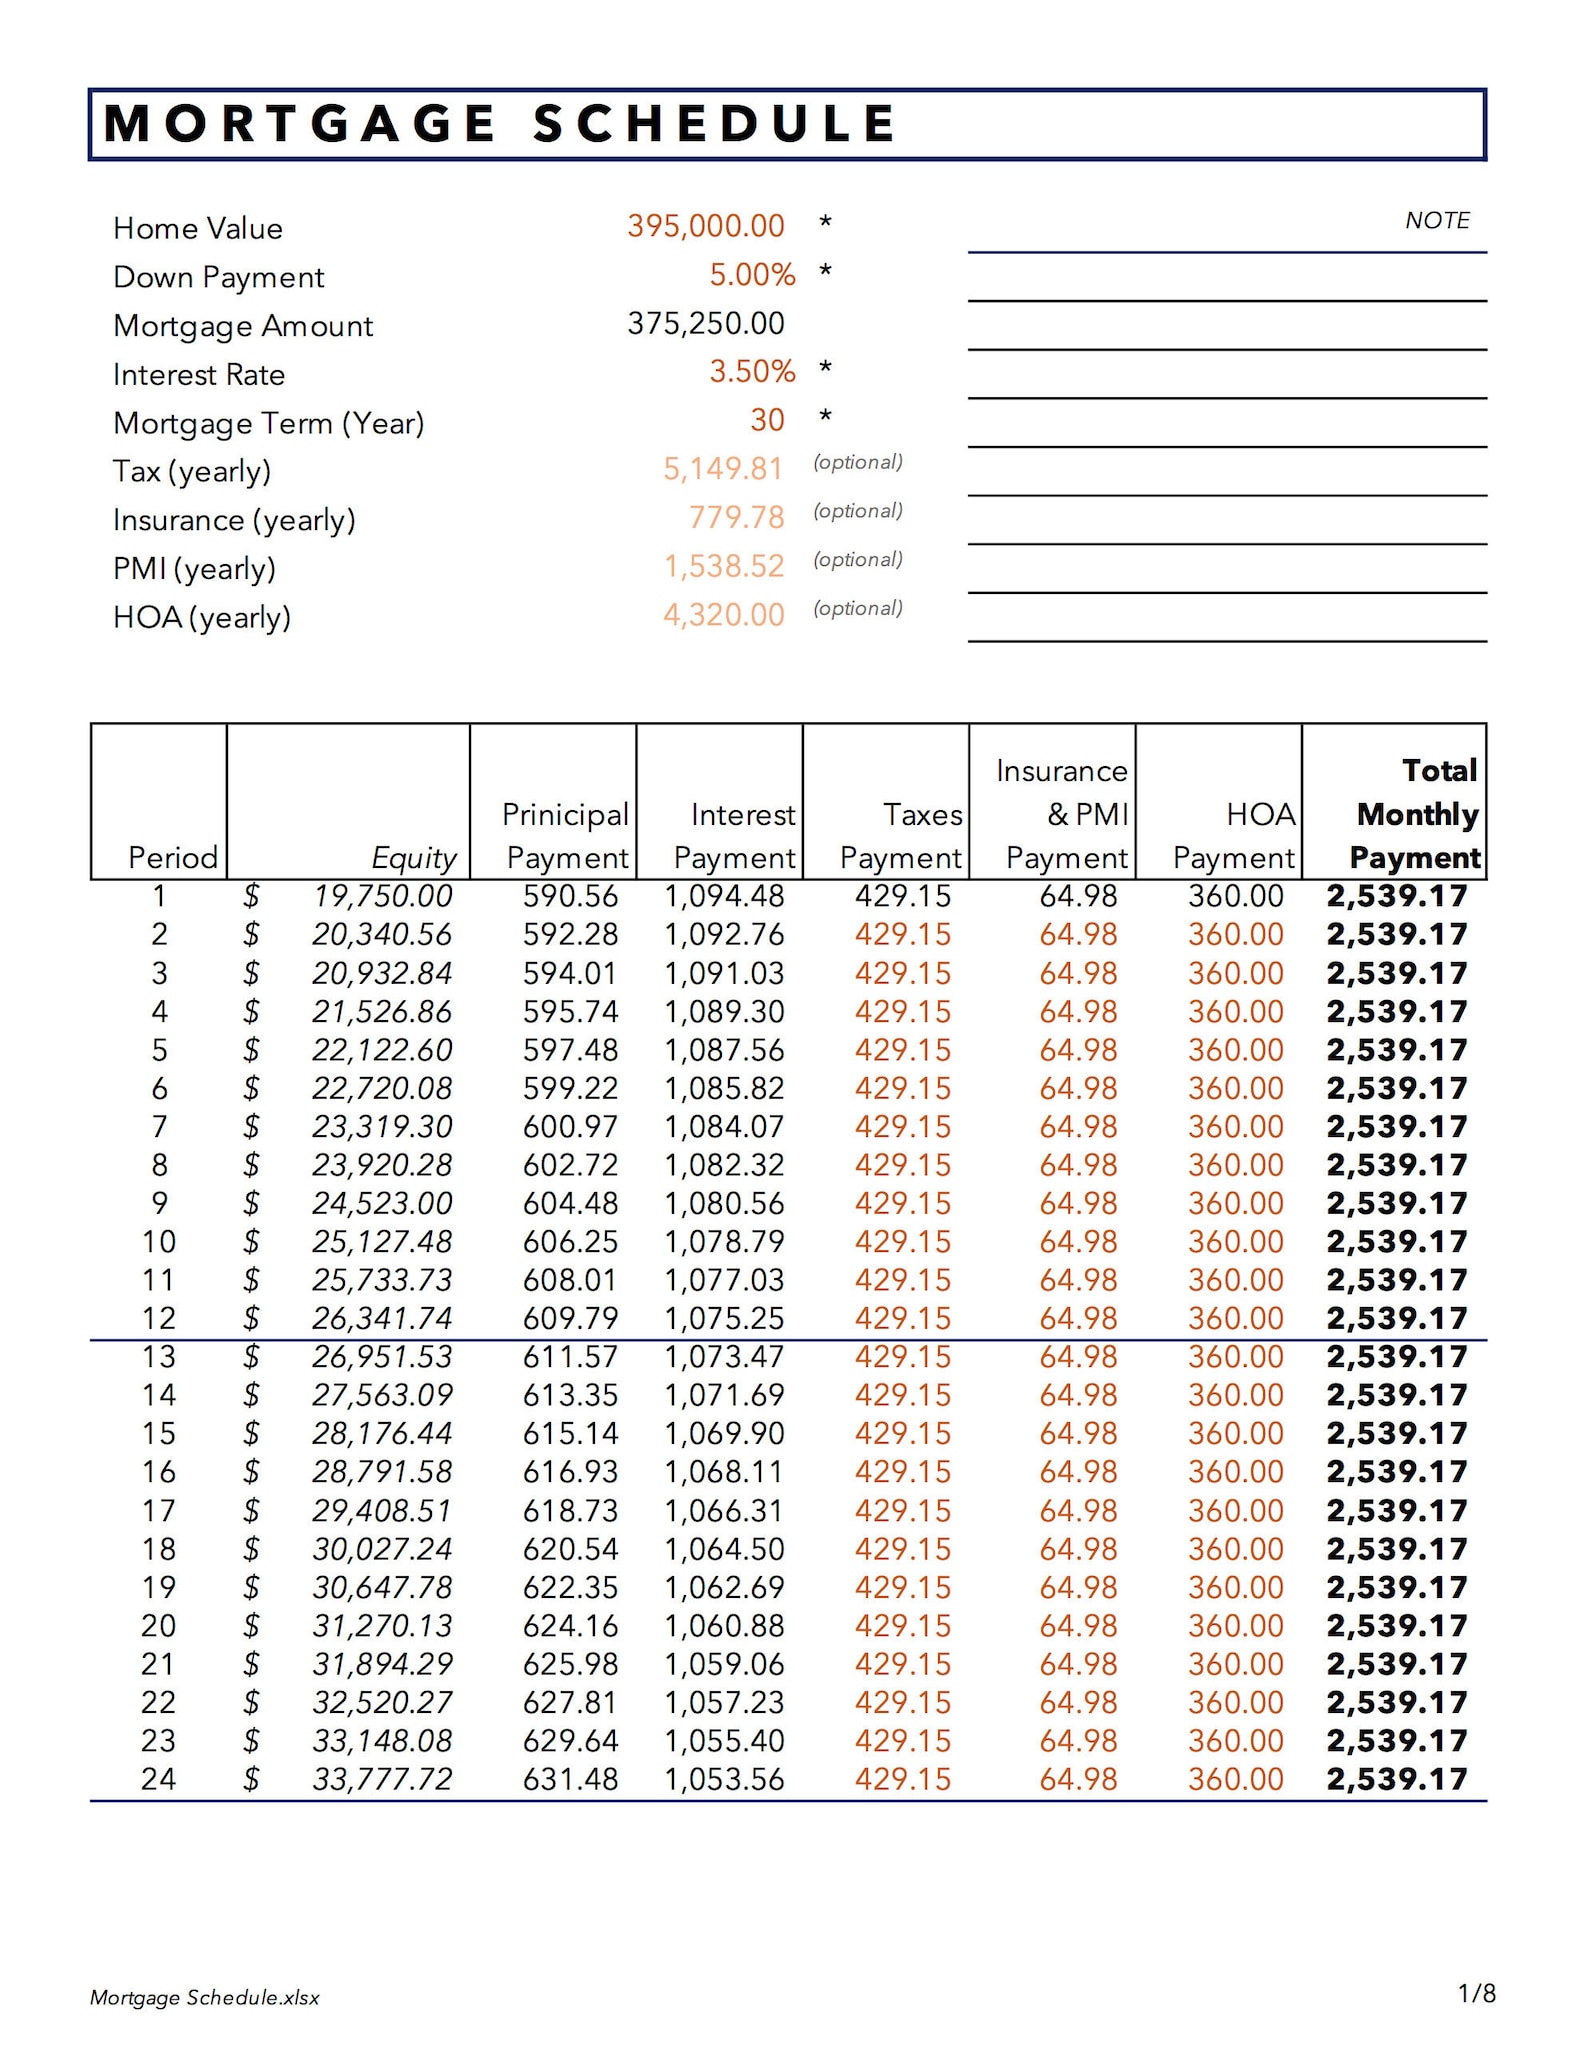
The core structure needs six columns at minimum: Payment Number, Beginning Balance, Monthly Payment, Principal Portion, Interest Portion, and Ending Balance. You start with the loan amount in the first Beginning Balance cell. The Ending Balance of one row becomes the Beginning Balance of the next. That's the mechanical part. The formula work comes in figuring out the monthly payment itself and then splitting it between principal and interest. For the monthly payment, use the PMT function. It looks like this: =PMT(rate/12, nper, -loan_amount). The rate is your annual interest rate, nper is the total number of payments, and the loan amount needs the negative sign so the result comes out positive. If your rate is 6.5%, you enter 0.065/12. For a 30-year loan, nper is 360. This gives you the total monthly payment before any escrow is added. To split that payment, the interest portion is simply the beginning balance multiplied by the monthly rate: =B2*(rate/12). The principal portion is the payment minus the interest: =C2-D2. The ending balance is the beginning balance minus the principal portion: =B2-E2. Drag those formulas down for however many months you're amortizing. That's the skeleton of the worksheet.
Where people get tripped up is when they try to handle extra payments or biweekly options without restructuring the sheet properly. I built one for a client who was comparing biweekly payments against monthly, and the spreadsheet gave wildly wrong results because I hadn't adjusted the nper and rate inputs correctly for the biweekly frequency. The fix was straightforward once I caught it: biweekly means 26 payments per year, which equals 13 full monthly payments, not 26 half-payments that don't align with the loan's compounding structure. You have to model it as 26 payments of half the monthly amount but recalculate the total term accordingly. Another thing worth getting right from the start is the year-to-date summary section. Lenders care about how much interest you paid in a given tax year, and tracking that row by row gets tedious quickly. I add a small block that sums the interest column for each calendar year automatically. Use SUMIFS with a condition on the payment date or payment number range mapped to years. It cuts down the time I spend building these from about an hour to roughly twenty minutes for a standard residential loan. Here's a realistic edge case that cost me a few extra hours on a revision: a client had an adjustable-rate mortgage with caps and an initial fixed period. The standard amortization template didn't account for the rate adjustment at year seven. My workaround was to split the schedule into two sections with a hard reset at the adjustment point. The first section ran exactly like a normal fixed-rate schedule. At the adjustment row, I recalculated the new payment using PMT with the remaining balance, the new rate, and the remaining term. It's a manual step but it's reliable, and you avoid the common mistake of trying to force a single formula to handle rate changes, which usually breaks the sheet.
Get the Full Details
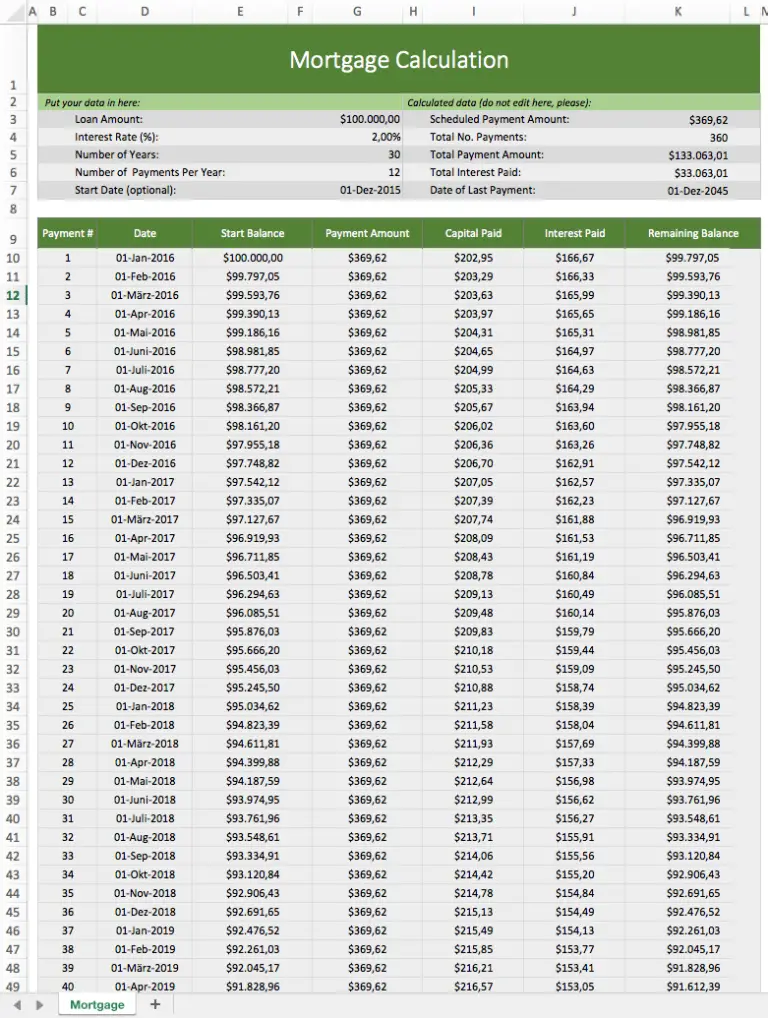
For the download, most people don't need anything fancy. If you want a ready-made file, searching for "mortgage amortization schedule template" on Microsoft's template gallery or even the Excel community forums will pull up something functional. I usually start from one of those and strip out the unnecessary bells and whistles because the default templates tend to overcomplicate things with conditional formatting and charts that nobody touches. What matters is the math, not the colors. A counter-intuitive detail that most people miss: the order in which you set up your cells matters more than the formulas themselves. If you put the loan parameters at the top in a clean block, changing one value recalculates everything instantly. If you hardcode values into the formulas, you're going to spend way more time updating individual cells. I keep Rate, Term, Loan Amount, and Escrow in one section at the top and reference them throughout. A change takes three seconds instead of three minutes. Another nuance: Excel's PMT function assumes payments are made at the end of each period. If your loan has payments due at the beginning, you need to set the type argument to 1. Most mortgages are end-of-period, but if you're working with a private loan or a lease that works differently, skipping this will shift every payment by a month and throw off the entire schedule. It's a small setting and a common oversight.
There are also limitations to be aware of. A Mortgage Worksheet Excel can't accurately model loans with variable fees, lender credits that fluctuate, or prepayment penalties that change over time without significant manual intervention. If you're dealing with a complex commercial loan or a balloon payment structure, the basic template falls apart quickly. In those cases, I'd recommend building in a separate payments tab that handles each payment event individually rather than relying on automated formulas, or switching to a dedicated mortgage calculation tool that supports those features natively. For most residential refinance or purchase scenarios, though, a well-built worksheet covers everything you need. It gives you visibility into the actual payoff timeline, shows the impact of extra principal payments, and generates a schedule you can hand to an accountant without spending hours formatting it. That's the practical value of getting it right the first time.