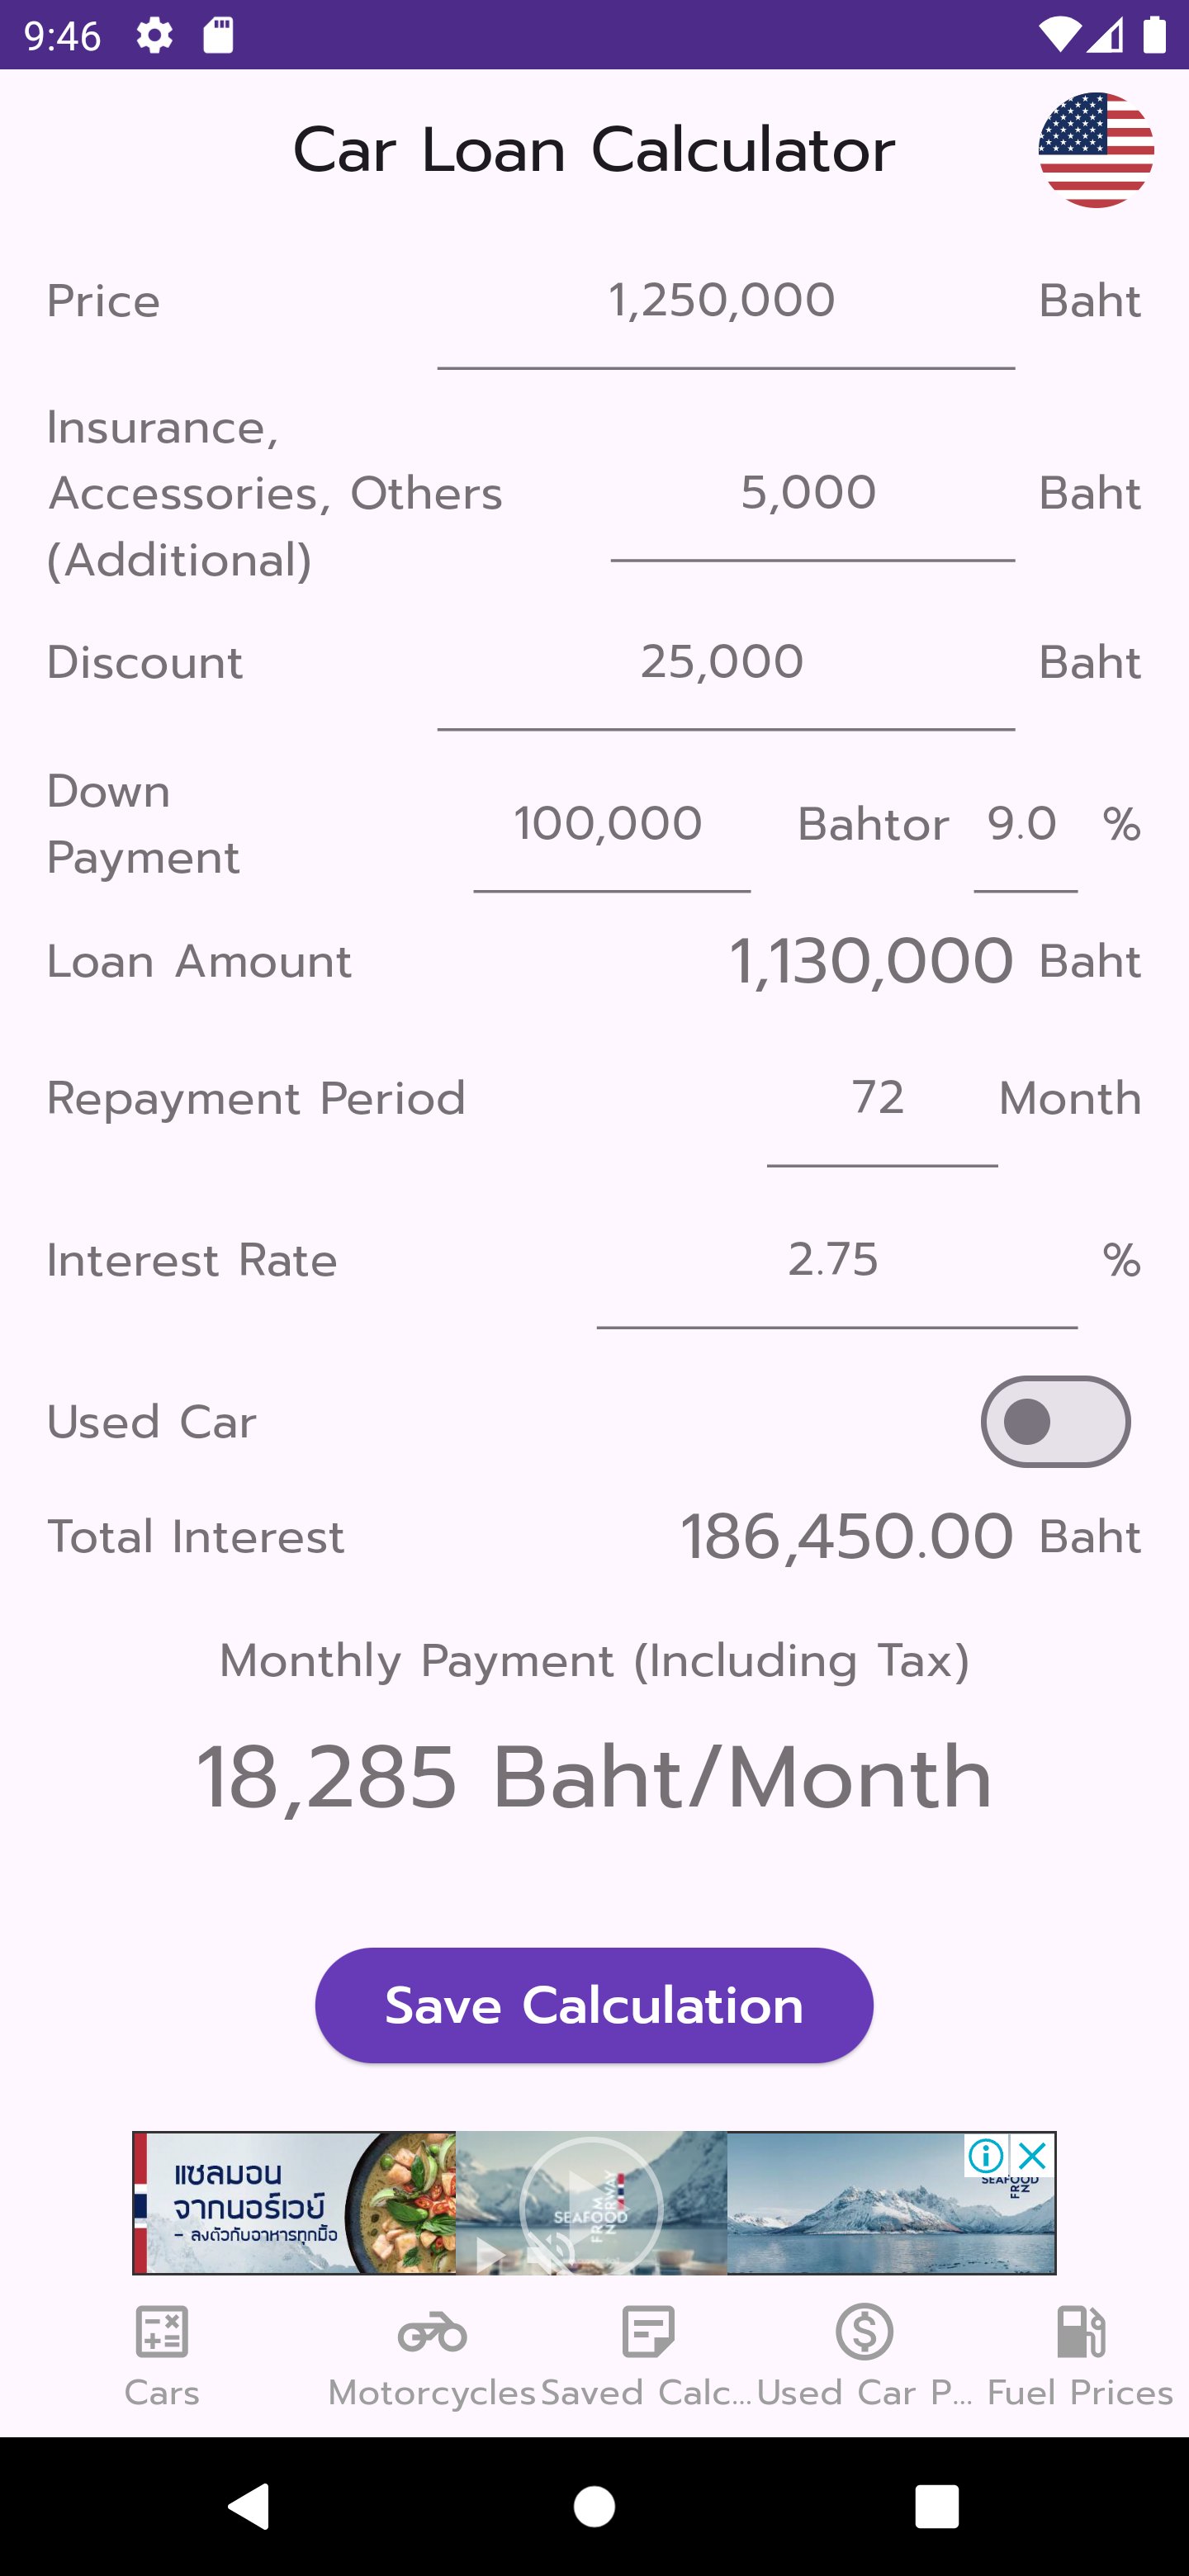
Most people think a motorcycle loan calculator is just an online form where you plug in numbers and get a payment. It is, but the real utility is in the reverse calculation. You know your budget ceiling — say $250 a month — and you need to figure out what price motorcycle you can actually afford after factoring in the down payment, interest rate, and loan term. That is the hard direction, and it is also where most calculators fall apart because they only do forward math.
I have seen more riders blow their budget because they looked at the monthly payment without accounting for the total cost of the loan. You put $2,000 down on a $10,000 bike, the calculator says $178 a month, and you feel great. Then you realize over five years you paid $3,466 in interest on top of the down payment and principal. The calculator does not always flag that. You have to.
Using a Motorcycle Loan Calculator With Down Payment Effectively
The basic formula is straightforward enough that you can verify any result yourself. Take the loan amount, subtract the down payment, divide by the number of months, then add the monthly interest portion. Most calculators use the standard amortization formula, which means your early payments are mostly interest and your later payments shift toward principal. This matters more than people realize because if you plan to sell the bike or pay off the loan early, you need to understand where you sit in that curve.
Here is a practical example from my own work. A rider came to me last year with a $7,500 sportbike, $1,500 down, and a quote of 8.9% APR over 48 months. The dealer's spreadsheet showed $157 per month. The rider was happy with that. I ran it through an independent Motorcycle Loan Calculator With Down Payment tool and got the same number, but I also pulled the total interest column. Over 48 months at that rate, the total interest came to $1,536. The rider had no idea. We restructured to a 36-month term at the same rate, which pushed the payment to $197 but cut total interest to $1,192. That is a $344 difference for paying $40 more per month. The calculator makes this visible if you look at the full output, not just the payment line.
One thing most people miss is how dealer-added products skew the calculation. Window stickers, extended warranties, tire and brake protection — these get rolled into the loan amount without being obvious. I had a situation where a customer was quoted a payment based on a $12,000 bike but the actual financed amount was $13,400 because the dealer wrapped in $900 of accessories and a $200 documentation fee. The down payment looked healthy, but the loan amount was inflated. Always verify the actual financed amount, not just the sticker price minus down payment.
Another edge case that caught me once involved a trade-in valuation. A rider brought a older bike to trade, the dealer appraised it at $1,800, and applied it as part of the down payment. The calculator accepted it, but the trade value never showed up in the financing paperwork. The lender only saw the cash down. The rider lost the benefit of that appraisal on paper. I learned to confirm that trade values are actually credited to the loan balance before finalizing anything. Write it down, get it in writing, then run the numbers.
Pitfalls and Where Calculators Fail
Not every calculator handles every scenario. Some do not account for sales tax in the down payment calculation. Others assume the down payment is a flat percentage when in reality it is a fixed dollar amount. A few tools ignore prepayment penalties entirely, which matters if you are looking at a subprime loan from a buy-here-pay-here dealership. Those loans often have stiff early payoff penalties that a standard calculator will not show.
There is also the issue of variable rates. If you are looking at a floating rate loan, any calculator gives you a snapshot, not a forecast. The payment could shift significantly depending on where rates go. I recommend treating any calculator result as a baseline for discussion with the lender, not as a commitment.
If you are working with a large down payment — say over 20% of the bike price — the calculator may not reflect the interest savings accurately because some lenders change their rate tiers based on loan-to-value ratios. A higher down payment can drop you into a lower APR bracket, and not all online tools factor that in. Check with the lender directly if your down payment is substantial.
For the most accurate results, pull your actual credit score range from a monitoring service before running the numbers. The rate you see advertised is rarely the rate you qualify for. I have had people run calculations at 5.9% only to be offered 11% at the dealership because their credit did not meet the promotional threshold. The calculator result was technically correct, but practically useless without the real rate.
How to Verify Any Calculator Output
Run the same numbers through two different sources. I use a free online amortization schedule generator alongside the dealer's quote. If the numbers differ by more than a few dollars, something is off — either the calculator is using a different compounding method, or the loan terms are not what they appear. Sometimes the difference is as simple as whether the calculator assumes 360-day years or 365-day years for interest accrual. It seems minor but it adds up over the life of the loan.
Check whether the calculator includes insurance and registration in its total cost display. Most do not, but those costs are real and they affect your monthly budget differently than a loan payment. Insurance on a new sportbike can run $80 to $150 a month depending on your age, location, and riding history. That is money that needs to exist alongside your payment, not inside it.
I also recommend printing or saving the full amortization table, not just the summary. The table shows you exactly how much principal you pay each month and when you start building equity. This is useful information if you ever need to refinance or sell before the loan is paid off. You can see your remaining balance at any point without guessing.
Gallery Motorcycle Loan Calculator With Down Payment
Motorcycle Loan Calculator – How Much Is Your Payment With Financing?
Motorcycle Loan Calculator 2025: Payment & Amortization
Motorcycle Loan Calculator - Estimate Payments | MyCarCalc
Motorcycle Loan Calculator - Estimate Monthly Payments
Car&Motorcycle Loan Calculator APK for Android Download