What You Actually Get When You Sell Something
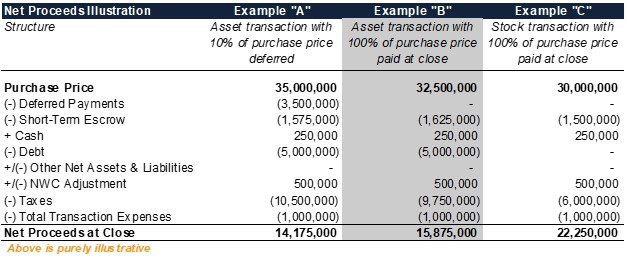
Net proceeds is the money that lands in your pocket after every fee, commission, tax, and chargeback gets stripped out of the gross sale price. People confuse it with gross revenue all the time, and it costs them money because they budget based on the wrong number. I learned this the hard way when pricing a used vehicle for a dealership client. The car sold for $18,500 at auction. The gross looked fine. But once I ran the buyer's premium at 8.5%, the seller's side administrative fee, the document transfer charge, the state sales tax remittance, and the payment processing holdback, the actual cash returned was $14,923. The broker had quoted the client a figure that was over $3,000 higher than what would actually clear. Nobody caught it until the check arrived. The concept itself is simple arithmetic, but the complexity comes from how many deduction layers exist between a sale price and a deposit. Different industries stack these differently. Real estate has agent commissions, closing costs, prorated taxes, HOA transfers, and title insurance. E-commerce has payment gateway fees, shipping subsidies, platform commissions, return losses, and advertising spend allocation. The calculation changes depending on where the transaction happens, but the principle stays the same: gross minus every associated cost equals net proceeds.
Calculating Net Proceeds in Practice
Start by identifying every single cost layer tied to the transaction. This is where most people fail because they only think about the obvious ones like commissions or fees and forget about the silent deductions. Chargebacks on merchant platforms can run 1.5 to 3 percent of volume during certain months. Shipping insurance gets baked into net calculations more often than sellers realize. Platform subscription fees should be allocated proportionally when you're calculating per-transaction net proceeds. Here's how I structure a clean calculation template. Step one: Write down the gross sale amount. This is the total dollars exchanged before any deductions. Step two: List every deduction as its own line item. Do not group them. Grouping hides errors. A typical line-by-line list looks like this: platform commission, payment processing fee, shipping cost, return reserve, advertising attribution, tax remittance, processing or service fee, and any penalties or holdbacks.
Step three: Convert percentages to dollar amounts using the gross as your base. If a platform takes 15 percent commission on a $500 sale, that is $75. If payment processing is 2.9 percent plus $0.30, calculate that separately. The flat fee applies per transaction, not per percentage. Step four: Subtract all deductions from the gross. The result is your net proceeds. I use a spreadsheet with color coding so deductions pull red and the final net pulls green. It sounds trivial, but when you're processing fifty transactions a week across three different platforms, color coding saves you from mixing up which commission rate applies to which marketplace. Amazon charges differently than eBay. Shopify charges differently than Etsy. One mistake in the formula and your net proceeds number is wrong by enough to matter at scale.
Get the Full Details

The Edge Case That Cost Me an Afternoon
Early in my career I handled a commercial lease assignment where the tenant claimed net proceeds of $42,000 after their broker fee and move-out restoration costs. I ran the numbers and agreed with the figure. Then I noticed the lease had a hidden clause about landlord administrative processing fees that triggered at assignment. The fee was structured as a flat $2,500 but only appeared on the addendum, not the main contract. I had missed it in my first pass because I was reading the lease linearly and stopped at page three when the financial terms seemed complete. I caught it when I cross-referenced the amendment schedule. The real net proceeded dropped to $39,500. The workaround I adopted after that was to always pull the full document package including addenda and rider schedules before running any net calculation. It added twenty minutes to the review but saved me from looking careless in front of the client. I still do that now on every deal, regardless of size. The biggest mistake I see repeatedly is double-counting deductions. People subtract the broker commission and then also subtract a marketing fee that is already baked into that commission structure. In some industries the listing fee is included in the agent cut. In others it is separate. You have to verify the contract language before treating anything as an additional line item. I spent a weekend recalculating a property sale because I had listed the photographer fee separately when it was already covered under the staging package the seller had purchased. That was about $600 sitting in no-man's-land for three days while I untangled it. Another frequent error is applying a flat percentage deduction to a gross that already includes tax. Sales tax collected is not your revenue. It belongs to the state. If you calculate net proceeds on a gross that includes remitted tax without stripping the tax out first, your deductions come out inflated and your net number drops artificially. The fix is to back out applicable taxes before applying any commission or fee percentage. Most invoices break this out clearly if you know where to look.
A less obvious problem is timing mismatch. Revenue might be recognized in one period while the deductions get paid in another. Marketplace platforms often hold funds for fourteen to thirty days. That holdback reduces your available net proceeds for the period you record the sale, even though the deduction technically leaves later. This matters for cash flow planning more than it matters for the final accounting number. I flag it explicitly in every report now because owners get anxious when they see money missing from their available balance even though the math is correct.
When Net Proceeds Calculations Break Down Completely
Manual spreadsheets stop working reliably once you cross about twenty transactions per week. The error rate climbs, the formulas drift, and reconciliation takes longer than the calculation itself. At that point you need transaction-level software that pulls directly from your payment processor and marketplace dashboards. I switched one of my clients from Excel to a tool called Ramp from Ramp.com when their monthly volume hit roughly eighteen sales across four different channels. The migration took about four hours. Monthly reconciliation that used to take six hours now takes forty minutes. The system auto-fetches the fee schedules and applies them correctly, which eliminates the double-counting issue I described above because it reads the actual invoice rather than a percentage you type in manually. The downside is that not every platform integrates cleanly. Some marketplaces still require manual exports and CSV imports, which reintroduces the risk of human error. The integration gap usually shows up with newer or regional platforms that lack an official API. In those cases the hybrid approach works best: automated tracking for your primary channels and a disciplined manual template for the rest. The manual template should include mandatory fields for deduction source so you can audit each entry instead of guessing what went into a rounded number.

Industry-Specific Variations You Should Know About
Real estate net proceeds calculations are the most heavily scrutinized because the dollar amounts are large and the deductions are numerous. Closing costs alone can range from 1 to 3 percent of the sale price depending on the county. Transfer taxes vary by municipality and sometimes by property type. Home warranty plans, inspection credits, and repair allowances all reduce net proceeds and are easy to forget if you are relying on memory instead of a checklist. I keep a standard deduction matrix for residential transactions that I run through for every deal. It catches things like municipal stormwater fees and school district transfer charges that most sellers have never heard of until they see the line on the settlement statement. E-commerce net proceeds look cleaner on the surface but carry hidden erosion from returns and ad spend. A product might sell for $60 with a 30 percent margin on paper, but if the return rate is 12 percent and customer acquisition cost is $8 per sale, the true net proceeds per unit drop well below the initial estimate. Retailers who ignore return reserves in their net calculation end up overpromising profitability to investors or partners. The adjustment here is to treat returns as a standard deduction line item with a rolling twelve-month average rate rather than a one-time guess. Freelance and service-based work has its own distortion. Platform fees on freelance marketplaces range from 5 to 20 percent depending on the service tier and payment method. Invoice payment processing through Stripe or PayPal adds another 2.9 to 3.5 percent. When clients ask what their net proceeds will be from a $1,000 project, I always run both the platform cut and the processing cut before answering. The difference between quoting gross and quoting net is usually about $150 to $200, and that gap is where trust breaks down if you are not transparent about it upfront.
A Practical Net Proceeds Example
Here is a straightforward example using an e-commerce sale so you can see the full stack. A product sells for $120. The platform commission is 15 percent, which is $18. Payment processing is 2.9 percent plus $0.30, which comes to $3.78. Shipping runs $8.50 flat. The product return reserve is estimated at 5 percent of gross, which is $6. Advertising attribution for this sale is $7.20. Sales tax of $9.60 is collected but remitted to the state, so it does not count as revenue and must be removed before calculating percentages. Gross revenue before deductions is $110.40 after stripping tax. Total deductions equal $43.48. Net proceeds equal $66.92. The effective deduction rate is 36.2 percent of the original sale price. Many sellers walk away thinking they made $102 after fees and are confused when the bank deposit is noticeably lower. The lesson from that example is that the deduction rate is rarely a single number you can memorize. It shifts every time your platform changes its fee schedule or your return rate fluctuates. I update my deduction assumptions quarterly rather than setting them once and forgetting them. The spreadsheet method works fine for low volume, but if you want this number to stay accurate over time you need a living document rather than a static calculation.
Tools That Make This Easier
Ramp from Ramp.com handles transaction-level net proceeds tracking automatically for most major e-commerce and payment channels. It pulls sales data, maps the associated fees, and produces a clean net proceeds report with exportable detail. I recommend it for anyone processing more than fifteen transactions per month manually. For lower volume, a well-built spreadsheet with mandatory deduction fields and a rolling average table for variable rates like returns and ads is sufficient and avoids subscription costs. The one situation where neither approach works well is cross-border transactions with multi-currency fees, customs duties, and currency conversion loss. The deduction stack expands so much that standard tools lose accuracy. In those cases I fall back to a per-transaction manual log with a currency conversion column using the actual rate on the settlement date, not the mid-market rate from the day of sale. The difference can be several percent over a year, and that gap shows up directly in your net proceeds line.
Bottom Line Without the Fluff
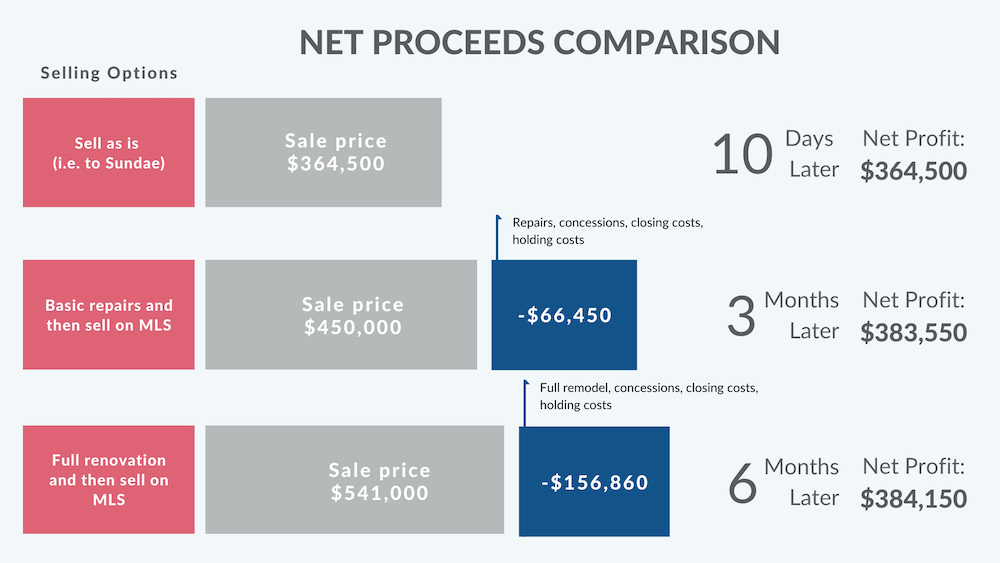
Net proceeds is not a glamorous number but it is the only one that determines whether a transaction actually made money. Gross revenue feels good on a dashboard. Net proceeds keeps the lights on. Calculate every deduction separately, back out taxes before applying percentages, and treat your calculation as a living document that updates when fees or rates change. The afternoon I lost chasing a hidden landlord processing fee taught me that attention to document structure matters just as much as the arithmetic. If you build the habit of checking addenda first and running deductions line by line instead of as a lump sum, your net proceeds numbers will stay honest and your decisions will be based on actual cash rather than optimistic estimates.