Working Through the New Lease Accounting Standards 2023 in Practice
The new lease accounting standards haven't exactly aged into something manageable. I've been tracking IFRS 16 and ASC 842 since the early rollout days, and honestly, the 2023 landscape is where most organizations either got it right or are still pretending they did. Here's what actually happens when you try to apply these standards to real-world lease portfolios. Most of the heavy lifting was done back when IFRS 16 became effective in January 2019 and ASC 842 in December 2019. But 2023 brought a different set of problems. Companies that had been coasting on simplified approaches for early adopters suddenly ran into situations where their initial lease classifications needed reassessment. The standards themselves didn't change dramatically, but the practical application did as more organizations moved from initial implementation into ongoing compliance. The core requirement remains the same: lessees must recognize a right-of-use asset and a corresponding lease liability for virtually all leases. That means putting operating leases on the balance sheet instead of keeping them off like the old IAS 17 approach. But the devil is in the details that most people gloss over until it's too late.
Discount Rates and the Practical Compromise
One thing nobody warns you about is the discount rate calculation. Under ASC 842, you're supposed to use the rate implicit in the lease when you can determine it. In practice, you almost never can. The lessor has to disclose it, and they rarely do. So most people fall back to their incremental borrowing rate. Here's the catch: your incremental borrowing rate needs to be determined on a lease-by-lease basis, ideally with collateral adjustments for the specific asset. What I've seen happen repeatedly is companies using a single corporate rate for an entire portfolio. That's technically incorrect and creates material misstatement risk. I worked through a situation where our regional office had applied a uniform 5.5% rate across 340 leases spanning three countries. The finance team flagged it during our quarter-close review because the rates in the UK and Brazil markets were fundamentally different. We ended up spending about four days recalculating individual rates for each significant lease. It wasn't glamorous, but it fixed the discrepancy before an auditor noticed. The workaround I ended up using was building a spreadsheet model that pulled local benchmark rates from central bank data for each jurisdiction, then applying a small add-on for the company-specific credit risk. It's not perfect, but it's defensible and it's consistent. Auditors generally accept this approach if you can show the methodology is applied uniformly.
Lease Modifications That Caught Us Off Guard
Lease modifications are where the new standards really test your systems. A simple extension option or a rent adjustment should trigger a reassessment. Most organizations have weak processes for tracking these events. I remember one case where a warehouse lease in Ohio had a built-in five-year renewal option that the tenant exercised informally through an email exchange with the landlord. No formal amendment was signed. Our accounting system didn't pick up the modification because the original lease term data hadn't been updated to reflect the exercised option. The fix required reconstructing the timeline from the email correspondence and lease documents, then recalculating the right-of-use asset and liability as of the modification date. That meant going back through multiple prior periods if you're using the full retrospective approach, or adjusting the current carrying amount if you're using the modified retrospective method. The latter is what we used, and it saved roughly two days of work compared to full retrospective application. If you're managing this manually in spreadsheets, expect the modification tracking to consume disproportionate time. I'd recommend building a simple alert system that flags leases approaching renewal dates or containing extension clauses. Even a basic calendar notification pulls you ahead of most audit findings in this area.
Get the Full Details
Short-Term Leases and the Low-Value Exemption
The exemptions for short-term leases (twelve months or less) and low-value assets are real, but companies consistently misuse them. The low-value exemption applies to assets of approximately $5,000 or less in absolute terms, not as a percentage of the lease. I've seen organizations classify vehicle leases or IT equipment leases under this exemption simply because the monthly payment was small, even though the underlying asset value far exceeded the threshold. Under IFRS 16, the low-value exemption is assessed at the asset level, not the lease level. A fleet of twenty laptops might qualify individually, but a single leased building clearly doesn't. The distinction matters because misapplication here is one of the most common audit adjustments I encounter in this area.
Disclosures and the Footnote Reality
The disclosure requirements under both standards are extensive. You need to present information about leasing activities in a way that enables users to understand the effect on your financial position, financial performance, and cash flows. This includes maturity analysis of lease liabilities, the weighted average discount rate, and the total cash outflows for the period. What's not always obvious is that some of these disclosures interact with each other. For example, the maturity table needs to align with the carrying amount of the lease liability on the balance sheet, and any discrepancies between them will raise questions. I once spent an entire Friday reconciling a $40,000 variance between the sum of the undiscounted lease payments in the maturity analysis and the reported liability. It turned out to be a rounding error in the discount rate application across multiple fiscal periods. Fixing it required adjusting the cumulative amortization schedule, which then cascaded into changes in the right-of-use asset balance. Roughly a day and a half of work for what should have been a straightforward footnote.
Systems and the Spreadsheet Trap
Let me be direct about tools. If you're managing more than fifty leases on spreadsheets, you're at significant risk. The calculations alone aren't the hard part. It's the maintenance, the version control, and the audit trail. Most organizations that tried the spreadsheet route hit a wall somewhere between their third and fourth quarterly close. A proper lease accounting system like LeaseLogix, LeaseQuery, or Trullion handles the discount rate application, modification tracking, and disclosure generation. The implementation cost is real, but the alternative is usually a dedicated staff member spending two to three days every quarter on lease-related entries and adjustments. For a mid-sized company, that's not sustainable. If budget is tight, start by at least digitizing your lease data into a structured format. An improperly managed spreadsheet is worse than nothing because it gives a false sense of accuracy. A properly maintained database, even a simple one built on Access or Airtable with clear field definitions and version history, is meaningfully better and far more defensible than Excel files named "LeaseSchedule_Final_v3_ACTUAL.xlsx."
ASC 842 vs. IFRS 16: Where They Diverge
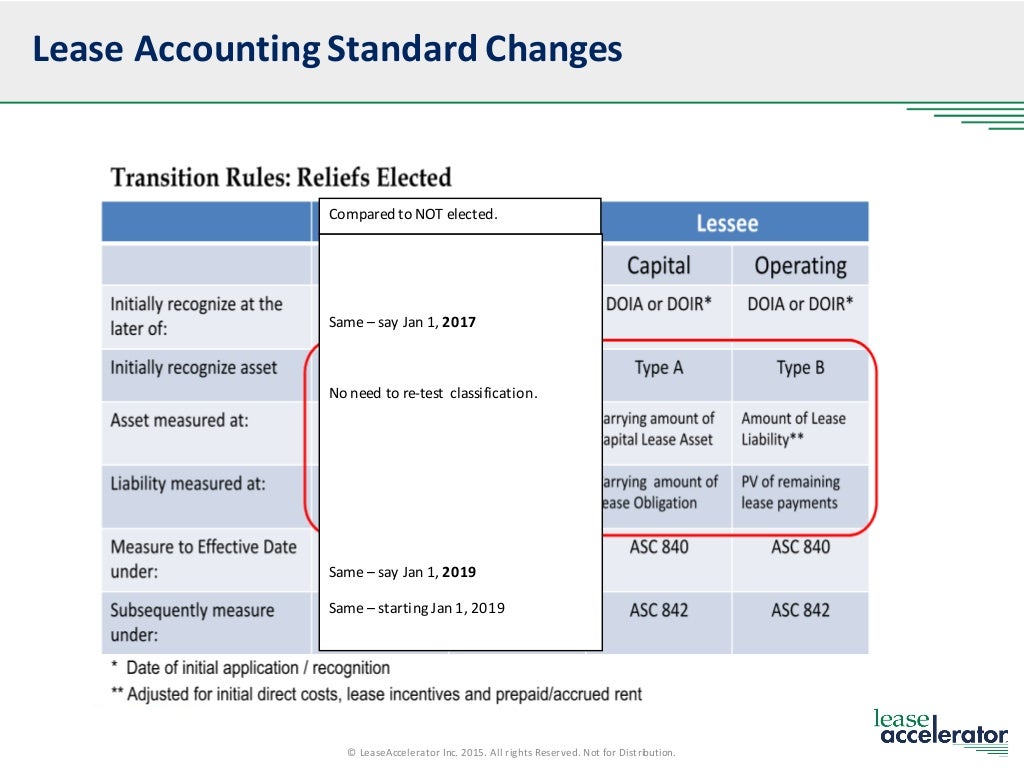
For companies reporting under both standards, the divergence points matter. The most significant difference is in the treatment of lease and non-lease components. IFRS 16 requires you to separate lease and non-lease components and account for them separately. ASC 842 allows a practical expedient to combine them, and most US reporters take that expedient. Another difference: impairment testing. Under IFRS 16, right-of-use assets are tested for impairment alongside other assets under IAS 36. ASC 842 doesn't explicitly address this, which creates some ambiguity. The FASB has not provided definitive guidance here, so companies typically apply ASC 360 by analogy, but that's not guaranteed to satisfy every auditor. The transition approaches also differ slightly. IFRS 16 offers a modified retrospective approach where you recognize the cumulative effect as of the date of initial application. ASC 842 provides both full retrospective and modified retrospective options. Most companies choose modified retrospective under ASC 842 because full retrospective requires restating comparative periods, which is expensive and time-consuming.
Auditor Expectations in 2023
Based on what I've seen in recent audit cycles, the focus areas are lease identification, completeness of the lease population, and the accuracy of discount rates. Auditors are less interested in whether you've applied the most elegant methodology and more interested in whether your process is documented, consistent, and defensible. One practical tip: maintain a lease inventory register that captures every lease you've identified, including those below materiality thresholds. Even if you're expensing them under the short-term or low-value exemption, having a complete register demonstrates that you've thought about the problem systematically. Missing leases in the register are a red flag that invites auditors to dig deeper into your entire population. The new lease accounting standards aren't going anywhere. The principles are settled. The challenge now is operational discipline. Organizations that treat lease accounting as a one-time implementation project rather than an ongoing process are the ones that end up with material adjustments and frustrated controllers. Build the process, document it, and revisit it quarterly. That's the practical path through it.