Filing New Mexico State Income Tax Actually Makes Sense Once You Get Past the Paperwork
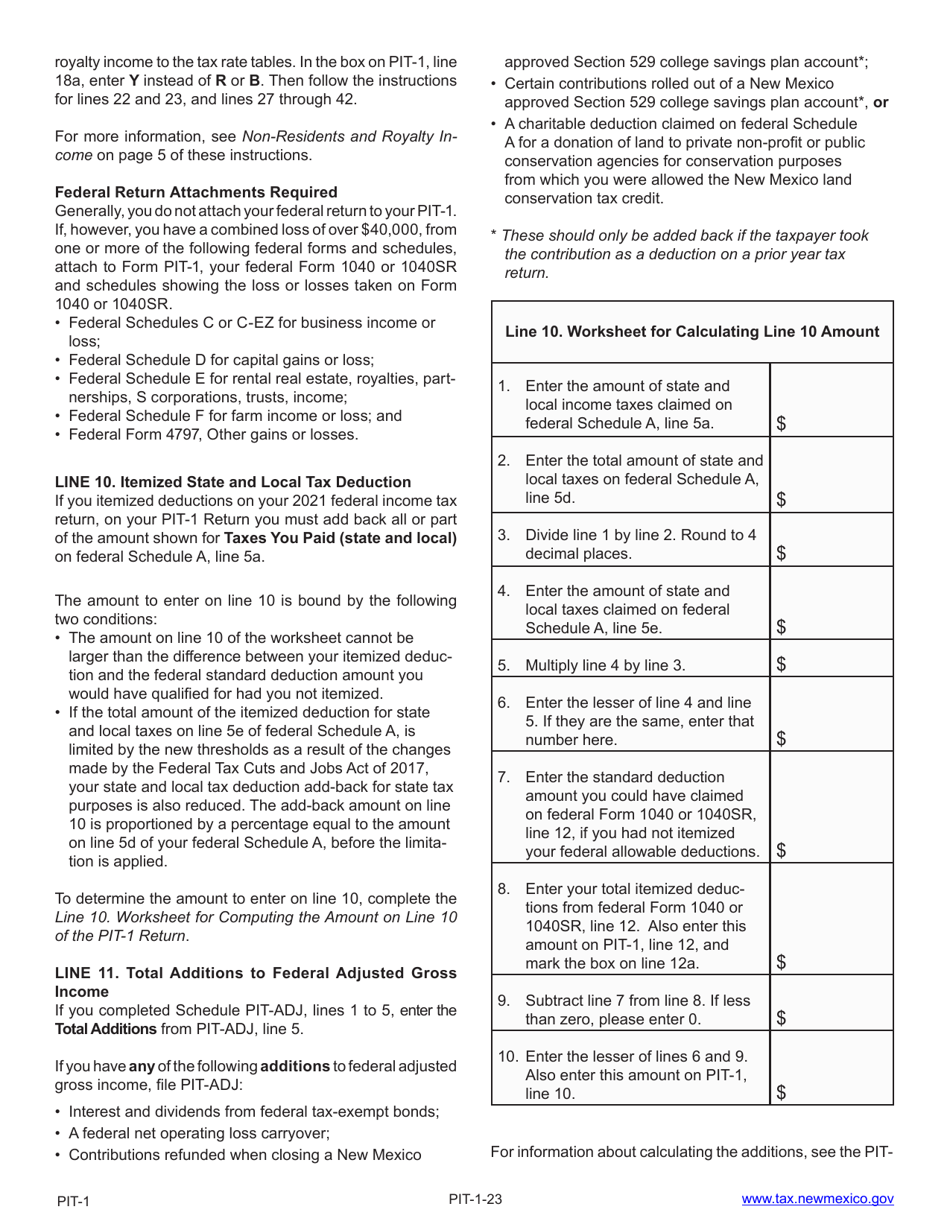
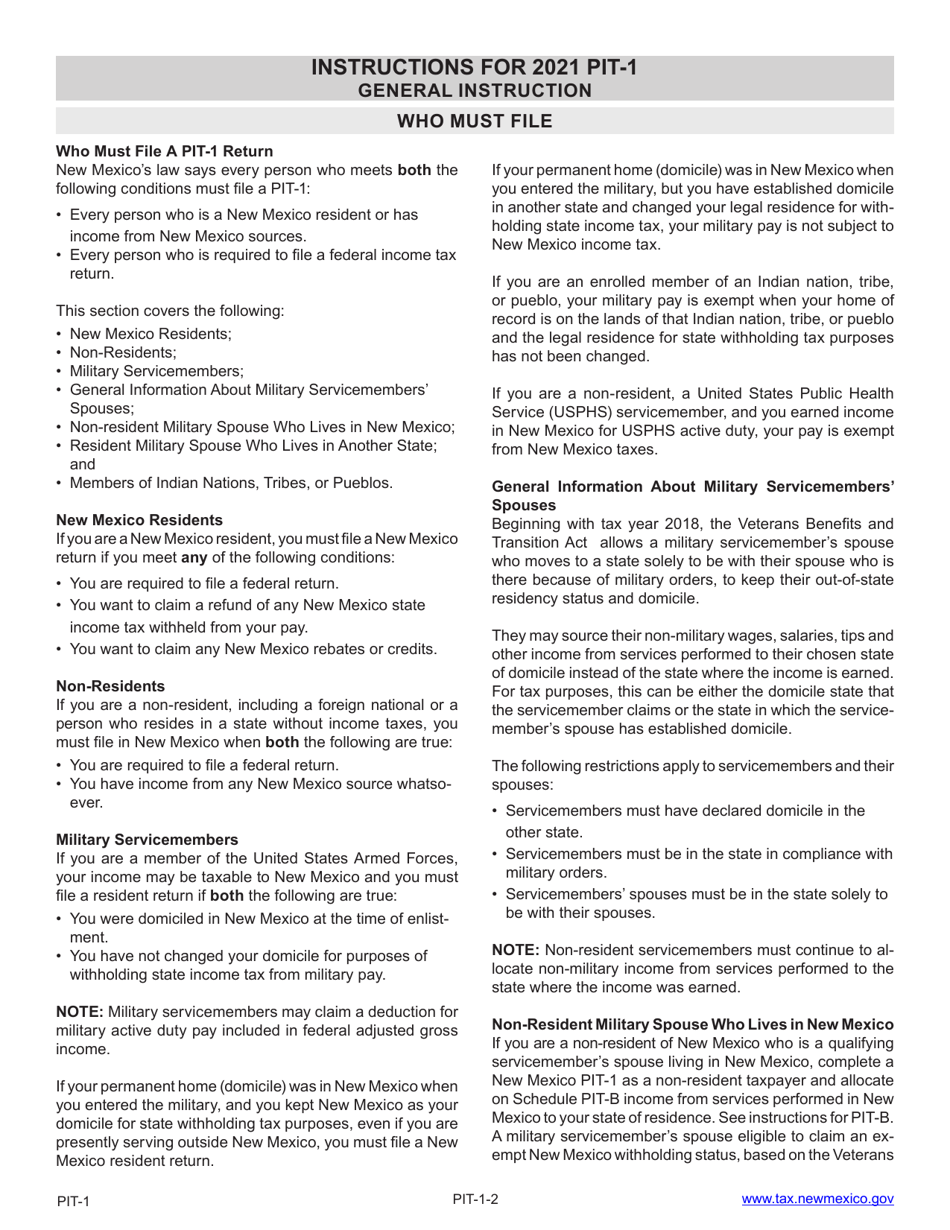
New Mexico operates as a filing state that largely mirrors your federal return but doesn't automatically accept everything you send to the IRS. You need to file Form PD-1 if your gross income exceeds the standard deduction thresholds, which for 2024 are roughly $14,650 for single filers and $29,300 for married couples filing jointly. Those numbers shift slightly each year. The filing deadline lines up with the federal date, so April 15th is your baseline unless you request an extension. The first thing you need is your federal return in hand. New Mexico starts with your adjusted gross income from line 11 of your 2024 Form 1040 and then applies state-specific adjustments on Schedule M. Most deductions flow directly from your federal return, but there are a handful of items that trip people up repeatedly. Interest income from U.S. Treasury securities gets subtracted out because New Mexico doesn't tax federal obligations. Municipal bond interest from other states may or may not be deductible depending on whether the bond was issued in New Mexico. This is where I learned to stop assuming reciprocity works the way I thought it did. Here's the edge case I ran into last year that nearly cost me two hours of headache. I had a W-2 from a employer headquartered in New Mexico but I physically worked in Colorado for about six months. My employer withheld New Mexico tax the entire year because of where the payroll office was located. Colorado also withheld taxes. New Mexico Personal Income Tax Instructions don't explicitly call out this scenario in any prominent place. The workaround is straightforward once you know it: file a Colorado nonresident return first to establish the taxes paid there, then claim a credit for those taxes on your New Mexico return using Form PIT-R. Without that credit you'd end up paying double. I learned this the hard way after my first attempt flagged an underpayment and I spent an evening on the PNM website trying to figure out why my refund was suddenly smaller than expected.
Itemized deductions on your federal return carry over directly to New Mexico unless you took the standard deduction federally, in which case New Mexico also uses the standard deduction. You cannot itemize on one and take the standard on the other. The standard deduction amounts track closely to the federal brackets but they are not identical. For 2024 the New Mexico standard deduction for single filers is $14,650, matching the federal amount, but for head of household the state breaks away at $21,900 versus the federal $21,900 which actually aligns this particular year. The numbers drift in other years so always check the current filing year's schedule. One counter-intuitive thing about New Mexico that nobody warns you about: the state does not conform to the federal SALT deduction cap the way most people expect. If you itemize and your state and local tax deduction got capped at $10,000 on your federal return, New Mexico recalculates that deduction without the federal limitation. That means your New Mexico taxable income could actually be higher than your federal taxable income in cases where the SALT cap bit you. This reversal caught a lot of my clients off guard in 2023 when the cap was still very much in effect. The adjustment shows up on Schedule M line 11. New Mexico also offers a few credits that are worth knowing about regardless of how ordinary your situation seems. The Homestead Exemption can reduce your taxable income by up to $4,000 if you own and occupy your home as your primary residence and meet the income limits. You file a separate Homestead Claim form rather than handling this on your main return. The working Families Tax Credit mirrors a portion of the federal EITC and is fully refundable. If you qualified for the federal Earned Income Credit you almost certainly qualify for the state version, and the math is simple because New Mexico applies a fixed percentage to your federal credit amount.
The pension exclusion is another one people overlook. New Mexico allows you to exclude up to $8,000 per person of pension and retirement income if you were born before January 2, 1963. If you and your spouse both qualify that is a potential $16,000 reduction in taxable income. The age cutoff matters more than the birthdate wording suggests. If your spouse turns 62 during the tax year they still do not qualify until the following year. This is a hard rule, not a gray area, and the forms will reject filings that misstate the date.
Get the Full Details
How to File and Where to Find the Forms
You can file electronically through the New Mexico Taxation and Revenue Department's website or use third-party tax software that supports e-filing for New Mexico. Paper filings are accepted but mail delivery adds roughly three weeks to the processing time compared to electronic submission. If you are requesting a refund e-filing with direct deposit is the fastest route and typically lands in your account within three weeks. Paper refund checks can take eight to twelve weeks to arrive. For free filing assistance, New Mexico offers a volunteer tax help program through the Low Income Taxpayer Clinic network. If your adjusted gross income falls below roughly $79,000 you may qualify for free in-person help at designated sites across the state during tax season. This is not the same as the VITA program run by the IRS though they sometimes operate out of the same locations. The state-run sites handle New Mexico specific questions that federal volunteers might not be set up to answer. The official forms and instructions are available at the New Mexico Taxation and Revenue Department website. Look for the Individual Income Tax section and you will find the PD-1 packet which includes the main form, Schedule M for adjustments, Schedule 1 for additional credits and deductions, and the Homestead Claim form. Download the version labeled for the current tax year because the old versions carry over into the next filing season and cause reconciliation problems when the department's systems auto-match against the wrong year's figures.
Extension filings are straightforward. Form PD-1A gives you six additional months beyond the April deadline. An extension to file is not an extension to pay. If you owe taxes you should still pay by April 15th to avoid interest charges. The interest rate on underpayments is set annually by the department and has hovered around 6 percent over the past several years. Penalties for failure to pay are steeper at roughly half a percent per month, so paying what you owe on time matters more than filing by the extension date.
Pitfalls and Where the System Falls Short
New Mexico's online filing system is functional but not intuitive. The e-file portal does not always validate field entries the way commercial tax software does, which means you can submit a return with calculation errors that go unnoticed until you receive a notice months later. I have seen taxpayers get penalty letters for miscalculated homestead exemptions because the portal accepted the form with an obviously wrong number in a field that should have been auto-populated from their income data. The department's customer service response times are unpredictable. During peak season you might wait on hold for forty-five minutes or more. Email support exists but responses can take up to ten business days. The most efficient path for urgent questions is the toll-free number listed on the PD-1 instruction sheet, and even then calling early in the morning on a weekday gives you better odds of reaching a live person before the queue builds up. New Mexico does not have a state-level Roth IRA conversion tracking system, which means if you converted a traditional IRA to a Roth in a given year you need to handle that reporting yourself on the state return rather than relying on an automated adjustment. The federal Form 8606 carries over but the state does not auto-import it. You enter the conversion amount manually on Schedule 1 and attach a copy of Form 8606 if requested during audit. This is a small detail that causes issues for people who convert IRA accounts every few years.
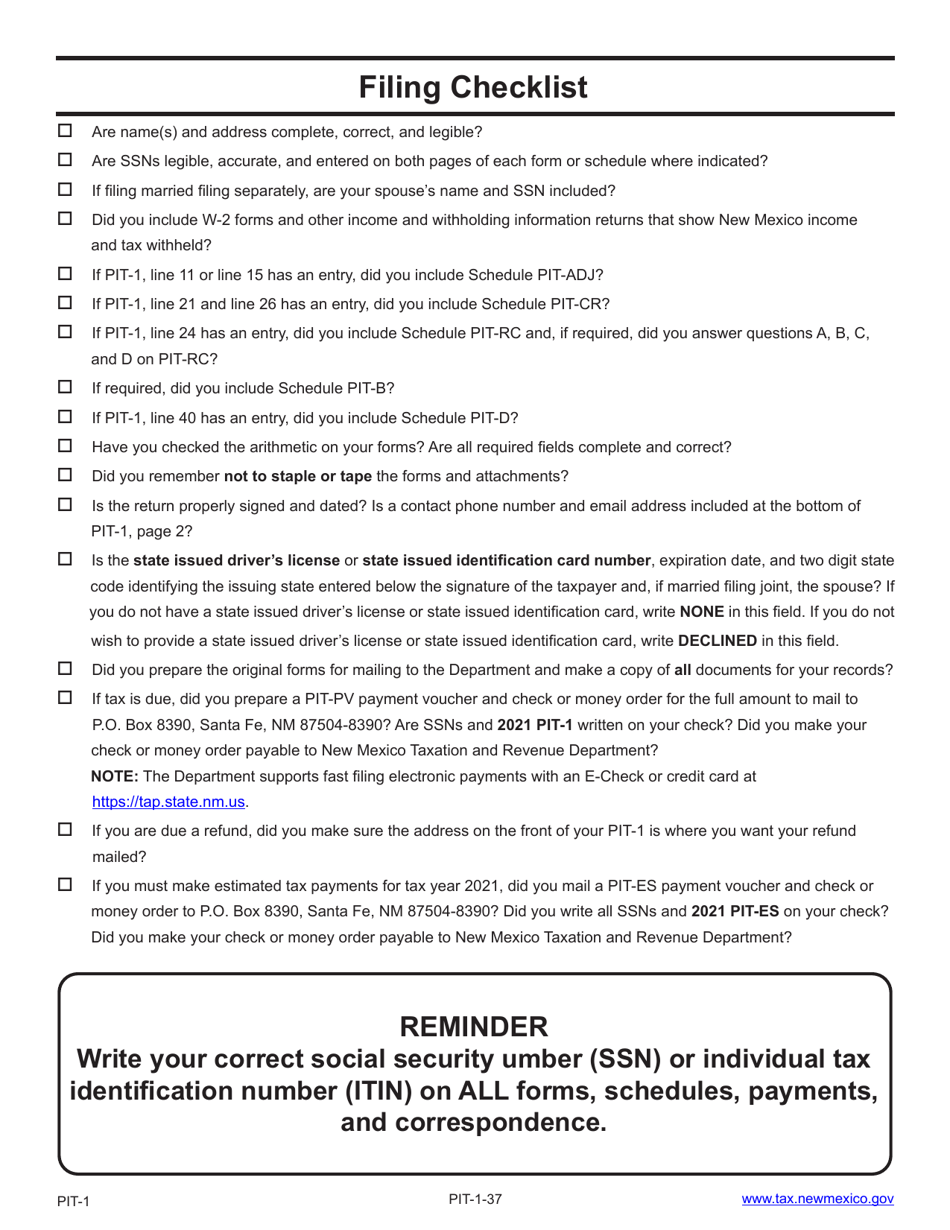
For high-income earners there is another quirk worth noting. New Mexico does not have a separate alternative minimum tax, but the interaction between federal AMT adjustments and the state's add-back requirements can produce unexpected taxable income increases. If you have large depreciation deductions or incentive stock option exercises on your federal return, running through the Schedule M lines carefully before filing can save you from a surprise balance due. The math is not inherently complex but the form layout makes it easy to miss the correct line entry. The bottom line is that New Mexico taxation and revenue follows familiar patterns if you file a standard W-2 return with no complications. The moment you introduce multi-state work, retirement income, or significant itemized deductions the state-specific rules diverge enough from federal treatment that manual review becomes necessary. Budget extra time for that situation and do not assume the e-filing system will catch every inconsistency before submission.