How to Actually Use the Ngpf Compare Auto Loans Answer Key Without Losing Your Mind
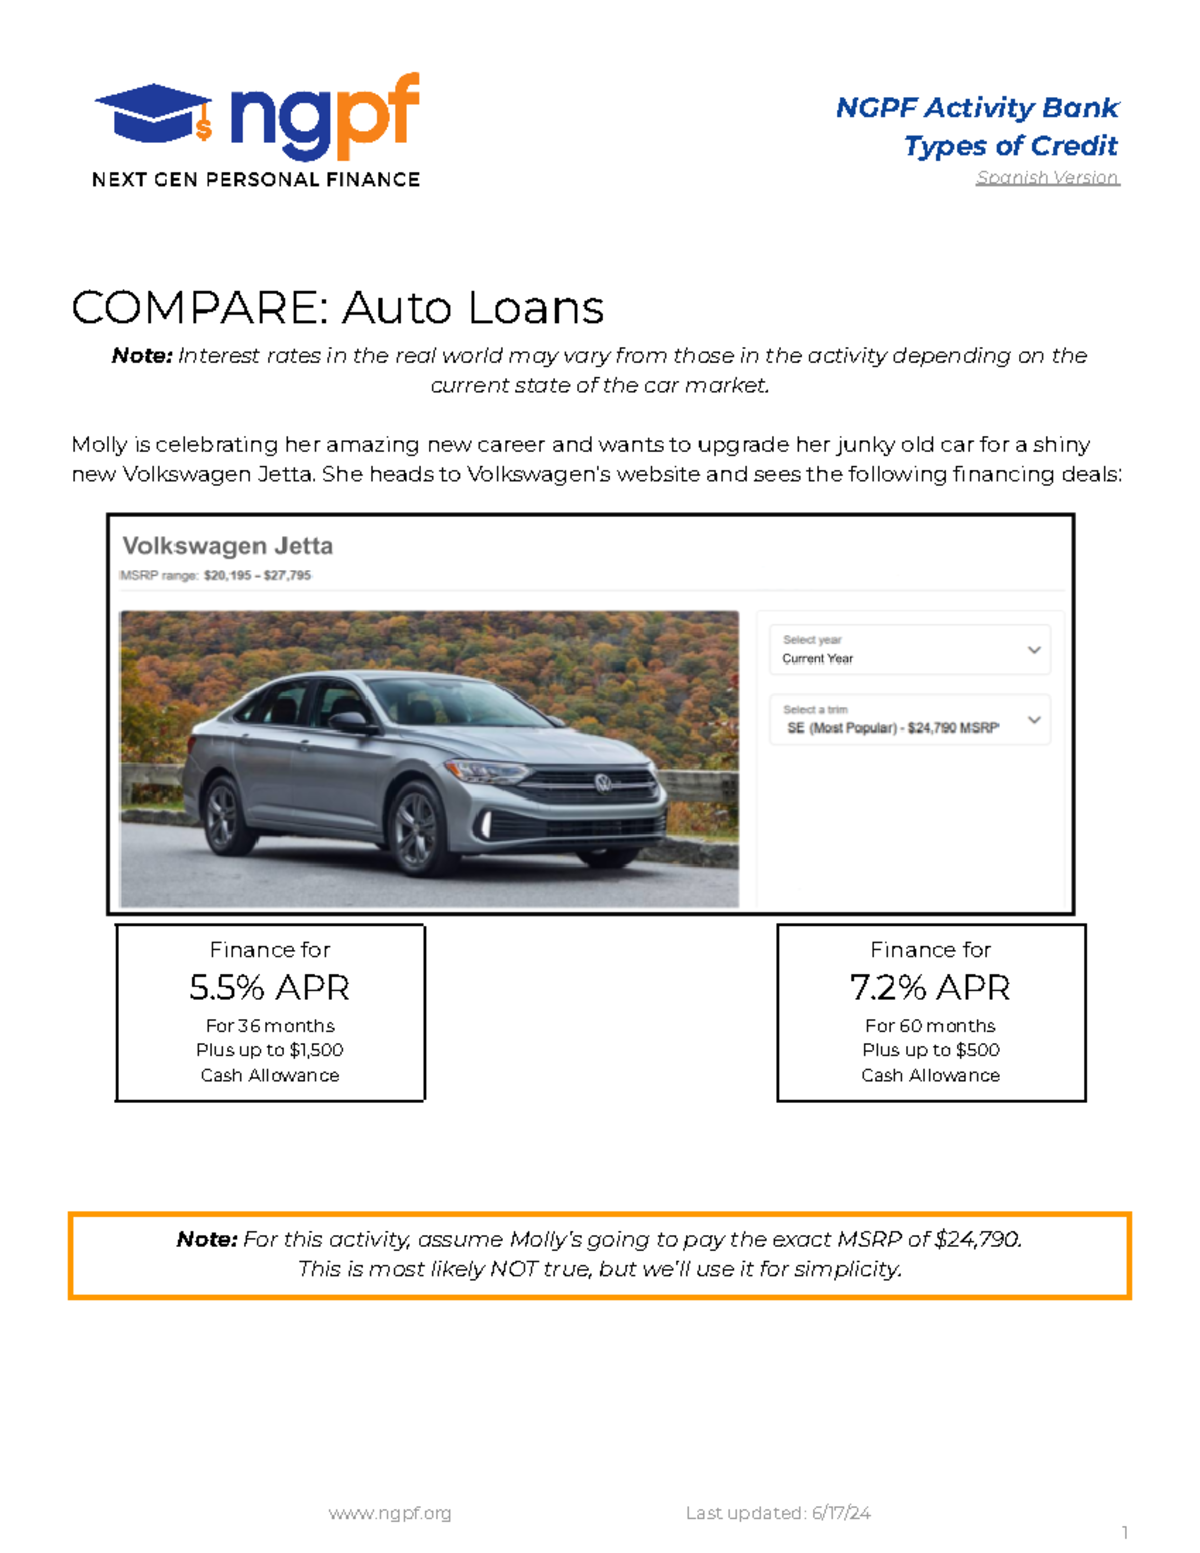
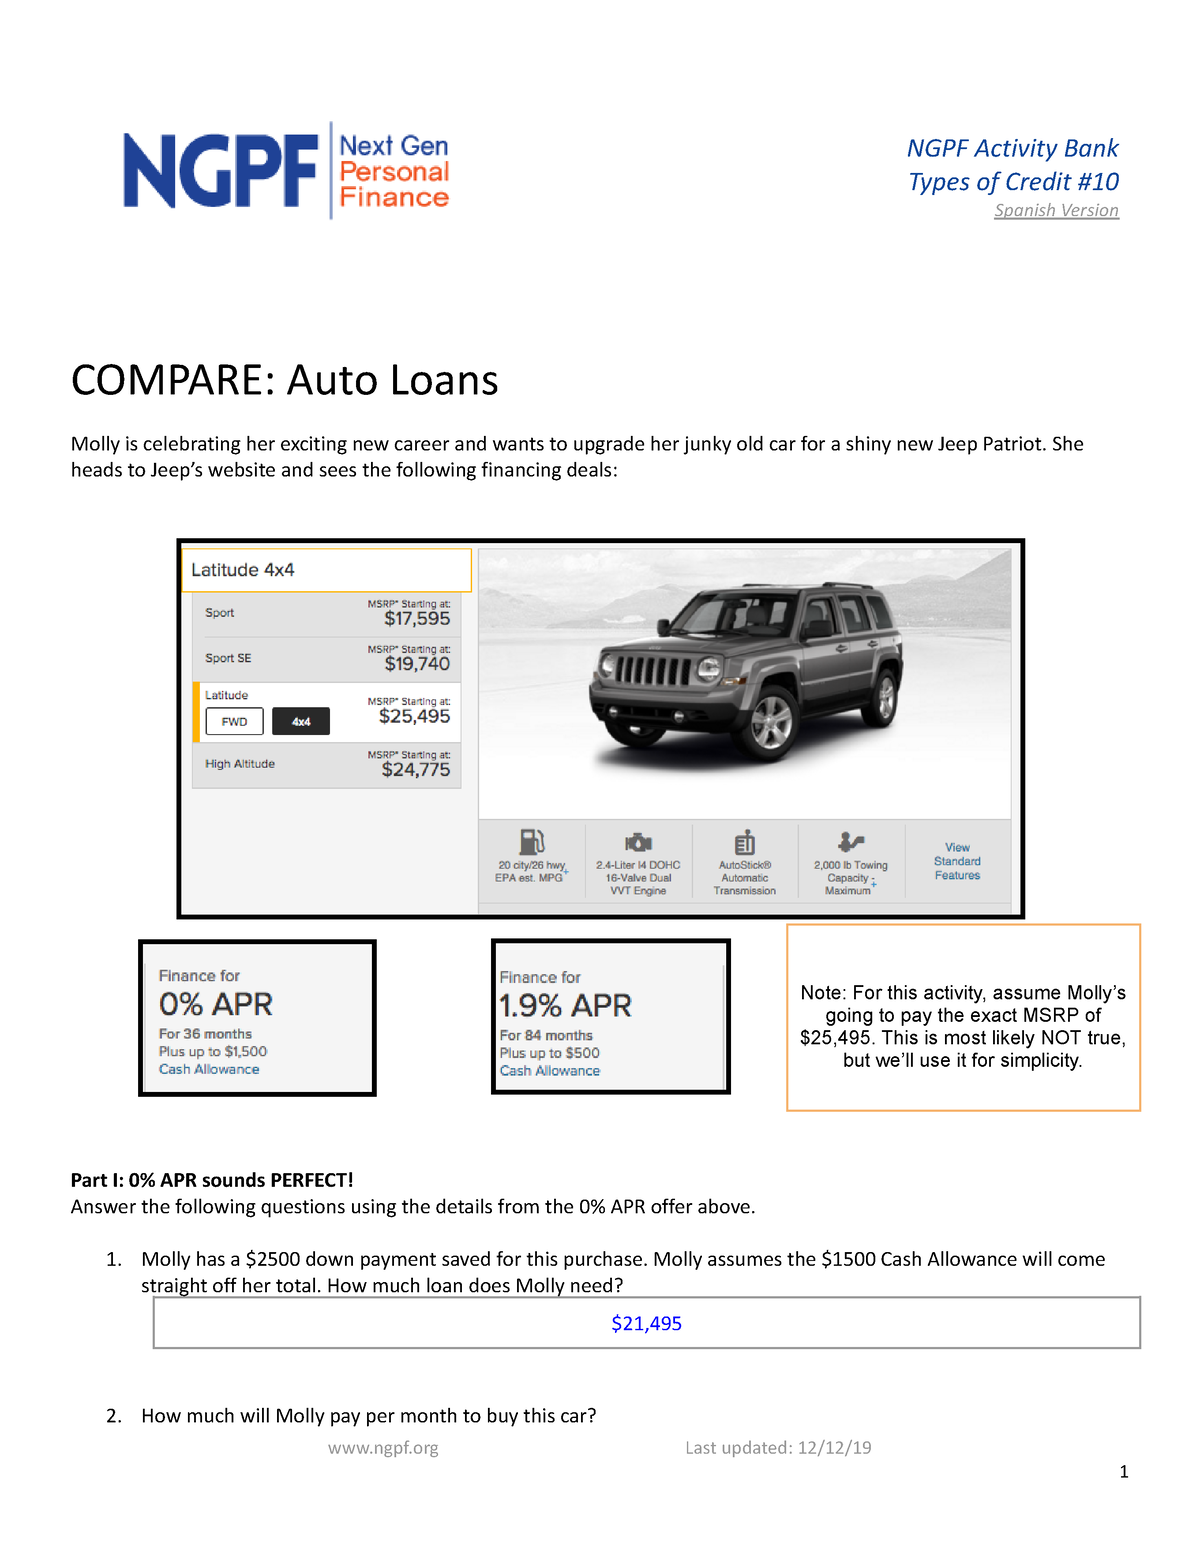
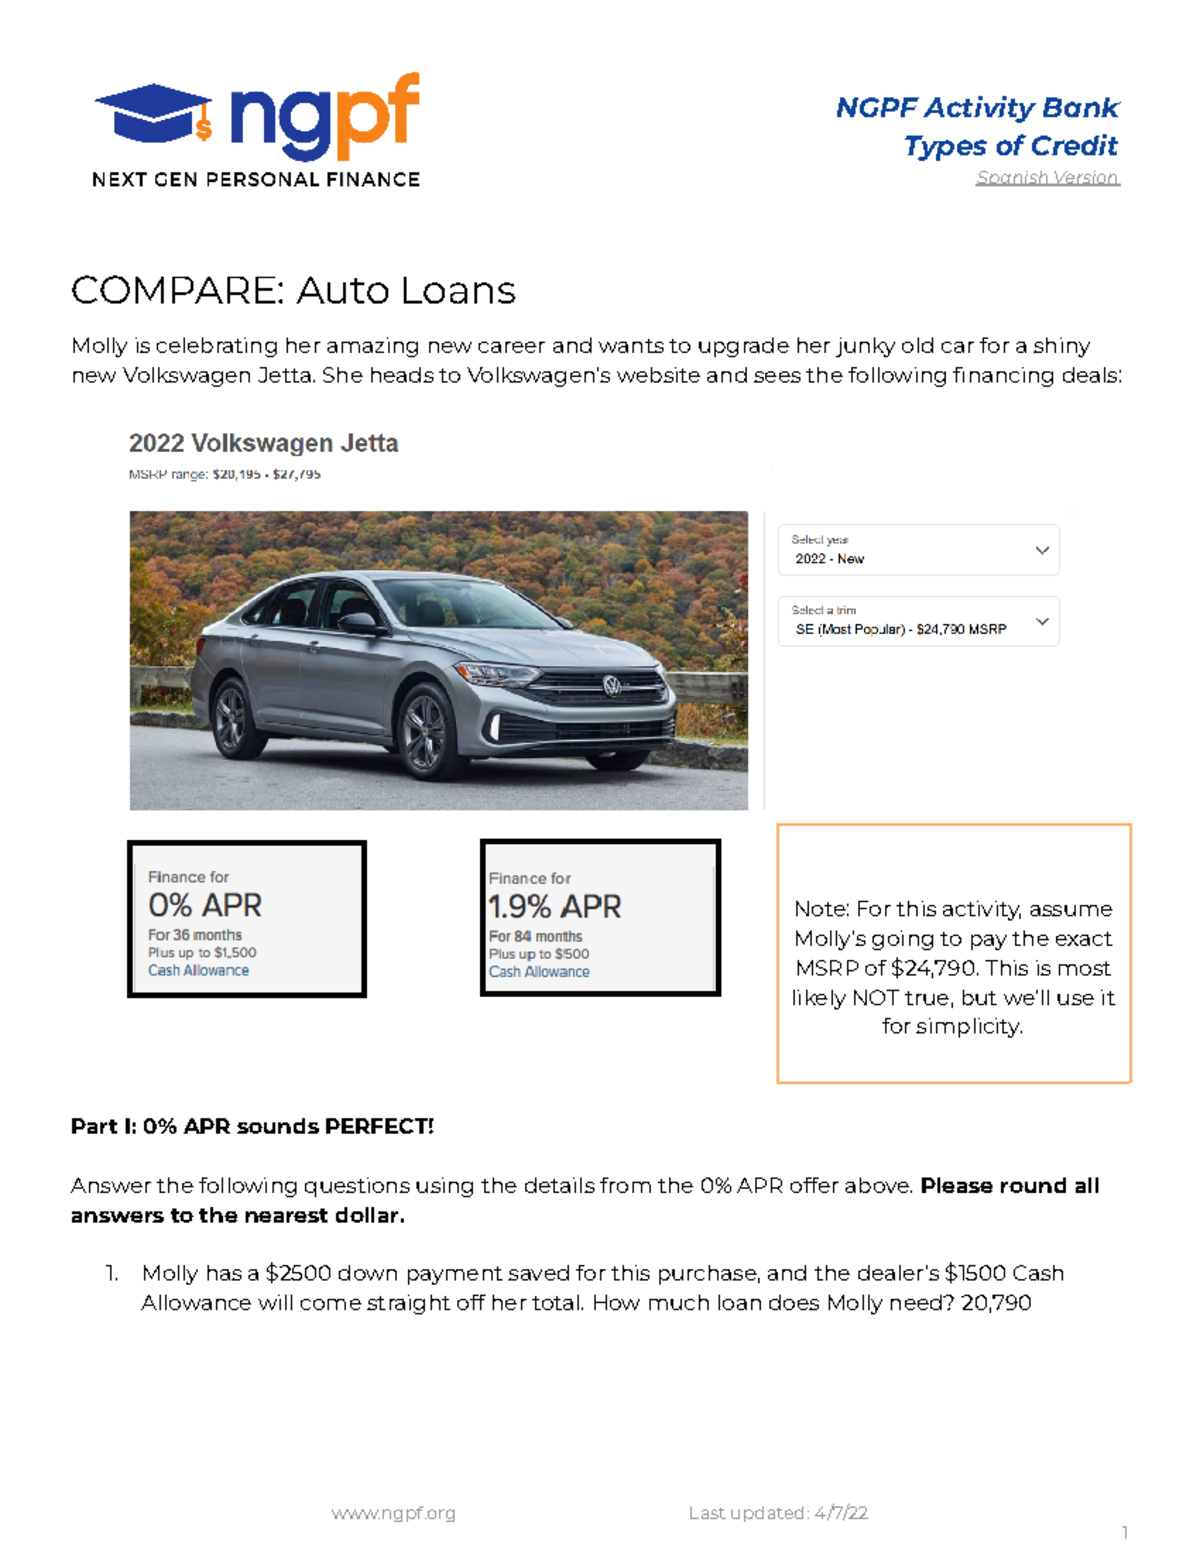
The NGPF Compare Auto Loans activity asks students to evaluate different loan offers using APR, loan amount, term length, and monthly payment calculations. It seems straightforward until you actually sit down to grade it or check your own work. That's when things get messy. I've gone through this activity multiple times now, both as a teacher and as someone who's helped students troubleshoot their calculations, and there are a few things that aren't obvious from the worksheet itself. Here's the core of what you're working with. The activity typically presents several auto loan scenarios with different terms - maybe a 36-month loan at 4.5% APR, a 60-month loan at 6.2%, and so on. Students need to calculate monthly payments, total interest paid, and total cost of the vehicle including interest. The standard formula they're expected to use is the amortization formula: M = P[r(1+r)^n]/[(1+r)^n-1], where M is the monthly payment, P is the principal, r is the monthly interest rate, and n is the number of payments. I remember one student who kept getting slightly different numbers than the answer key, about $3 to $5 off per month. She was frustrated because she thought she was doing everything right. The issue turned out to be rounding. She was rounding the monthly interest rate to four decimal places before plugging it into the formula, while the answer key uses the unrounded rate. The fix was simple - don't round intermediate values. Keep the full precision in your calculator and only round the final monthly payment to the nearest cent.
Another thing that trips people up is how NGPF handles the total cost calculation. Some students calculate total cost by multiplying the monthly payment by the number of months and adding the down payment. The answer key sometimes expects you to also account for sales tax and fees in the total cost, which means the actual financed amount might differ from the sticker price. If your numbers aren't matching, check whether the problem includes tax and registration in the loan amount or if those are separate line items. The activity also throws in a scenario where one loan has a lower APR but a higher total cost because of the longer term. Students often instinctively pick the lower rate without looking at the total interest. The answer key will show the math, but the real lesson is recognizing that APR isn't the only number that matters. A 72-month loan at 3.9% can cost significantly more in total interest than a 48-month loan at 5.4%, even though the rate looks better on paper. One counter-intuitive detail most students miss: the answer key sometimes uses the financial calculator method rather than the formula method, and the two can produce slightly different results due to how they handle compounding frequency. If you're getting close but not exact matches, try entering the values into a financial calculator or Excel's PMT function. In Excel, that's =PMT(rate/12, months, -loan_amount). The PMT function gives you the most accurate result and matches the answer key more closely than manual formula calculation.
There are limits to what this answer key can do for you. It doesn't account for every variation a teacher might create, especially if they've modified the loan amounts or added prepayment penalties to the scenarios. The activity was designed for a standard classroom setting, so if you're working with non-standard terms or real-world loan documents from actual lenders, you'll need to adjust the approach. Also, the answer key assumes you're comparing fixed-rate loans. Variable-rate loans or balloon payment structures aren't covered and would require a different calculation method entirely. If you're teaching this and need the key for reference, it's available through the NGPF member resources section on their website. You'll need an active educator account to access it. The PDF versions tend to have the answers formatted in a table that maps directly to each question number, which makes grading faster. I'd recommend printing it rather than using it on screen - it cuts grading time roughly in half compared to scrolling through a digital document while cross-referencing student work. Some people look for shortcuts like just copying the final answers without understanding the calculations. That works until a student asks why their Excel formula gives a different result than the key, or until they encounter a real loan situation where the numbers don't line up the way the simplified worksheet suggests. The answer key is a teaching tool, not a substitute for knowing how the math actually works. Spend the extra ten minutes understanding the amortization formula properly and you'll save yourself hours of remedial explanations later.
Get the Full Details