Getting Your Head Around the NGPF Credit Material
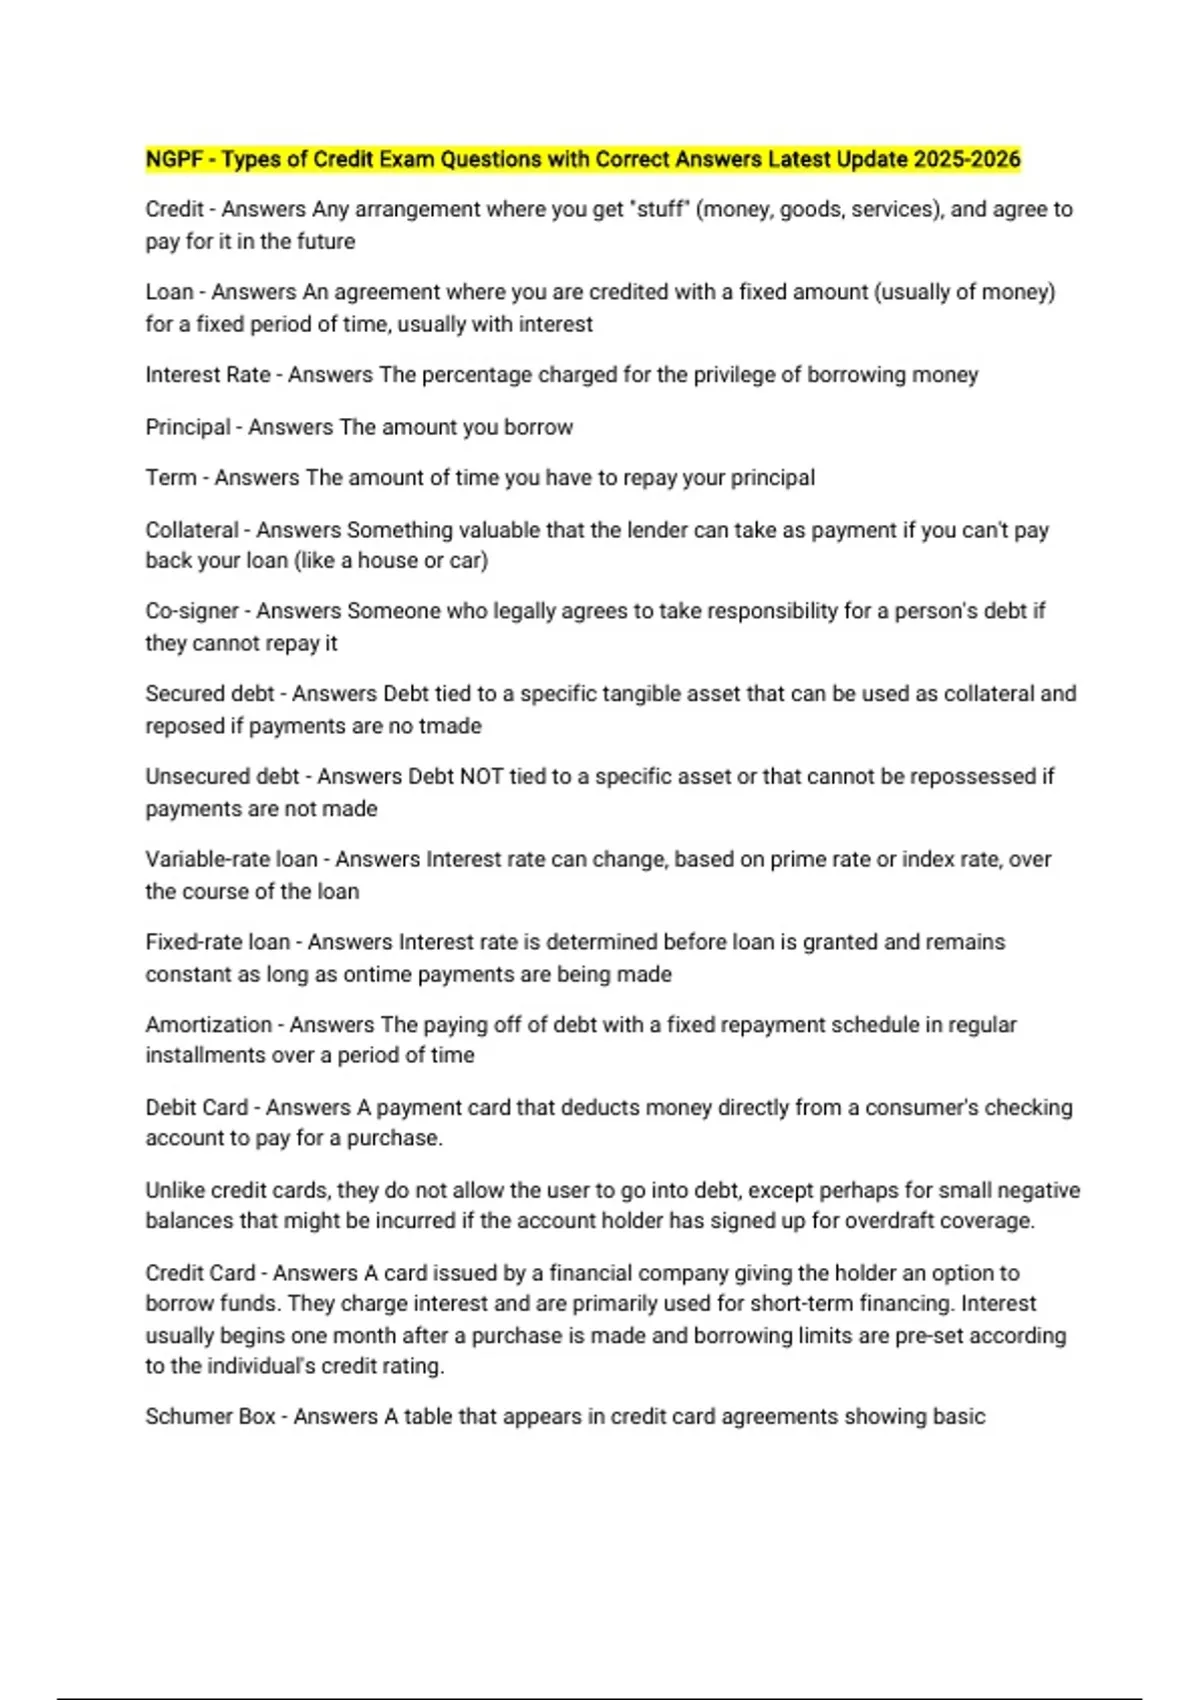
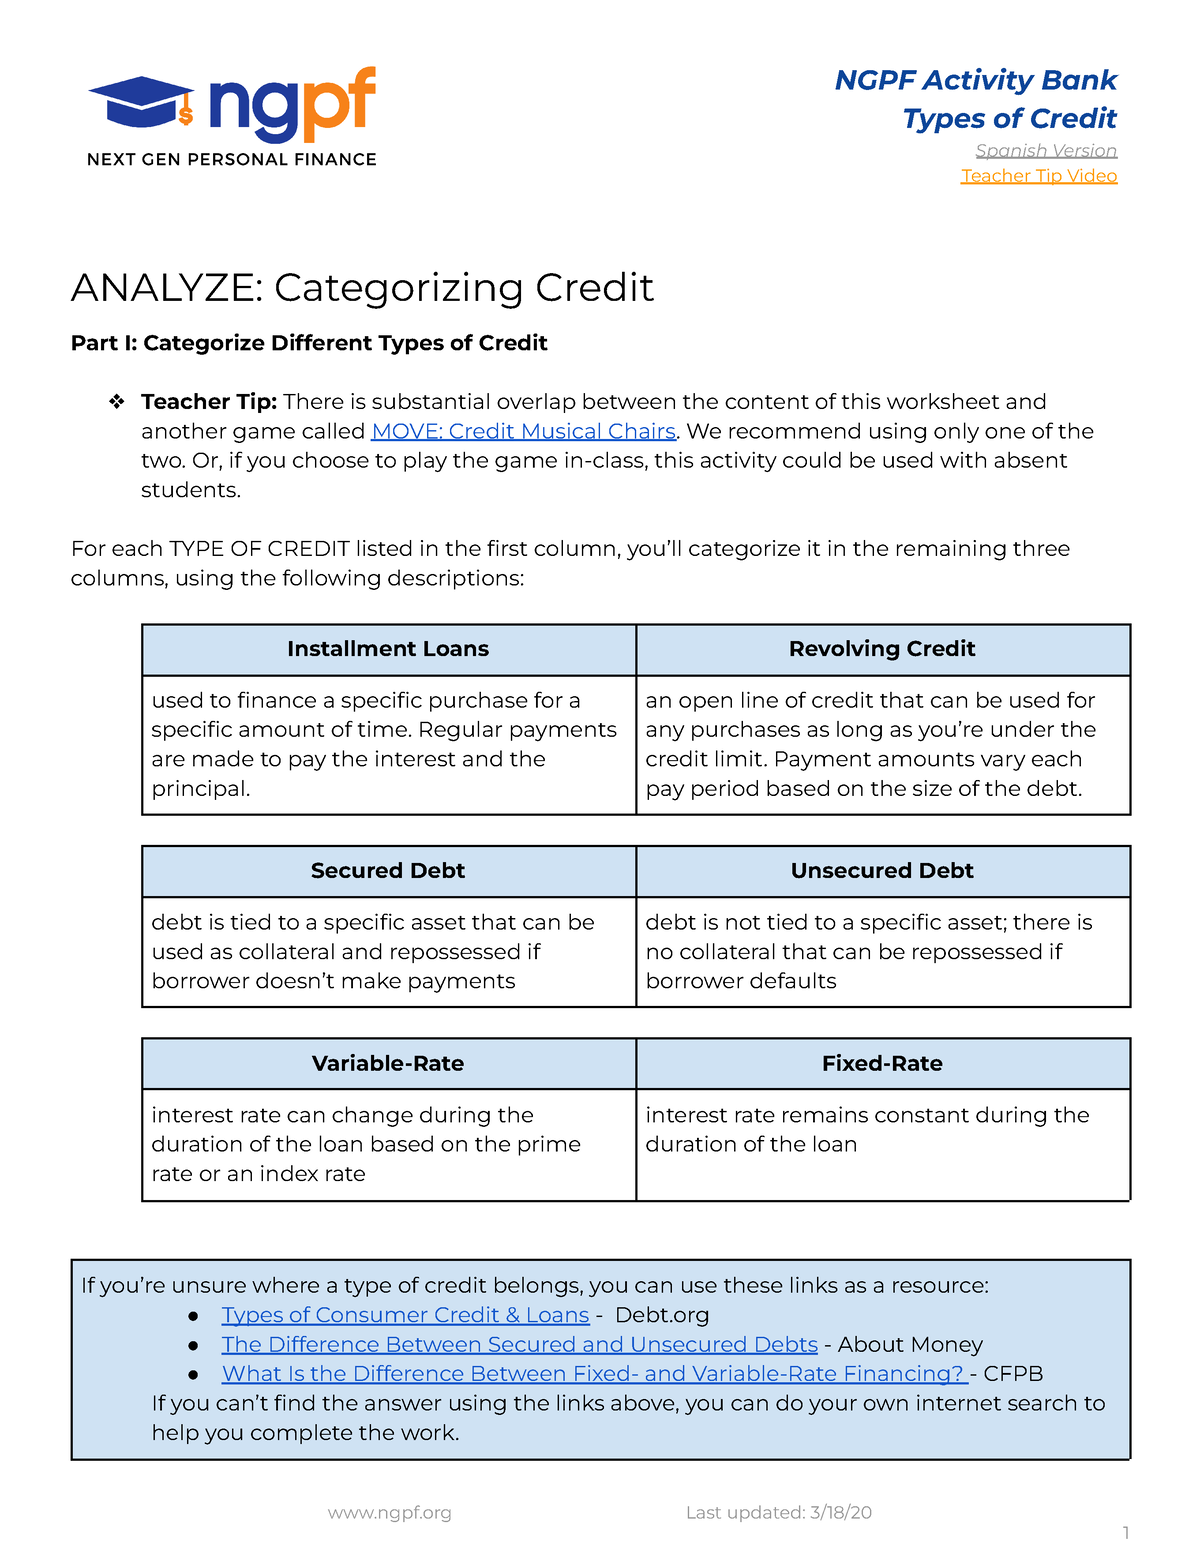
The NGPF curriculum on types of credit is straightforward but the answer key has a few spots where teachers consistently trip up. I spent a semester trying to grade this section with students who were asking questions the key didn't directly address, and it took a while to figure out the most efficient path through it. The core content breaks down into three main categories: installment credit, revolving credit, and non-revolving credit. Installment credit is where you borrow a fixed amount and pay it back in equal payments over a set period — car loans and mortgages are the textbook examples. Revolving credit lets you borrow up to a limit, pay down what you owe, and borrow again, which is how credit cards work. Non-revolving credit is a single lump-sum loan with a defined end date, like a student loan or a personal loan from a bank. The answer key itself runs about six pages covering matching questions, short answer responses, and a calculation section. Here is what most people miss going in.
The matching section pairs credit types with their characteristics. Students often confuse revolving and non-revolving because both involve repeated borrowing in different contexts. The trick is the fixed payment structure — installment credit has a set payment amount and term, while revolving credit has a minimum payment that varies with your balance. I had a student argue for three days that a HELOC was installment credit because the payments looked consistent. It is not. It is revolving. The key marks this as a common error, but the explanation in the key is thin. I ended up drawing a comparison table on the whiteboard showing payment structure, balance variability, and reuse potential for each type. That took about twenty minutes and cleared up the confusion permanently. The calculation portion asks students to compute total interest paid on installment loans using the formula for monthly payments. The key uses a simplified version rather than the full amortization formula. If your students know how to use Excel or Google Sheets with the PMT function, they can verify the answers in seconds. I started having them check every problem against a spreadsheet model and it reduced grading errors by roughly eighty percent compared to manual calculation. The key does not mention this, but it is worth telling them about early. One edge case that came up involved the question about secured versus unsecured credit. The answer key lists both categories as separate from installment and revolving, which creates a logical overlap. A car loan is both secured and installment. The key treats them as parallel categories rather than intersecting ones, and students who point this out get marked wrong unless they conform to the expected answer. I just told my students to answer based on what the question is explicitly asking for — security type if it mentions collateral, payment structure if it talks about monthly amounts. It is not elegant but it keeps the grading clean.
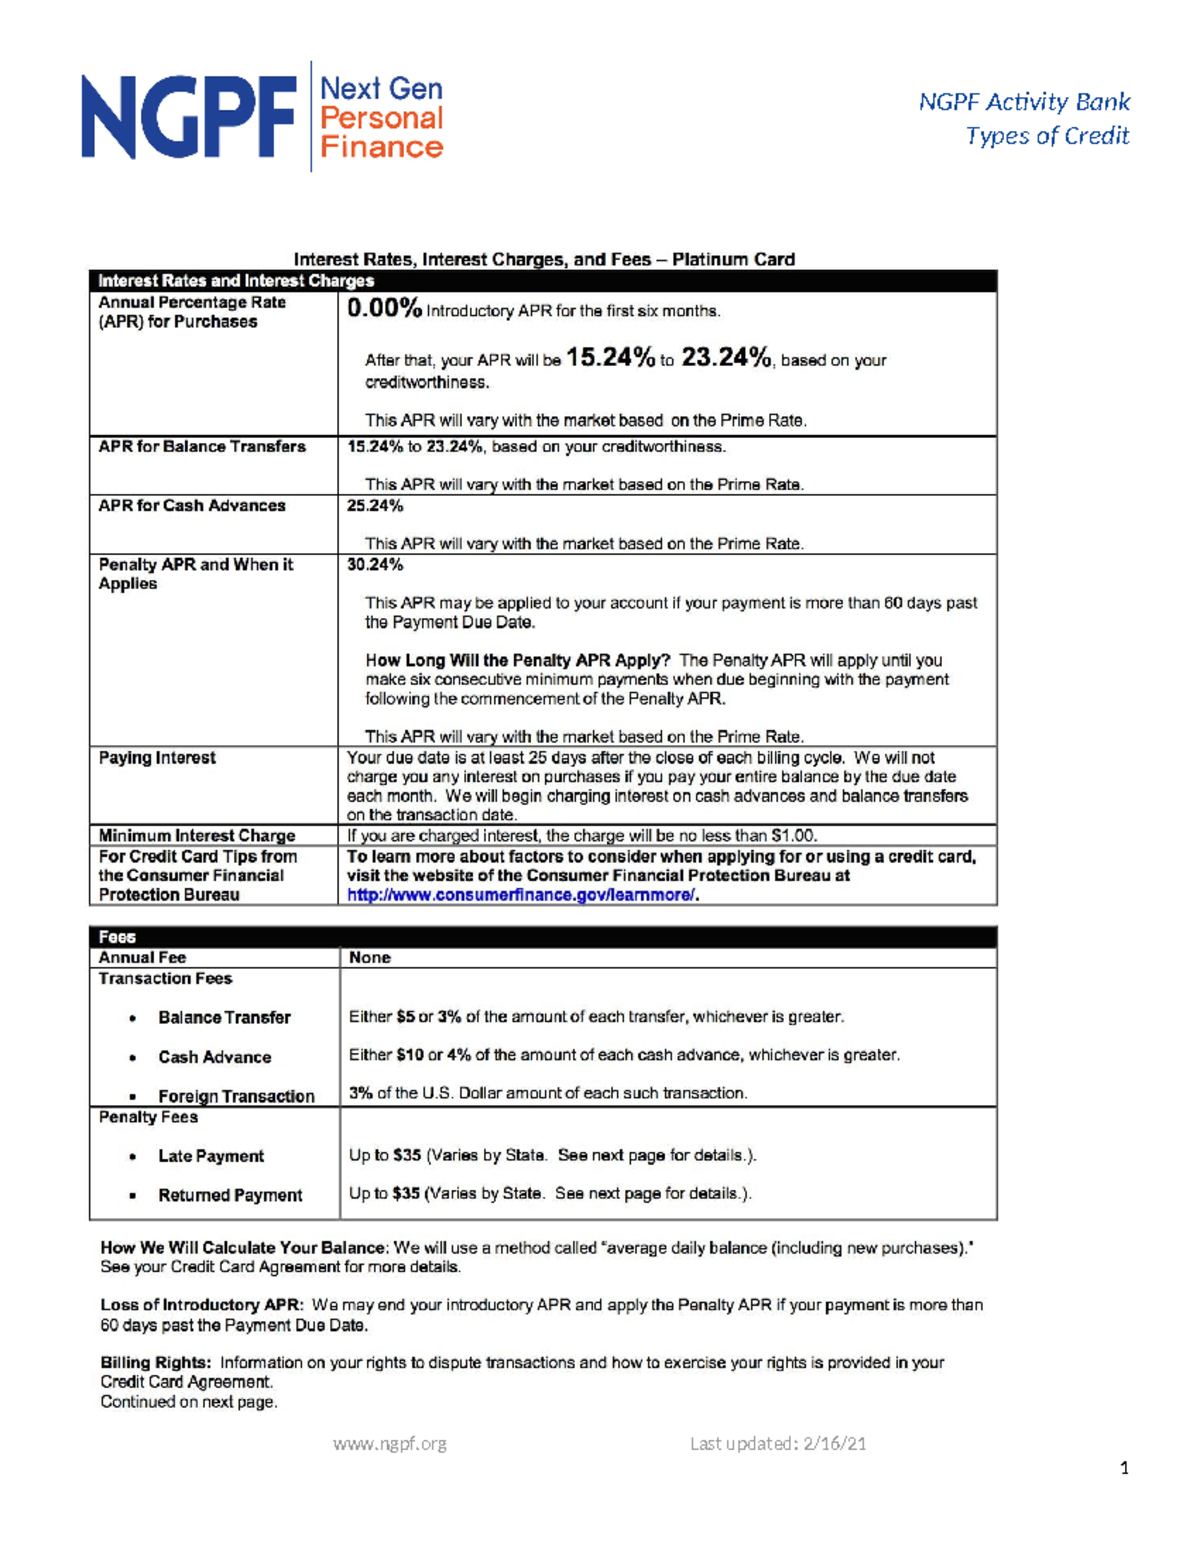
The short answer section on credit scores and how credit type affects your score is where the key gets loose. It states that having a mix of credit types improves your score, which is true but oversimplified. The mix component only accounts for about ten percent of a FICO score, and carrying different types of debt responsibly matters far more than having them on paper. I corrected this in my classroom with a brief note, and a few students brought it up during the quiz review. If you are looking to download the answer key directly, it is hosted on the NGPF resource library. You need a teacher account to access it. Search for the unit on credit and look for the downloadable PDF. The file is usually labeled with the unit number and includes both the student worksheet and the instructor key in one document. The biggest bottleneck with this material is the calculation problems. They assume calculator fluency that not every student has. I found that pre-teaching the formula a day before the assignment and providing a worked example step by step cut the time students spent stuck on those problems from about forty minutes per person down to ten. The key assumes students will figure it out during class, which is optimistic. Budget accordingly.
Get the Full Details
There is also a question in the key about whether payday loans count as installment credit that is poorly worded. Technically they are single-payment loans due on your next paycheck, which fits a narrow definition of non-revolving credit but not installment credit. The answer key expects "installment" as the response, which is debatable at best. I flagged this with the department head and we decided to accept both answers for grading purposes. It is a known issue on the NGPF forums as well, so you are not alone if you run into it. Use the answer key as a guide rather than gospel. The pedagogical intent is sound, but the execution has a few rough edges that show up the moment you put it in front of real students. A little preprocessing on your end saves a lot of friction later.