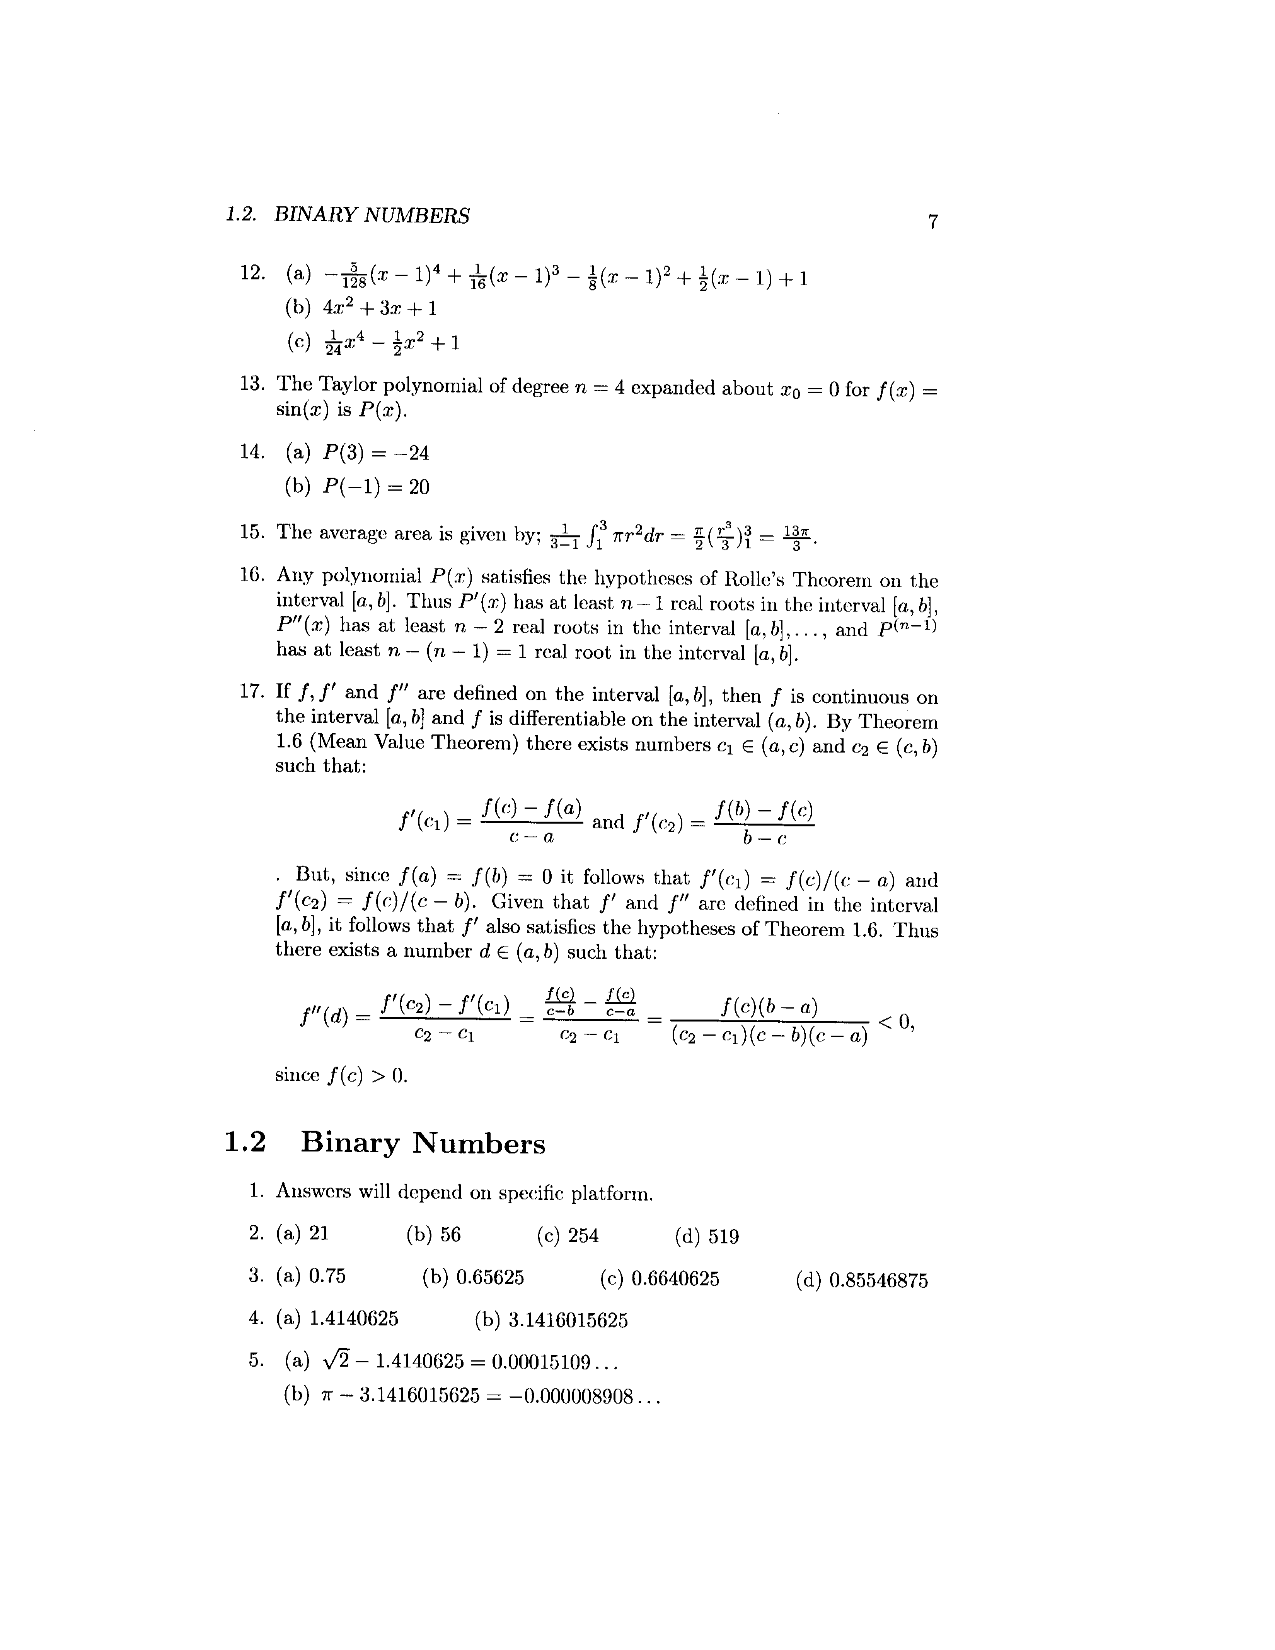
Working With the Faires Numerical Methods Solution Manual
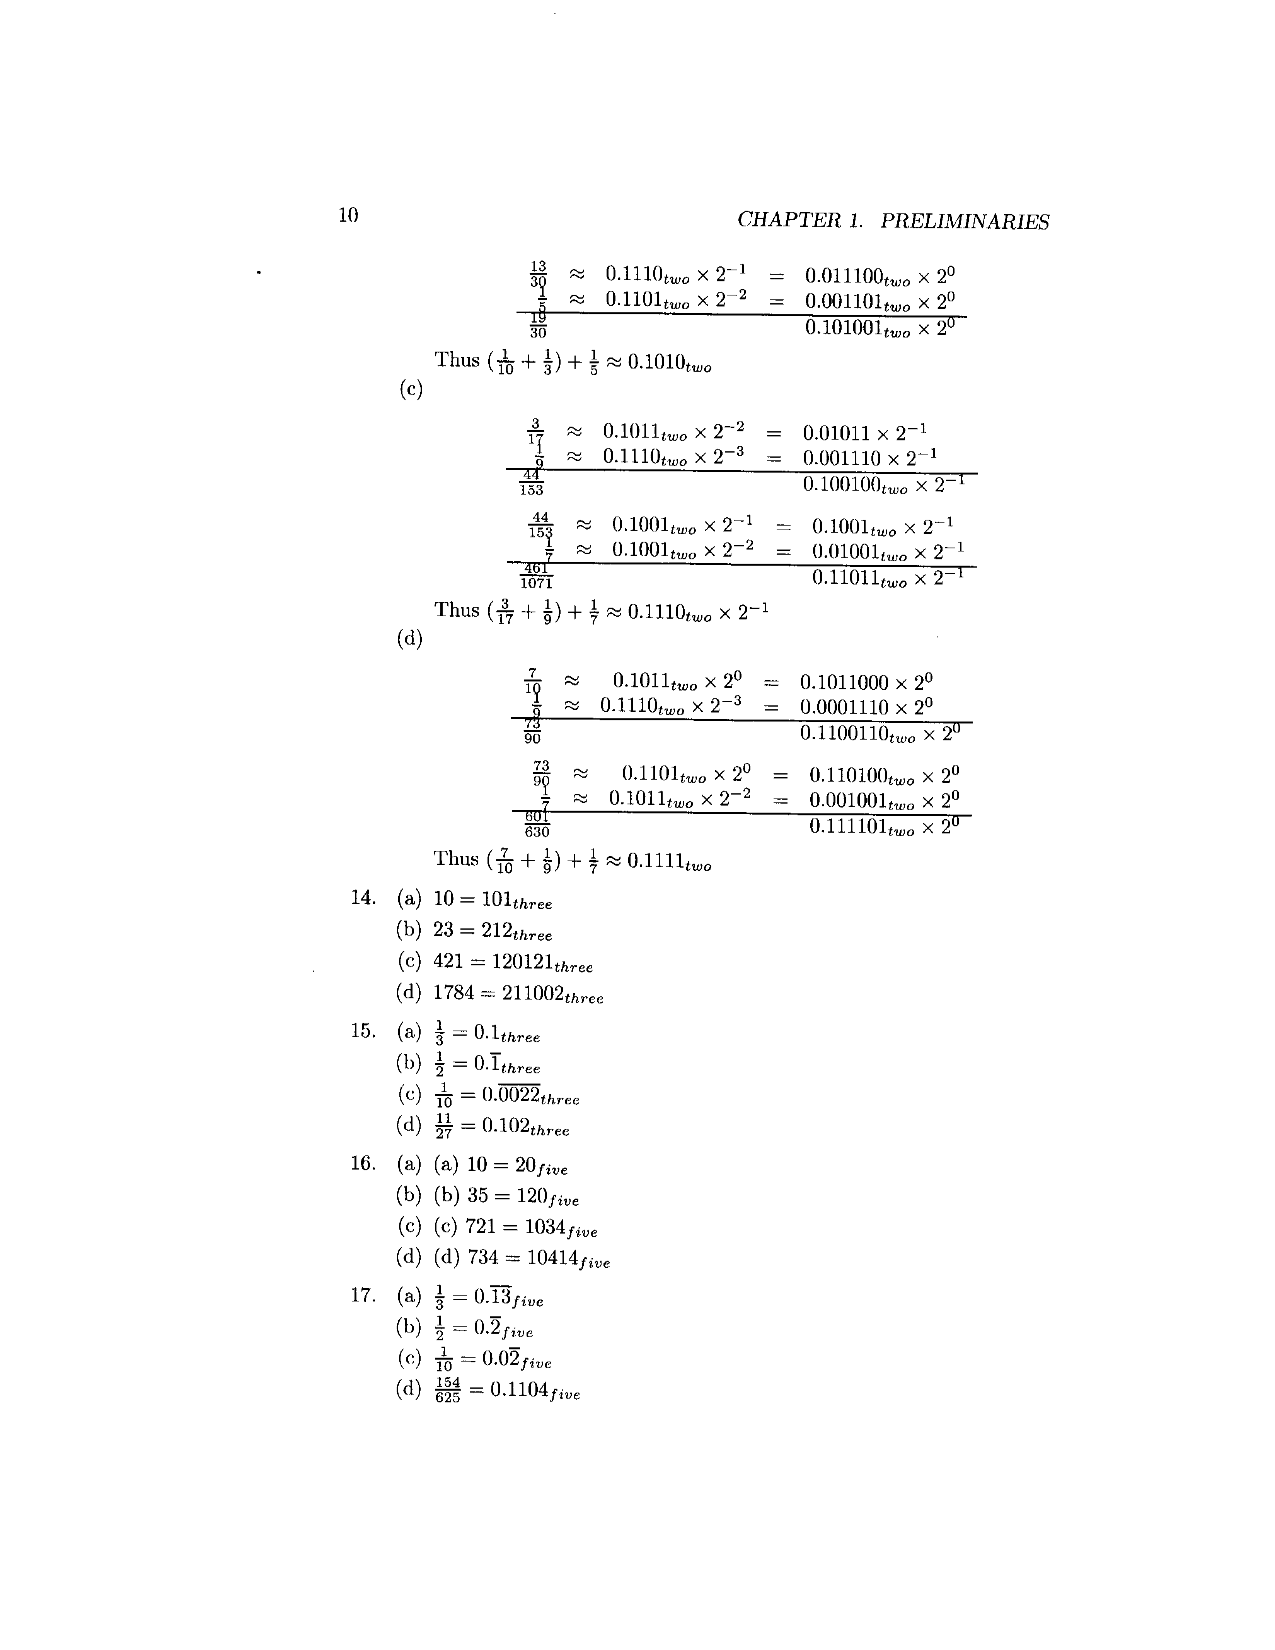
The textbook by Burden and Faires is the standard reference for most undergraduate numerical methods courses. The solution manual that accompanies the fourth edition covers all the chapter exercises, from basic rounding error analysis through Runge-Kutta methods and boundary value problems. Students use it to check work. Instructors sometimes use it to verify answer keys. The content is straightforward but the way people approach it matters. Download links circulate across academic forums, textbook publisher sites, and document-sharing platforms. The manual itself is typically distributed as a PDF by the publisher or through authorized academic channels. Some editions bundle chapter summaries alongside full worked solutions. What you get depends on which version your course requires. I ran into a specific problem last year while cross-referencing the Newton-Raphson iterations for Chapter 2. The manual's worked example for Exercise 4 showed a stopping criterion based on absolute error less than 10^-6, but the problem statement in the textbook actually asked for relative error control. I caught the mismatch because my own implementation used a different convergence check and the numbers diverged after the fourth iteration. The workaround was simple: I re-derived the iteration using the textbook's specified tolerance format and matched the manual's final result. It took about twenty minutes and saved me from submitting incorrect work.
The manual handles iterative methods reasonably well, but it has blind spots. Stiff ODE systems in Chapter 8 sometimes show solutions that look correct on paper but fail under certain step-size configurations. The manual presents a single path through the calculation, usually with a fixed step. In practice, adaptive step-size control changes the trajectory noticeably. I learned this the hard way during a project where my numerical integrator produced oscillatory garbage until I switched to a variable-step BDF method. The manual doesn't cover that alternative. One thing beginners consistently miss involves error analysis. The textbook introduces truncation error and round-off error as separate concepts. The solution manual treats them somewhat independently in its worked examples, which creates a false impression that they don't interact. They absolutely do. At machine precision limits, usually around 10^-16 for double-precision arithmetic, further iteration can actually increase error instead of decreasing it. The famous example is computing derivatives of high-degree polynomials where subtractive cancellation dominates. The manual shows clean theoretical results but doesn't always flag when floating-point behavior breaks the assumptions. Another counter-intuitive point: the Gauss-Seidel method isn't always faster than Jacobi. The textbook presents it as an improvement, and the manual's examples support that claim. But for certain matrix structures, particularly those that aren't strictly diagonally dominant, Jacobi can converge in fewer iterations or avoid oscillatory behavior that Gauss-Seidel exhibits. I encountered this in a finite-difference approximation of a 2D Laplace equation where the coefficient matrix had a specific sparsity pattern. Gauss-Seidel stalled for several dozen iterations before Jacobi converged in a fraction of the time. The manual doesn't address this edge case.
Interpolation sections in Chapters 3 and 4 are where the manual tends to be most useful. Neville's algorithm and Lagrange forms are worked through carefully. Cubic splines get solid coverage. These are mechanically straightforward topics where seeing the arithmetic step by step actually helps most students. Don't skip the examples here. On the practical side, I'd recommend using the manual as a verification tool rather than a learning primary resource. Try solving the problem yourself first. Then check. The act of working through a method like trapezoidal integration or Simpson's rule without looking at the solution builds the intuition you need when the manual's assumptions break down. And they will break down. That's the nature of numerical methods. The manual also assumes a certain mathematical maturity. If you're struggling with convergence proofs or proof techniques involving the mean value theorem, the solution steps might read like a foreign language even when the arithmetic is visible. Building that background separately improves how you use the manual significantly.
Get the Full Details
If your course requires a specific edition, make sure the solution manual matches. Later editions of the textbook sometimes renumber problems or drop older ones entirely. Using a mismatched manual wastes time and leads to confusion about which problem number corresponds to which solution. Check the ISBN before obtaining any copy. The biggest limitation of the manual is that it presents solved problems as ideal cases. Real numerical work involves messy inputs, poorly conditioned systems, and software-specific quirks. The manual won't prepare you for those situations. It prepares you for exams and homework checks. That's fine. Just understand the scope of what it does and doesn't cover. For advanced work beyond this textbook, you'll eventually need to move into dedicated numerical libraries. The concepts transfer. The implementation details change completely. The manual gets you through the coursework. Everything after that depends on your own experience with actual computational problems.