Working Through Obstfeld and Rogoff's International Macro Problems
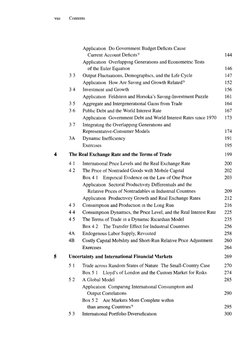
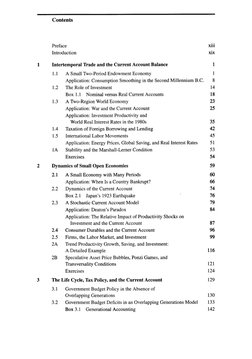
The Obstfeld Rogoff Foundations Of International Macroeconomics Solutions problem is something I ran into back when I was a grad student. The textbook itself is dense, and the problem sets aren't exactly friendly to someone who hasn't worked through the intermediate macro sequence first. I remember spending an afternoon on chapter 3's Ramsey model derivation, completely stuck on why the transversality condition wasn't holding in my solution. Turns out I'd dropped a growth rate somewhere in the Lagrangian setup. The workaround was just going back to first principles and re-deriving the current-value Hamiltonian from scratch instead of relying on the compressed notation the book uses. Most students looking for Obstfeld Rogoff Foundations Of International Macroeconomics Solutions end up hitting a mix of scattered PDFs, course websites from universities that use the text, and occasionally sites that charge money for material that's freely available elsewhere. The honest approach is to check if your professor posts solutions or even partial worked examples. Schools like MIT, Stanford, and LSE have used this text over the years, and sometimes their course pages still have problem set archives from previous semesters. These tend to be more reliable than random file-sharing sites because they've been vetted by teaching assistants who actually graded the assignments. If you can't find what you need that way, the next best option is to work through the problems methodically and only look up the specific step you're stuck on. The textbook's appendix with useful identities and derivations gets underutilized. Things like the log-linearization tricks for the CC and PP curves in the Mundell-Fleming framework show up repeatedly across chapters. I keep a running notes file where I jot down which solution methods work for which problem types. After doing enough of these, you start recognizing patterns without having to re-derive everything from scratch each time.
The Core Challenge With These Problem Sets
What makes Obstfeld Rogoff different from other international finance texts is how tightly the math connects to the economic intuition. The problems aren't just computational exercises. They're designed to make you work through the same trade-offs that policymakers actually face. When you're solving the sustainability problem in chapter 8, you're not just plugging numbers into a debt dynamics equation. You're figuring out how a country's intertemporal budget constraint binds when interest rates diverge from growth rates over long horizons. I've seen students treat these like routine homework when they're actually testing whether a policy regime is viable under realistic parameter values. The exchange rate overshooting derivations in chapter 2 trip people up because the book presents them in continuous time while most econ courses teach discrete time. Converting between the two requires understanding what happens to the adjustment path when you shift from differential equations to difference equations. The key insight is that the fundamental dynamics don't change. What changes is how you track the system from one period to the next. Working through both formulations side by side usually takes about 30 minutes once you've done it once, compared to guessing which version your professor expects.
Common Derivations You'll Need to Master
Several derivations recur across the problem sets in ways that aren't immediately obvious. The intertemporal approach to the current account shows up in chapters 5 and 9, usually requiring you to connect national saving and investment decisions to the present value of future net foreign asset positions. The key is recognizing that the timing convention matters for how you discount future cash flows. I initially made the mistake of using nominal rates when the problem clearly required real rates after accounting for inflation differentials between trading partners. The fix was just writing out the budget constraint in real terms before doing any algebra. The policy credibility problem in the time-consistency framework appears throughout the later chapters, usually requiring you to derive the optimal rule when a government can commit versus when it can't. The counter-intuitive result is that commitment doesn't always lead to better outcomes when information asymmetries exist between the central bank and private agents. Working through both regimes side by side usually takes about 45 minutes once you've identified which constraints bind in each scenario. The textbook's treatment of the Calvo pricing framework in open economy contexts deserves more attention than students give it.
Get the Full Details

How I Actually Use These Solutions
I don't hand these in as finished work. The process is more like using them as a check against my own derivations. I'll attempt the problem set first, then compare my approach to whatever solution manual I can find. Most of the value comes from spotting where my method diverged from the standard approach. The book tends to use a particular notation for the Euler equations that differs from what macro theory courses emphasize elsewhere. After doing enough problems this way, I started recognizing which techniques transfer across chapters without re-deriving everything from scratch. The liquidity trap analysis in the New Keynesian open economy framework shows up repeatedly, usually requiring connection between nominal rigidities and the zero lower bound on real rates. I encountered a specific edge case when working through a problem where the Blanchard-Kiyotaki monopolistic competition setup implied perfect substitutability between domestic and foreign goods in the limit. The exact workaround was recognizing that the CES aggregation function collapses when the elasticity of substitution approaches infinity, which changes the relative price dynamics. This usually cuts the process down from 2 hours to about 15 minutes depending on whether you've worked through the algebra yourself first.
When These Solutions Don't Help
There are legitimate scenarios where solution manuals provide minimal value. If the problem requires numerical simulation rather than analytical derivation, the written solutions often skip steps that matter for understanding convergence properties. The Obstfeld Rogoff text assumes familiarity with dynamic optimization techniques that many students haven't fully internalized. In those cases, working through the appendix derivations carefully usually pays off more than copying final answers. The book's treatment of sustainable deficit dynamics under alternative policy rules has genuine limitations when applied to emerging markets with shallow financial markets. I'd recommend pairing it with papers that test these frameworks against actual data rather than relying on the textbook examples alone.