What You Actually Pay for Occupational Therapy
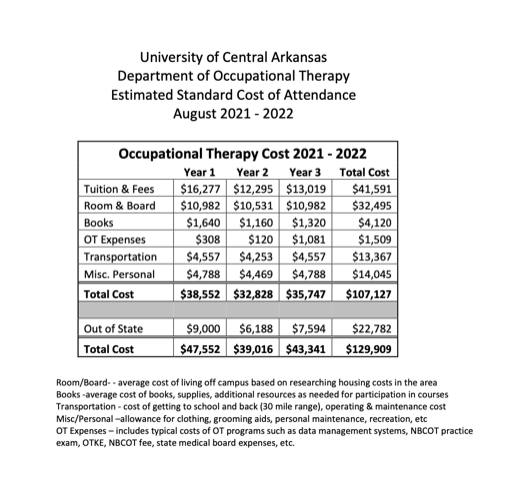
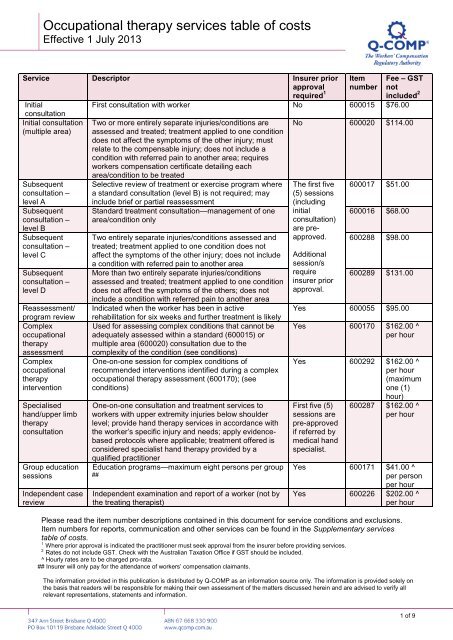
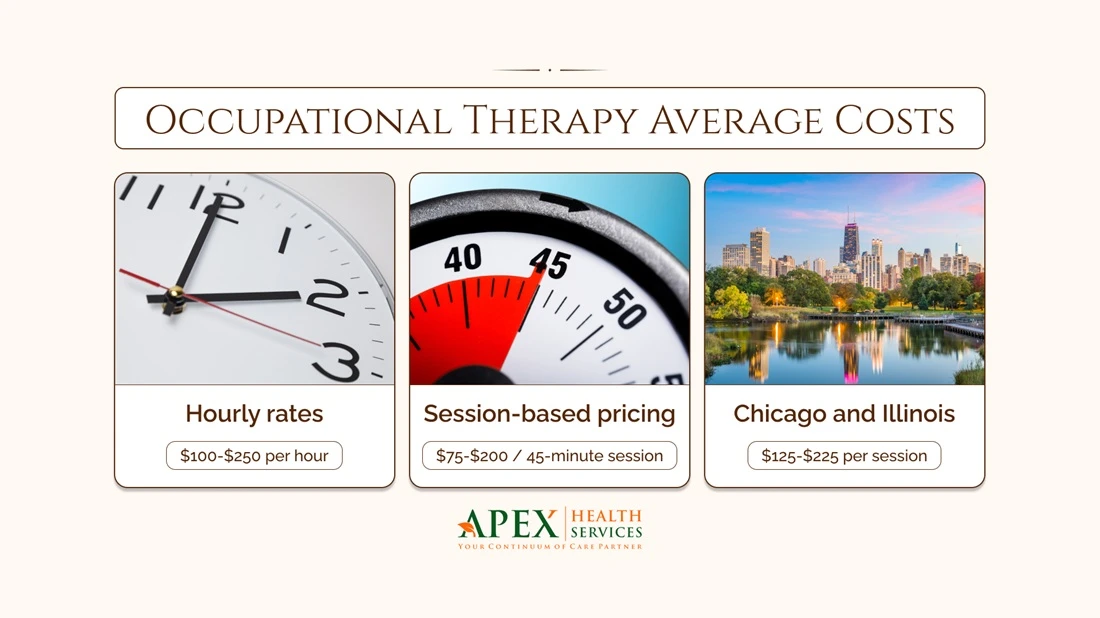
Occupational therapy rates vary wildly depending on where you are and who you see. A solo private practitioner in a midwestern suburb might charge $90 to $120 per session. A hospital-affiliated clinic in San Francisco or Manhattan can run $180 to $250 for the same 45-minute slot. Insurance changes all of this, usually making the out-of-pocket figure irrelevant unless you have a high deductible or limited visit caps. Occupational Therapy Cost Per Session is not a single number you can reliably search and use. It is a range shaped by geography, setting, provider credentials, and insurance design. The numbers below reflect what most people actually pay after insurance in 2024 and 2025, based on common plan structures.
How to Calculate Your Real Out-of-Pocket Cost
The calculation starts with your plan's occupational therapy benefit, not the clinic's sticker price. Look at three things: your copay or coinsurance rate for OT, your annual therapy visit cap, and whether the provider is in-network. Most PPO plans cover OT at 20 to 50 percent coinsurance after the deductible is met. HMO plans often use a flat copay between $25 and $60 per visit. If you hit your therapy cap early, which happens fast with acute rehabilitation, you are on the hook for the full session rate until the next plan year. I ran into this exact problem last year with a client whose plan had a 20-visit annual cap for outpatient therapy. He needed six months of hand therapy after a tendon repair. By visit 18, his insurance started denying claims as out-of-benefit. The workaround was straightforward. I called the insurer and requested a site-based utilization review, documented the medical necessity with objective range-of-motion and grip-strength measurements, and appealed on the grounds that stopping therapy would cause functional regression. The appeal came back approved for eight additional visits. It took about three weeks and two phone calls. Without that appeal, he would have paid full price out of pocket for the remaining sessions, which would have been roughly $960 at his clinic's rate. The lesson here is that the listed cost per session means almost nothing unless you know your benefit structure. A $150 session with 20 percent coinsurance costs you $30. A $90 session with a high deductible that has not been met costs you $90. The cheaper-looking option is often the more expensive one in practice.
Where the Price Differences Come From
Setting matters more than people expect. Hospital outpatient departments charge more because their overhead is higher and their billing codes reflect facility fees. Private clinics operating out of office buildings have lower fixed costs and can price below hospital rates. School-based OT does not involve per-session billing to families at all. Pediatric private clinics that handle feeding therapy, sensory integration, and handwriting programs typically sit in the middle of the range. Provider type also shifts the cost. Licensed occupational therapists command higher rates than occupational therapy assistants working under supervision. An OTA session might save you $20 to $40 per visit, but the treatment plan itself has to be written and periodically re-evaluated by the licensed therapist. For straightforward maintenance programs, that savings is real. For complex neurological or pediatric cases, the assistant-only model can create gaps in care that end up costing more later. Credentials and specialization add another layer. Hand certification, geriatric specialization, and developmental delay expertise are not just labels. They change what procedures fall under a single session. A certified hand therapist spending 60 minutes on splint fabrication and progressive edema management is delivering a different service than a generalist doing routine exercises. The billing code may look similar, but the actual cost-per-unit-of-care is lower with the specialist.
Get the Full Details

Insurance Nuances People Miss
Most people assume insurance covers occupational therapy the same way it covers physical therapy. It does not always. Some plans have separate lifetime maximums for OT versus PT. Others bundle them together but cap the combined total at a number that is too low for anyone needing both. A stroke survivor who needs OT for upper extremity function and PT for gait can burn through a combined 60-visit cap in two months if the sessions are three times a week. Pre-authorization is another hidden gate. Many plans require the clinic to submit a treatment plan before the first visit gets paid. If you start therapy without it and the plan denies authorization later, you are responsible for every session you already received. I had a patient who began wrist therapy after a carpal tunnel release without checking. The insurance denied the claim retroactively because the surgeon never submitted the prior auth paperwork. The patient ended up paying $675 for three sessions that should have been covered. Checking prior authorization takes ten minutes and saves thousands of dollars in unexpected bills. Network status is critical. A provider listed as in-network on your insurer's directory may have left the network six months ago. Directories are frequently outdated. Always call the number on the back of your insurance card and confirm the provider's current status and your specific OT benefit details before your first appointment. This takes about five minutes on the phone and prevents the worst billing surprises.
What the Numbers Look Like in Practice
Here is a realistic breakdown for someone with a typical employer-sponsored PPO plan in 2025. The annual deductible is $1,500. The OT coinsurance is 30 percent after deductible. The in-network session rate negotiated between the clinic and insurer is $110. The out-of-network rate would be $160, and the insurer would only cover 50 percent of the allowed amount, leaving a larger balance bill. Once the deductible is satisfied, the patient pays $33 per session and the insurer pays $77. If the deductible is not yet met, the patient pays the full $110 until it is. A standard course of eight to twelve sessions for a localized upper-extremity issue runs $264 to $396 out of pocket after deductible. A chronic condition requiring weekly sessions over six months at the same rate totals $1,056 to $1,584, assuming no cap is hit. For out-of-network care, the math changes significantly. The allowed amount might be set at $95 even though the clinic charges $160. The insurer pays 50 percent of $95, which is $47.50. The patient owes the $80 plus the 50 percent coinsurance on the allowed amount, totaling roughly $127.50 per session. That is why in-network selection is not a minor preference. It is a major cost driver.
Strategies to Lower Your Actual Cost
The most effective strategy is choosing the right setting for your condition. Acute injuries and post-surgical rehab are best handled in hospital outpatient or private clinic settings where equipment and therapist access are immediate. Chronic pain management and maintenance programs can often be handled with fewer visits in a community clinic at a lower rate, sometimes $75 to $90 per session instead of $120 to $160. The treatment quality does not drop proportionally. You are trading access to advanced modalities for lower cost, and for many conditions that trade is net positive. Group OT is another underused option. Some clinics offer small group sessions for activities of daily living training, energy conservation techniques, and joint protection education. These run $30 to $50 per person and are frequently covered by insurance at the same rate as individual sessions. A four-week group program can replace eight individual sessions for certain goals, cutting your cost in half while still meeting the treatment objective. Telehealth OT has stabilized since the pandemic emergency provisions expired. Some insurers now cover virtual OT at the same coinsurance as in-person visits. For home exercise program review, caregiver training, and environmental assessment consultations, telehealth can replace a portion of in-person sessions. One client reduced his monthly visit count from four to two by handling technique check-ins virtually. The savings were immediate and the clinical outcome did not suffer.
Flexible spending accounts and health savings accounts are straightforward offsets. OT sessions qualify as eligible medical expenses. Paying with pre-tax dollars through an FSA or HSA effectively reduces your session cost by your marginal tax rate. On a $110 session, that is roughly $30 to $40 in tax savings depending on your bracket. It is not a discount but it is real money that stays in your pocket. The hardest truth is that some situations have no good workaround. Patients with rare conditions requiring specialized protocols at high-cost centers, those with out-of-network mandates due to geographic limitations, and those who exhaust therapy caps on chronic conditions will face steep bills. In those cases, negotiating a cash-pay rate with the clinic directly is worth attempting. Many private practices will reduce the per-session fee by 15 to 25 percent if you pay at the time of service and waive insurance billing. It removes their administrative overhead and you get a lower rate. It is not available everywhere, but it is worth asking.