What Path In Investment Banking Actually Looks Like When You're Inside It
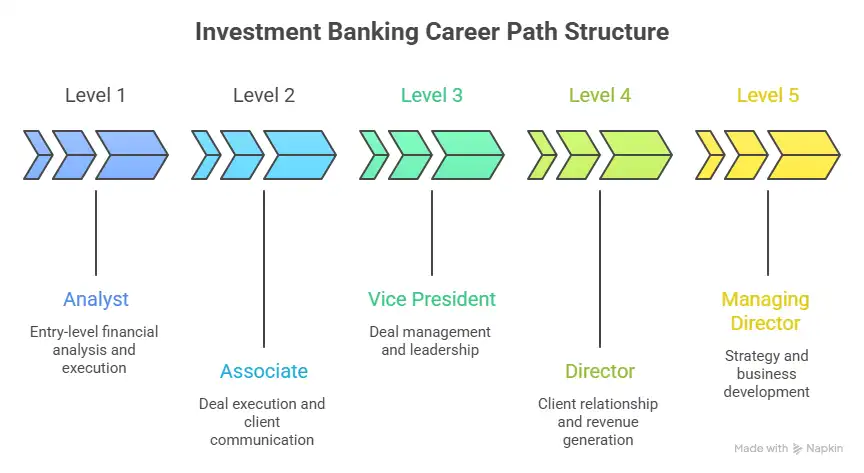
Most people think getting into investment banking is about GPA and networking events. It's not. It's about surviving the first eighteen months without making a basic error that gets sent to the managing director. I've seen people come in from top schools, bright as hell, and get filtered out by month four because they didn't understand how deal flow actually moves through a firm. The Path In Investment Banking isn't linear. You hear that a lot, but most advice you'll find treats it like a checklist: undergrad, internship, analyst program, associate, VP, director, MD. That's the brochure. The real path is messier and depends heavily on which desk you end up on, who your direct supervisor is, and whether the book of business stays intact when someone retires or gets pushed out.
Navigating the Path In Investment Banking: The Ground Level
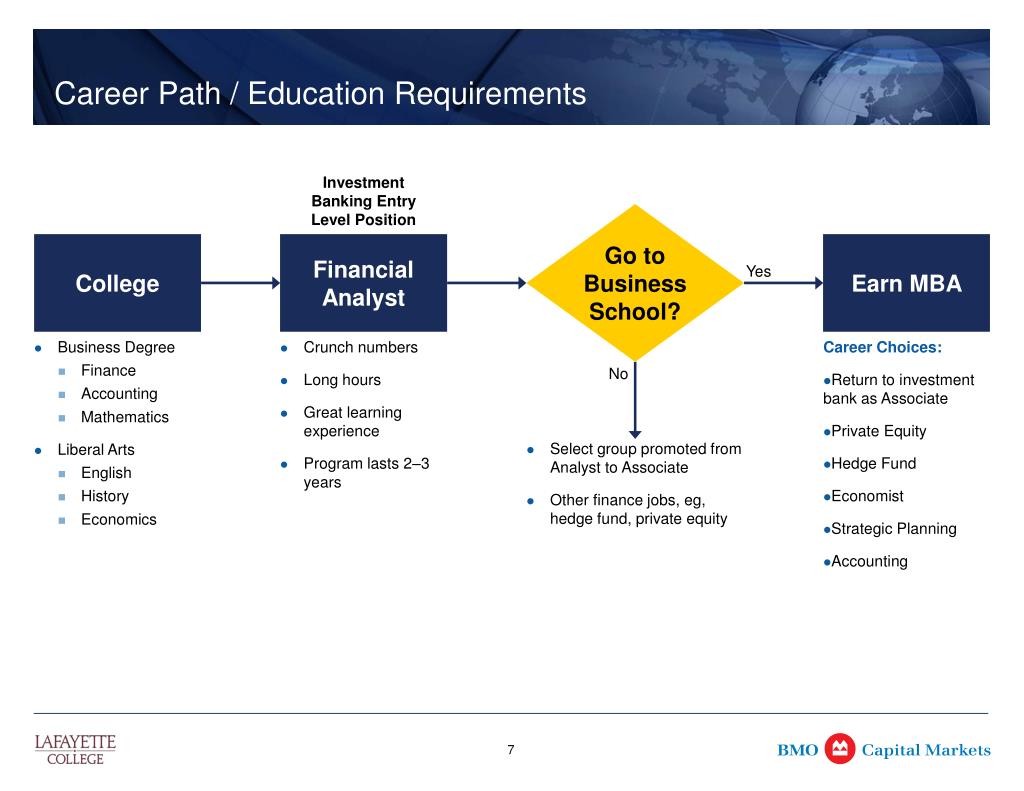
Start with the analyst program. This is where you spend two to three years doing the work that senior people refuse to touch and junior people don't want to do yet. Financial modeling. Pitch books. Data room management. Due diligence support. LBO models that need to be re-done because the client changed their mind about structure. You'll learn more in six months of actual deal work than you will in two years of coursework. Here's something nobody tells you about the analyst track: the people who advance fastest aren't always the ones with the best models. They're the ones who understand when to push back. I had a first-year analyst once who noticed a revenue multiple in a comps table was pulled from a filing that had since been restated. She flagged it before the deck went to the client. Her VP took the hit for not catching it, and she got moved onto the next deal instead of being made scapegoat. That moment mattered more than any valuation skill she'd ever built. Associates step up after the analyst years. You're now responsible for building the actual models that analysts lay the groundwork on, reviewing their work before it reaches the VPs, and managing the day-to-day relationship with the client teams. The jump from analyst to associate is where most people stall. The work changes from executing to directing. If you spent your analyst years just grinding hours without developing a sense for what the deal is actually trying to accomplish, you'll struggle here.
The Real Bottlenecks That Derail Your Progression
I remember working on a mid-market buyout where the path forward seemed clear on paper. We had the model, the comps, the comparable transactions. But the LTV-to-EBITDA covenant on the proposed credit facility was tighter than anything in the current market. Our initial structure would have gotten rejected by the syndicate desks within hours. I spent three days talking to the leveraged finance team to understand what they actually needed versus what the textbooks said. The workaround was repositioning part of the debt as supplemental commitment rather than senior secured, which changed the entire yield profile and made the deal pass underwriting. This kind of problem doesn't show up in any guide about the Path In Investment Banking. It shows up at 11 PM on a Tuesday when the printer is breaking down and you need the pitch book ready by 8 AM. Another counter-intuitive thing: sector expertise matters more than product expertise for long-term advancement. Everyone wants to be a restructuring guy or a tech M&A specialist. But the people who make it to MD tend to be the ones who understand a specific industry deeply enough to anticipate client needs before the RFP comes in. A healthcare M&A banker who knows how FDA approval timelines affect deal timing is more valuable than a generalist who can build a perfect DCF. There are also seasons where the path simply closes. In 2022 and 2023, IPO pipelines dried up across most sectors. Banks shifted focus toward recapitalizations and distressed advisory. Analysts who'd been training specifically for big public offerings found themselves with nothing to do for months. The firms that survived well were the ones where people had built relationships across multiple groups during their analyst years. If your entire identity was tied to one desk and that desk got hollowed out, you had limited options.
Get the Full Details

What Actually Moves the Needle in Your Career
Performance reviews matter, but they matter less than who vouches for you when you're not in the room. I've watched competent analysts get passed over for promotion because their VP didn't have the political capital to advocate for them. Meanwhile, someone average got fast-tracked because a MD remembered them from a summer internship three years earlier and thought highly of their work ethic. The move from VP to director is where the game changes again. You're no longer managing deals. You're bringing in business. If you haven't been building client relationships since your first year — even casually, even by being the person clients enjoy working with — this transition will be brutal. Some firms have formal business development expectations baked into VP reviews. Others don't make it explicit until it's too late. A realistic timeline for reaching managing director at a bulge bracket bank is eight to twelve years if everything goes well. At a middle-market firm, it can be faster because the hierarchy is thinner, but the pressure is different. You're expected to have a book of business much earlier. I've seen VPs at mid-cap shops leave after three years because they couldn't generate enough referral business, even though their deal execution was solid.
The compensation story is straightforward but not simple. Analysts at top firms start around $100,000 to $130,000 total compensation including bonus. Associates range from $175,000 to $300,000. VPs can see $400,000 to $700,000. Directors and above are where numbers become genuinely variable, often ranging from $800,000 to several million depending on business generation. The bonus component is what makes this path attractive and what makes it stressful. A bad year can cut your compensation in half.
When the Path Doesn't Work For You
Not everyone is suited for this. The hours are long, the margin for error is thin, and the culture in many firms rewards a kind of relentless availability that isn't sustainable for most people. I've known people who left after two years for private equity, then came back three years later as associates because they missed the deal-making pace. I've also known people who stayed twelve years and never made VP because they were great executors but terrible relationship builders. If the traditional banking path doesn't fit, there are adjacent routes. Corporate development roles at operating companies offer similar deal work with better hours. Boutique advisory firms like Evercore or Moelis have different culture dynamics than the bulge brackets. Some people find better fits in credit strategies, structured finance, or even operational roles within PE firms where the analytical rigor is similar but the grind is less extreme. The reality is that the Path In Investment Banking rewards a specific combination of technical skill, political awareness, and endurance. It's not the only path to a good career in finance. It's just one path that happens to be well-charted and heavily populated by people who think it's the only path. You'll hear that a lot. The people who do well are the ones who learn the route, understand where it breaks down, and know when to take a different road.