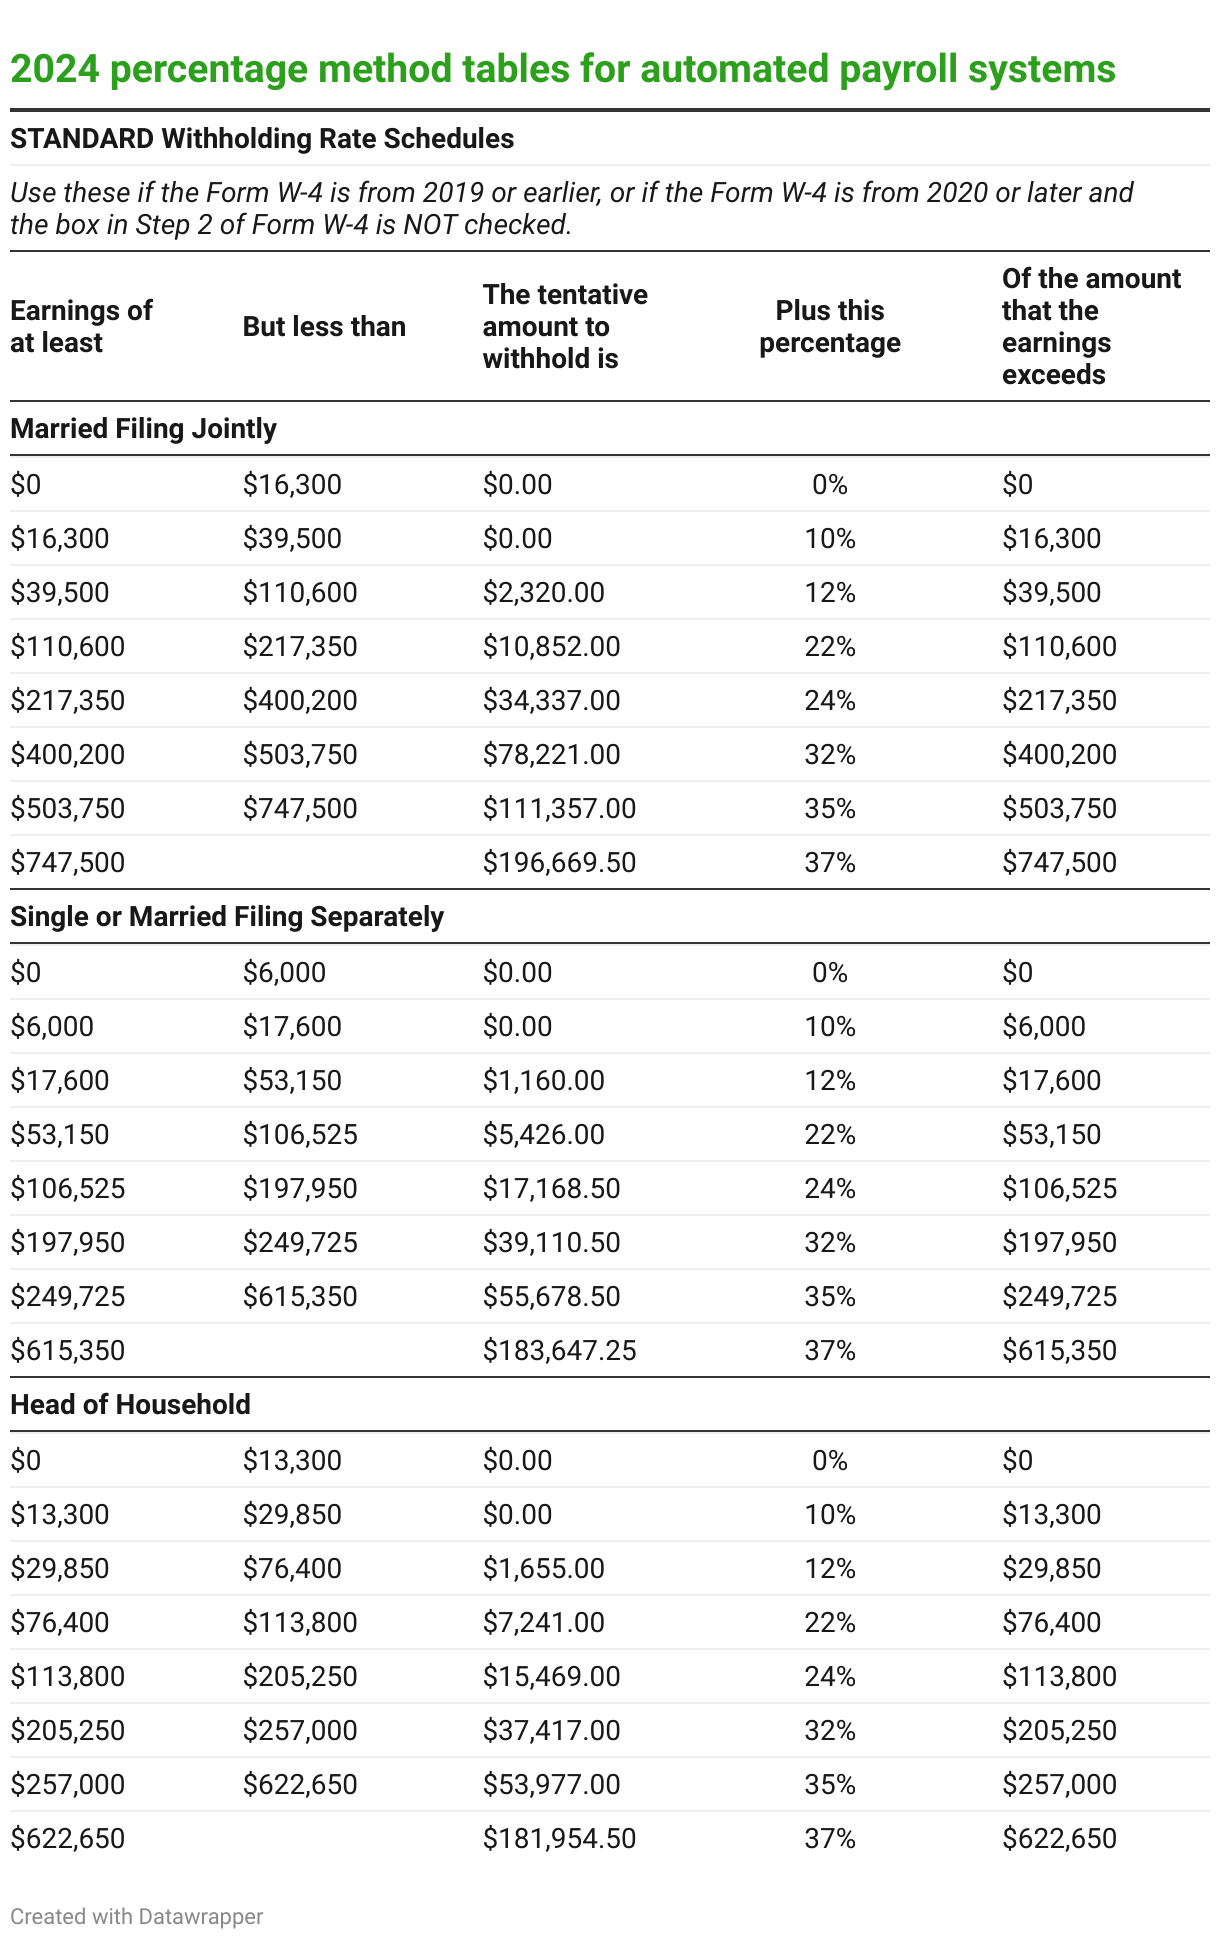
What Payroll Tax Actually Means for Your Business
Payroll tax guide materials are everywhere online, and most of them are either too generic or actively wrong about state-level compliance. I have spent years watching small business owners get burned on this exact topic because they followed a template that didn't account for their specific situation. This is a practical breakdown of what you actually need to handle, not a rehash of IRS publication language you can find in three seconds. The core issue most people miss is that payroll tax isn't one thing. It is federal income tax withholding, Social Security and Medicare (FICA), federal unemployment tax (FUTA), and then whatever your state and locality throw at you on top. Getting the federal piece right is the easy part. The complexity comes from the fact that every state handles quarterly reporting differently, some cities add their own withholdings, and independent contractor classification alone can cost you six figures if you get it wrong.
Payroll Tax Guide Basics You Actually Need
Start by understanding the employment tax triangle. You as the employer are responsible for three categories: withholding employee taxes from their paycheck, paying the employer portion of FICA, and paying FUTA. The employee portion gets withheld from wages, but if you don't withhold it correctly, the IRS still comes after you for the full amount plus penalties. That isn't a warning, it's just how the law works. Here is a practical note about deposit schedules that nobody explains well. The IRS uses a looks-back period to determine whether you are a monthly or semiweekly depositor. You calculate this based on taxes owed in the previous four quarters. If you were a monthly depositor last year but had a spike in Q3 that pushed your total over the threshold, you switch to semiweekly for the current year. I learned this the hard way in 2019 when a client had a seasonal hiring surge and missed the semiweekly requirement. The penalty was 2 percent per day on the late deposit, capped at 10 percent. We paid about $4,700 in penalties that could have been avoided with a simple annual review of deposit schedule eligibility. Form 941 is your quarterly employment tax return. It covers withheld income tax and FICA for all employees. Form 940 covers FUTA. These are filed separately and have different deadlines. Form 941 is due by the last day of the month following the end of the quarter, so April 30, July 31, October 31, and January 31. Form 940 is due by January 31 with a slightly different payment structure. State filings vary wildly. Some states require weekly deposits, others monthly, and a few like Pennsylvania and New York have additional local withholdings that require separate filings.
The Parts That Usually Go Wrong
Wrong classification is the single biggest source of payroll tax trouble. Independent contractors versus employees isn't just a legal preference, it changes your entire tax obligation. The IRS uses a behavioral control, financial control, and relationship test. If you control when and how work happens, provide equipment, and pay on a regular schedule, that person is almost certainly an employee regardless of what your contract says. I had a situation last year where a company was paying a writer as a 1099 contractor for three years, had set weekly deadlines, provided style guides, and required revisions. When the IRS audited, the contract didn't matter. The behavioral control was clear. They owed back FICA, FUTA, and penalties on approximately $80,000 in payments. Another common failure point is timely deposited taxes. The IRS penalties for late deposit start at 2 percent and go up to 15 percent depending on how late it is. If you are a semiweekly depositor, taxes withheld mid-week must be deposited by the following Friday, and taxes withheld on or before Friday must be deposited by the following Wednesday. These windows are tight and the system doesn't care that it was a holiday weekend unless you planned for it. Set calendar reminders three weeks before each deadline and run the deposits early, not on the deadline day. Workers' compensation insurance is another area that gets ignored in payroll tax planning. It isn't a federal tax but it is a mandatory payroll-related cost in every state except Texas if you have employees. The rates are based on your industry classification code and your experience modification factor. A construction company with a bad claims history can pay nearly triple what a similar company with a clean record pays. This directly affects your payroll budget in a way most new business owners don't anticipate.
Get the Full Details

How to Actually Set This Up
If you are running payroll manually, you need an Employer Identification Number from the IRS, state withholding registrations in every state where you have employees, and a FUTA account. The registration process for state taxes alone can take two to four weeks depending on the state. Don't wait until your first payroll to start this. Begin at least a month before your first pay date. For most businesses below roughly 50 employees, using a dedicated payroll service like Gusto, ADP, or QuickBooks Payroll will save you significant time and reduce compliance risk. The software handles federal and state tax deposits, quarterly filings, and annual W-2 and 1099 generation automatically. The cost runs between $40 and $150 per month plus per-employee fees. Manual payroll might seem cheaper but the penalty risk makes it a false economy very quickly. One late deposit penalty can exceed a full year of software costs. Here is a nuance that trips people up repeatedly. Safe harbor relief exists for estimated tax payments and certain payroll tax deposits, but it has strict requirements. For federal income tax withholding, you can avoid penalties if you withhold at least 90 percent of the current year tax or 100 percent of the prior year tax. But this calculation gets complicated with variable pay, bonuses, and commission structures. Run this scenario through your payroll provider or a CPA before you rely on safe harbor, because getting it wrong means you are penalized on the underpayment amount plus interest calculated daily.
Annual reconciliation happens with Form 944 for small employers in some cases, but most employers file quarterly on 941. At year end you will produce W-2s for employees and 1099-NEC for contractors. The deadline for delivering W-2s to employees is January 31, and the filing deadline with the SSA is also January 31 if you file electronically. Paper filing gives you until February 28. Late filing penalties are $30 per form, rising to $110 per form if you file more than 30 days late, and up to $265 per form if filed after the prior year December 31. For a medium sized business with 40 employees, that is a meaningful amount of money if you miss the date.
When the System Doesn't Work
Payroll tax software will not save you from bad input. If you classify someone incorrectly, enter wrong wage types, or fail to update new hire information, the software will happily calculate and deposit the wrong amount. I once saw a company using a major payroll platform that auto-withheld federal taxes on reimbursements that should have been non-taxable. The system treated every payment to an employee as wages because the expense category wasn't properly mapped. They over-withheld by about $12,000 across the year and spent three months getting refunds processed. The fix was mapping reimbursement accounts correctly in the software, something that required a manual audit of every expense type they had ever used. Multi-state operations introduce a whole different layer of complexity. If you have employees working remotely from a different state than your business location, you generally need to register and withhold taxes in that employee's work state. Some states have reciprocal agreements that simplify this, but many don't. New York and New Jersey have particularly aggressive enforcement on this. I handled a case where a remote employee lived in Delaware but the employer was in New Jersey. The employer was only withholding New Jersey taxes. Delaware required withholding because the employee performed work there, and New Jersey required it because the employer was based there. The company was out of compliance in two states simultaneously, and the penalties compounded rather than overlapped. Local taxes are another blind spot. Cities like New York City, New York City has its own mandatory wage withholding that is separate from state and federal. Philadelphia, Pittsburgh, and San Francisco have local wage taxes. Some counties and school districts add small withholdings. If your payroll provider doesn't explicitly support your city or county, you may need to file and remit those separately. Check this before you sign up for any service.
The biggest limitation of any payroll tax guide or software system is that they cannot handle genuinely unusual situations. Layoff recalls, workers comp leave, union negotiations, tipped employee credit calculations, and fringe benefits like employer-paid health insurance all have special handling rules. General guidance won't cover these well. When your situation includes any of these, you need a CPA or payroll specialist who understands the specific interaction, not just a checklist from a website. The most practical approach is to treat payroll tax compliance as an ongoing process rather than a one-time setup. Review your deposit schedules annually, reconcile your quarterly filings against your general ledger before each deadline, keep a running log of any state or local registration changes, and set aside a budget for professional review at least once a year. The cost of a thorough annual check by a qualified professional is typically a fraction of what a single compliance mistake costs you in penalties and interest. Most good CPAs can catch issues that internal teams miss within the first hour of review because they have seen the same mistakes happen across hundreds of different businesses.