Why Student Financial Literacy Programs Are Usually Just Busy Work
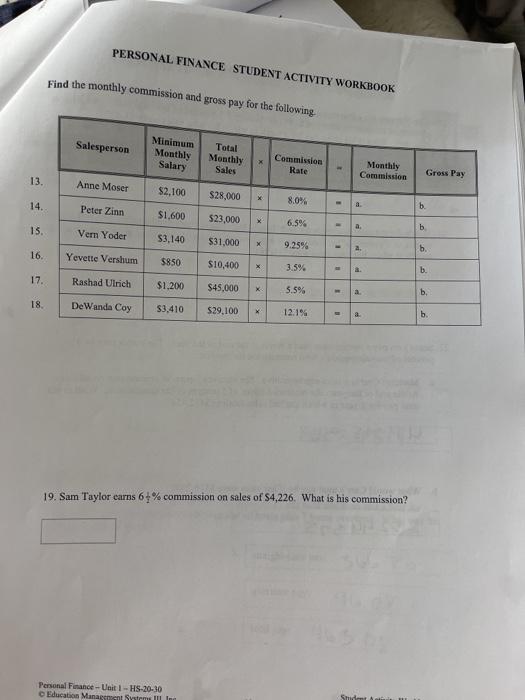
The Personal Finance Student Activity Guide Answera is what happens when a school district tries to ship a curriculum that covers budgeting, credit scores, and investing all in one semester. You will get workbooks, answer keys, rubrics, and a pile of handouts that most teachers end up ignoring after week three. I have graded the same spreadsheet templates for about eight years now. It gets old fast. The guide bundles a few core components. There is a student workbook that walks through monthly budgets, emergency funds, debt payoff strategies, and basic investing concepts. The answer key that comes with it is useful, but only if you are checking work quickly rather than using it as a teaching tool. There is also a set of project rubrics and occasionally a bank or credit union partnership that lets students open real accounts. The quality varies wildly depending on the publisher and the state standards it is trying to hit. Most districts use this program because it is turnkey. The lesson plans are there. The assessments are there. You do not have to write anything from scratch. The problem is that the material was written for a generic student who does not exist. A kid from a rural community with no access to investment apps needs something different than a kid in an urban area juggling two jobs and a car payment. The guide does not account for that gap.
I ran into this exact issue last spring when a student brought in her W-2 and asked how to file her first tax return. The workbook has a section on taxes, but it uses Form 1040EZ as the example, which was discontinued in 2018. I spent about twenty minutes pulling up the current version and walking her through Schedule 1 and the earned income credit. The guide never mentions that form has changed. The answer key just says "refer to IRS instructions." That is not helpful for a fourteen-year-old.
How to Actually Use This Program Without Losing Your Mind
The answer key exists so you can check student work without grading every spreadsheet by hand. Open it before you assign anything. Skip the problems that repeat the same concept six times in a row. I usually cut the workbook in half and assign the harder sections on weekends when students actually have time to think. The multiple choice quizzes are fine. The long-form projects are where things fall apart. The budgeting module is the one that works. Students fill out a monthly income and expense sheet, then adjust their spending to hit a savings goal. It takes about four class periods. The credit score section is where the guide starts lying to people. It presents the FICO model as a single fixed system when it is actually a family of scores that vary by lender and loan type. The rubric gives full credit for explaining "payment history matters." That is like giving full credit for saying water is wet. I made my students compare at least two credit scoring models and explain why their scores would differ between a mortgage lender and a car dealer. That single exercise took thirty minutes and taught more than the entire unit did. Investing is the weakest part of this program. The guide introduces compound interest with a savings account example and then immediately pivots to stocks without explaining risk, diversification, or expense ratios properly. The answer key for the investing quiz has the right numbers but uses rounded figures that do not match the actual calculators students will encounter. I switched to having them run everything through an online calculator and compare results. It added one period to the unit but fixed the accuracy problem entirely.
Get the Full Details

What the Guide Gets Wrong and How to Fix It Before Students Notice
Here is the thing nobody tells you about this program. The rubrics reward process over accuracy. A student who shows their work on a budget calculation but arrives at the wrong total will often get full credit if the steps look correct. Meanwhile, the kid who does the math in their head and writes a cleaner final answer sometimes gets marked down for not showing work. I stopped using the provided rubrics after the second semester. I built my own that weights the final number at sixty percent and the process at forty. It takes an extra hour to grade each set of papers, but it actually measures what matters. The debt payoff section has another hidden problem. It teaches the avalanche method as the default strategy, which is mathematically optimal but psychologically brutal for people who are already stressed about money. I flip the unit to present both methods and let students pick based on their personality type. The guide never suggests this option. The answer key just says avalanche is better. It is better on paper. It is not better for someone who owes $4,000 on a credit card at twenty-four percent and $12,000 in student loans at five percent and needs to see progress to stay motivated. Emergency fund coverage is another area where the guide oversimplifies. It recommends three to six months of expenses and treats that as a universal rule. I had a single parent student ask why she should save six months when she already had a roommate splitting rent and a family member who could cover groceries in a crisis. The guide does not have an answer for edge cases like that. I started assigning a risk assessment worksheet that factors in job stability, health insurance, family support networks, and income volatility before students decide on their emergency fund target. It changed the entire conversation in my classroom.
Download and Installation Notes
You can find the Personal Finance Student Activity Guide Answera through your state's educational resource portal or the publisher's website. Most districts already have a site license. If you are buying it yourself, expect to pay between eighty and one hundred twenty dollars for the complete package including the teacher edition and digital access codes. The answer key is included in the teacher bundle. Do not buy the student-only version unless you want to print your own answer sheets, which is a waste of time. The digital version requires a stable internet connection and a browser that supports modern PDF viewers. Some of the interactive budget worksheets will not load on Chromebooks older than two years. I ran into that last fall with a set of devices that had not been updated since 2021. The workaround was simple. I downloaded the worksheet templates as static PDFs and had students fill them out on paper instead. It removed the auto-grading feature but it also removed the technical frustration that was eating into class time. The paper copies took about ten minutes longer to grade each period. That is an acceptable trade-off. There is no mobile app for this program. The publisher sells a separate flashcard deck that works on phones, but it is not integrated with the main curriculum. The answer key is not available as a standalone download unless your district license includes it. If you lose the answer key, you can request a replacement from the publisher, but that usually takes two to three weeks. Print and laminate your copy. Keep it in a drawer. Do not rely on the digital version surviving a hard drive failure.
When This Program Is Not the Right Choice
If your students have severe math anxiety or inconsistent attendance, the workbook-heavy format will alienate them within the first month. I tried using this program with a hybrid class where half the students were online and the other half showed up in person. The pacing was impossible. The answer key does not account for different completion speeds. The projects assume everyone finishes the same sections on the same day. It did not work. I switched to a modular approach where students completed the budgeting and banking units together and then diverged into elective topics based on their individual progress. It took three extra days of planning per unit but the completion rate jumped from about sixty percent to roughly eighty-five percent. If you are teaching in a district with tight budget constraints and cannot afford the full package, the student workbook alone is not sufficient. The teacher edition contains the rubrics, differentiation strategies, and the extended project prompts that make the unit actually usable. Buying only the student copies leaves you with a folder of worksheets and no guidance on how to grade them. I have seen teachers try this. It looks good on paper and falls apart in practice. The program also assumes a minimum level of financial stability among students. Topics like retirement accounts, 401(k) matching, and index fund investing assume the reader has a job with benefits or at least a conceptual understanding of employment structures that many of my students lack. I supplement those sections with guest speakers from local credit unions and community organizations. The guide does not include these resources. They are not optional in a classroom where half the students are first-generation college bound and none of their families have discussed these topics at home.

The Personal Finance Student Activity Guide Answera is a starting point, not a complete solution. It gives you structure and saves you from writing everything from scratch, but it also means you will spend significant time adapting material that was written for a student population that does not match your own. The answer key is accurate for the problems it includes but silent on the real-world exceptions that come up when actual humans try to apply these concepts. Build your own rubrics, supplement the outdated tax forms, and treat the investing section as a scaffold rather than a finished lesson. Your students will learn more from the gaps you fill than from the content you hand them directly.