What a Personal Financial Planning Degree Actually Gets You
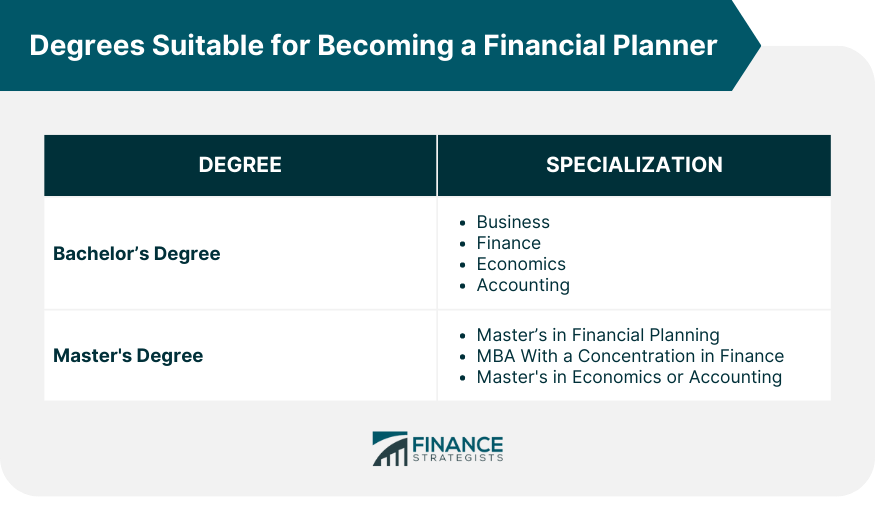
A personal financial planning degree is generally a business or finance program with a concentration in wealth management, retirement planning, tax strategy, and insurance. It is not a magic credential that lands you a six-figure job on day one. The programs vary wildly between schools. Some are tightly aligned with CFP Board certification requirements; most are not. I have hired people out of these programs and I have also had to retrain half of them before they could touch a client file. The first thing nobody tells you is that coursework and the certification exam live in different universes. A solid program will cover time value of money, estate law basics, risk management, and portfolio construction. That is useful. But covering those topics and passing the CFP exam require a different level of application. I learned this the hard way when a freshly graduated planner from a well-ranked program confidently recommended a Roth conversion strategy to a client with no current tax liability and no meaningful future liability either. The math worked in isolation. The holistic picture was wrong. The client would have locked away capital at a higher marginal rate for no reason. I spent two hours undoing it and explaining to the graduate why planning is not spreadsheet engineering. Most degrees structure the curriculum around five or six core areas: general financial planning principles, retirement planning, tax planning, investment planning, risk management and insurance, and estate planning. Some schools add a capstone where students build full financial plans for mock clients. That is the part that matters. Building a plan is different from solving end-of-chapter problems. You have to reconcile cash flow with tax brackets, coordinate beneficiary designations with trust language, and decide when to recommend annuities and when to walk away from them.
The practical side usually falls apart in two places. First, students treat tax planning as an afterthought instead of the spine of the plan. Second, they do not learn how to talk to clients who have messy real estate, complicated business ownership, or family dynamics that derail the best spreadsheets. I remember one student who produced a perfectly formatted retirement projection for a client who was actually living off a promissory note from a failed side business. The numbers looked clean. The income was fictional. The student did not catch it because the program never required a deep source-of-income audit. I made him redo the plan after we pulled six months of bank statements and traced every dollar.
Where These Programs Fall Short
The biggest gap is software proficiency. Academic programs teach concepts. They rarely teach you how to run a TAMP, pull account data through a platform like eMoney or MoneyGuidePro, or work with custodial reports from Fidelity, Schwab, and Vanguard simultaneously. You will also get very little training on the ethical boundary between advice and sales. Insurance and securities licensing are separate tracks. Some programs brush against them. Most do not prepare you to sit for the Series 65 or the state insurance producer exam. Another honest limitation is that degree prestige does not translate directly into client trust. When a person hires a financial planner, they care about certification, experience, and whether you can explain things without sounding like a textbook. A degree gets your resume past an HR screen at a medium-sized firm. It does not replace a CFP mark, an EA credential, or a solid record of handling real cases.
Get the Full Details
What I Would Do Differently If I Were Starting Over
Pick a program that explicitly maps its courses to CFP Board education requirements. Check the link on the CFP website before you enroll. Verify that the school has a dedicated financial planning lab or access to planning software. Ask what percentage of graduates pass the CFP exam on the first attempt. If the number is under forty percent, the program is probably not rigorous enough for certification prep. While you are in the program, get licensed. Take the series 65 if your state allows it through the degree pathway. Get your life and health license if insurance is part of your target market. Volunteer to build plans for pro bono clients through community organizations. Real clients expose you to gaps in your knowledge faster than any midterm. I had a client in her late sixties with a deferred annuity from 2008, a mesh of beneficiary designations that contradicted her will, and a long-term care policy she forgot she owned. The degree never covered that exact knot. Figuring it out took me three weeks of calling carriers, reading surrender schedules, and reconciling the estate documents. That experience taught me more than any elective did.
Common Pitfalls New Graduates Make
They over-index on investment allocation and under-index on behavior. A client who panics during a drawdown does not need a better Sharpe ratio. They need a plan they can stick to. They also assume tax planning is about minimizing current liability instead of managing marginal rate transitions across retirement, Social Security, and required minimum distributions. I have seen planners recommend aggressive Roth conversions to clients who would push themselves into a higher Medicare IRMAA bracket and lose more to premiums than they saved in taxes. Another mistake is ignoring the coordination between accounts. Traditional IRA, Roth IRA, taxable brokerage, and 401(k) withdrawals interact in ways that are not obvious until you model several years of distribution. I built a simple withdrawal sequence model that ranked buckets by their marginal tax cost each year, adjusted for state residency changes and Medicare thresholds. It cut my plan preparation time from about ninety minutes to roughly twenty-five minutes per client while improving accuracy. You can replicate something similar with basic Excel or a low-cost planning tool if your firm does not provide one.
Is the Investment Worth It
If your goal is to become a certified planner and work at a registered investment adviser, a targeted degree is a reasonable foundation, especially when combined with licensing and hands-on experience. If your goal is to manage your own finances or consult occasionally, the formal degree is overkill. You can reach competent personal financial planning through self-study, the CFP exam prep courses, and reading primary sources like the Internal Revenue Code and state probate statutes. The honest answer is that the degree opens doors but does not walk them for you. The planning profession rewards people who can handle edge cases, communicate clearly, and stay current on tax law changes. I have seen people with no degree succeed in those areas and I have seen graduates struggle because they treated planning as a theoretical exercise instead of a practice built on documentation, client interviews, and iterative modeling.

.png "Financial Planning Degree Australia at Kendra Mayes blog")