Most People Build These Wrong From Day One
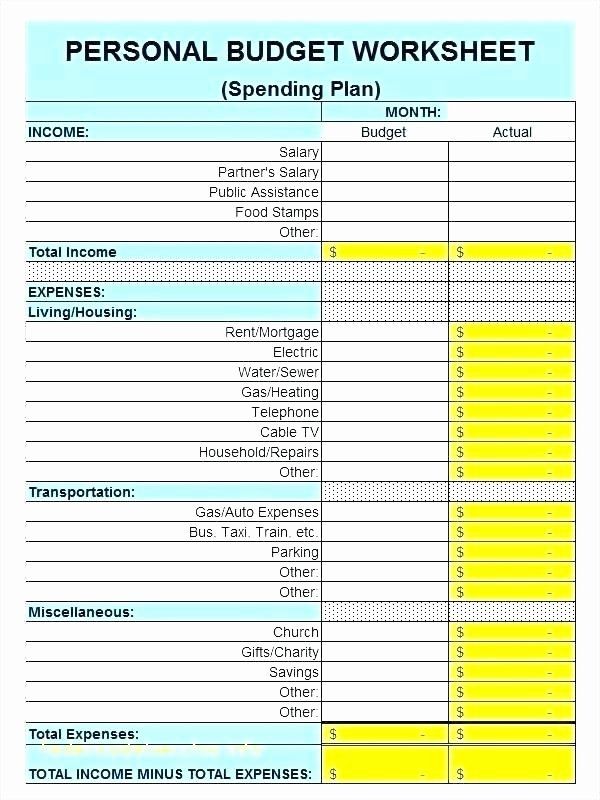
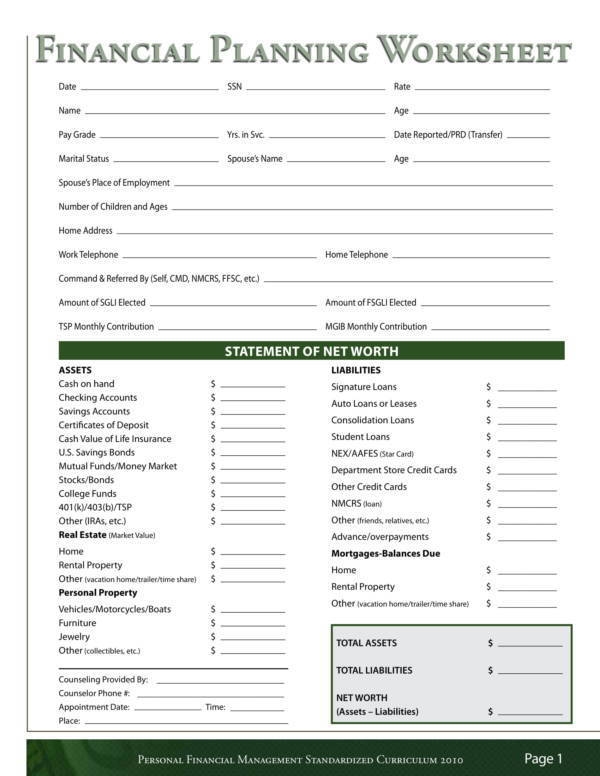
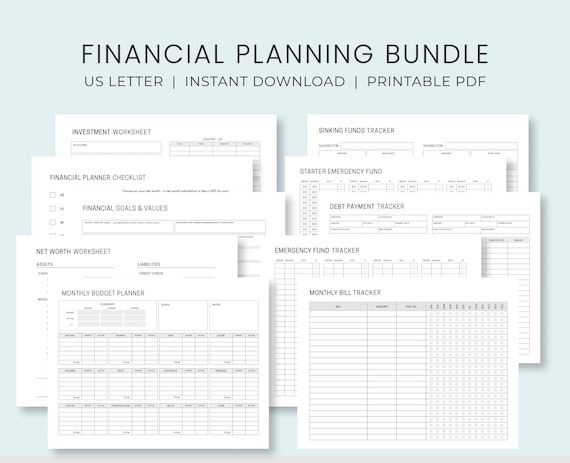
I used to spend two days per client hand-holding them through spreadsheet setup before we ever got to the actual numbers. The reason was simple: they always mixed up cash flow timing, double-counted expenses, and then wondered why the balance sheet didn't reconcile. A proper set of Personal Financial Planning Worksheets is really just four interconnected sheets that force you to admit what's actually happening with your money instead of what you assume is happening. Start with a Net Worth statement. Not a budget. Net worth. You need to know your total assets minus total liabilities as a baseline before you track anything monthly. Most beginners skip this and go straight into expense tracking, which means they never actually see the structural picture. Put your checking, savings, investment, and retirement accounts in one column. List every debt—mortgage, student loans, credit cards, car loans—in another. The difference is your starting net worth. If it's negative, write it down. Don't edit it to look better. Next build a cash flow tracker. This is where people mess up most often. You need two sections: income and expenses. Income should only include take-home pay after taxes and deductions. Gross income is useless here because you can't spend what the government takes first. Expenses get split into fixed and variable. Fixed includes rent, car payments, insurance premiums, minimum debt payments—things that stay the same or are locked in by contract. Variable is groceries, dining, utilities that fluctuate, entertainment, anything you can control month to month. I've seen people classify their internet bill as fixed when it changes every year with promotional rates ending. Classify it correctly and note the renewal date so you're not blindsided.
Then create a budget sheet that pulls from the cash flow data. This isn't a separate exercise. Your budget should auto-calculate based on the categories you set up in the tracker. If you're manually typing budget numbers while also tracking actual spending, you're going to abandon the system within three months. Use SUMIF formulas to pull category totals from your expense log into a budget comparison view. Show planned versus actual side by side with a variance column. When a category goes over by more than ten percent, that's your signal to investigate, not panic. The fourth sheet is a debt payoff planner. List every debt with its balance, interest rate, minimum payment, and extra payment amount. Use the debt avalanche method if you want to minimize total interest paid—the highest rate first. Use the debt snowball if you need behavioral wins to stay motivated. There's no universal right answer. A client of mine had a $4,200 credit card at 24.9 percent and a $18,000 student loan at 5.2 percent. She wanted to tackle the student loan first because it was larger. I ran both scenarios. She'd save $1,847 in interest going avalanche but would need eleven months of consistent snowball payments before seeing her first payoff. She chose avalanche. It took her fourteen months to pay off the card and she was stressed the whole time but she stuck with it. Method matters less than adherence. One thing nobody tells you about these worksheets: they need a maintenance ritual. I recommend a fifteen-minute weekly review where you input that week's transactions and check variances against your budget. Set a recurring calendar alert. If you wait until the end of the month to catch up, you'll skip weeks and then just give up entirely. Fifteen minutes every week keeps the data fresh without making it feel like a chore. The alternative is letting it pile up for sixty days and then spending four hours trying to reconstruct transactions from memory.
Here's a specific edge case that nearly broke a client's plan last year. She had irregular income from freelance work—some months $8,000, some months $1,200. Standard budgeting formulas completely failed because they assumed even monthly cash flow. What I did was calculate her average monthly income across the trailing twelve months, then budget conservatively to that lower number. Any month above that became a surplus category that rolled into a buffer fund. After six months she had enough in the buffer to cover her lowest earning months. Without that adjustment she would have been in the red every third month and stopped using the system altogether. The real limitation of these worksheets is that they only work if you commit to updating them. A blank or stale spreadsheet is worse than no spreadsheet because it gives you a false sense of control. There are tools now that sync directly with bank accounts and import transactions automatically. If you hate manual entry, use a tool like Monarch Money or YNAB. But even automated tools need human categorization and judgment calls that software still can't make reliably. Another counter-intuitive point: your worksheets should include non-monthly expenses as separate line items. Car registration, property taxes, annual subscriptions, holiday gifts. If you don't pre-fund these, they'll blow up your cash flow whenever they hit. Divide the annual cost by twelve and treat that portion each month as a real expense. It's called sinking funds and it's the single most effective technique for preventing budget failures.
Get the Full Details

If your situation involves business income, rental properties, or significant investment portfolios, these worksheets get more complicated. At that point you probably want a professional to help set up the structure. The basics still apply but the interaction between different income streams and tax implications requires knowledge most DIY systems don't handle.