Putting Your Financial House in Order
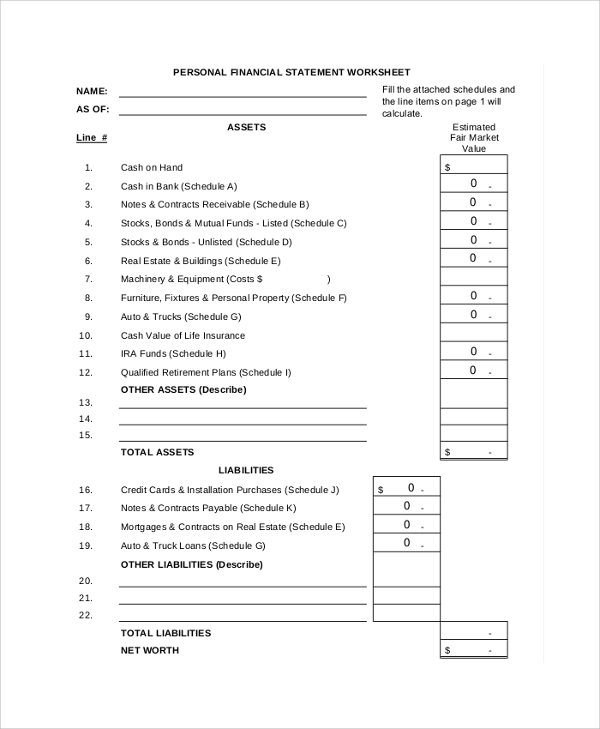
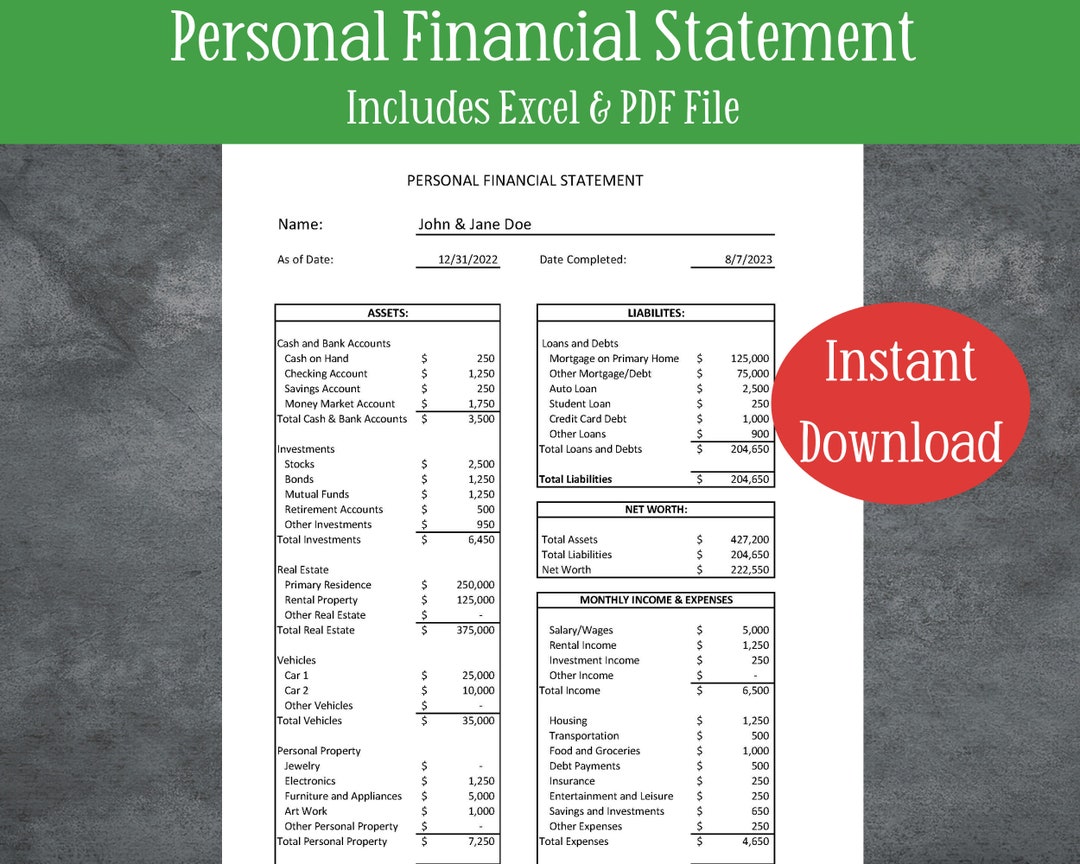
A Personal Financial Statement Worksheet is a structured document that lays out everything you own and everything you owe on a single page. Lenders use it when you apply for a loan, refinancing, or investment credit. It is the snapshot they trust more than any resume or verbal pitch. The worksheet has two sections. The first lists your assets by category: cash accounts, brokerage holdings, real estate at current market value, vehicles, jewelry, art, business interests. The second lists liabilities: mortgages, home equity lines, credit cards, auto loans, personal loans, anything owed to family that you have not documented elsewhere. I learned the hard way that lenders do not accept your purchase price for real estate. They want current market value, which means a quick Zestimate or a recent appraisal. One time I listed a property at what I paid in 2018, and the underwriter flagged it and asked for a new appraisal. That added three weeks to the closing. I stopped doing that after.
Cash and savings go at the top because they are easiest to verify. Investment accounts come next. Real estate is last among assets because the valuation is the most likely point of contention. On the liability side, minimum monthly payments matter more than the original loan amount. A lender needs to know your actual monthly obligation, not just that the loan exists. The net worth calculation is straightforward subtraction. Total assets minus total liabilities. The number that comes out tells the lender whether you have skin in the game. A negative number does not automatically disqualify you, but it changes the conversation. I once saw a self-employed consultant with a negative net worth get approved because her debt-to-income ratio was under 36 percent and she had two years of documented profit on Schedule C.
What Lenders Actually Look For
There are two numbers that carry the most weight. The first is your liquidity ratio, which is cash and liquid investments divided by monthly obligations. If you have six months of expenses covered in easily accessible accounts, you look stable. The second is your leverage ratio, which measures total debt against total assets. Below 50 percent is comfortable. Between 50 and 75 percent is where conversations get tense. Above 75 percent usually triggers additional documentation requirements. One thing most people miss is the treatment of retirement accounts. 401(k) and IRA balances count as assets, but lenders typically apply a haircut of 70 to 80 percent because you cannot access them without penalty before retirement age. I recommend listing the full balance but noting the restricted access. The underwriter will apply the haircut themselves if you do not mention it, and sometimes they apply it more aggressively than necessary. Another nuance involves co-owned assets. If your name is on a joint account with a sibling or parent, list the full balance but mark it as non-exclusive. Lenders will prorate it to your share unless you have documentation showing otherwise. I had a client who listed a joint savings account at 100 percent, and the underwriter assumed he owned half. When he later needed to prove full ownership for a down payment contribution, the mismatch created a gap in the paper trail that delayed funding by ten days.
Get the Full Details

Common Mistakes That Slow Things Down
The biggest error is inconsistency between the worksheet and supporting documents. If you list a credit card balance of 4,200 dollars but your most recent statement shows 3,891, the underwriter will ask for an explanation. Every number on the sheet should have a corresponding document ready within five minutes. I keep a folder organized by account name with the latest statement for each one. This usually cuts the processing delay from several days to a single email exchange. Another frequent mistake is omitting contingent liabilities. If you co-signed a loan for a friend or family member, that obligation belongs on the worksheet even if you are not the primary payer. I once missed listing a brother's student loan co-signature, and the lender found it during a routine credit pull. That triggered a manual review that added five business days. Lenders can see co-signed debts on your credit report, so hiding them does not work. Valuation errors on illiquid assets are the third common problem. Art, collectibles, and privately held business interests require third-party appraisals if they exceed a certain threshold, usually 25,000 dollars per item. Without an appraisal, the lender may value them at zero. I learned this when a client listed a vintage guitar collection at what he thought was fair market value, and the underwriter wrote off 18,000 dollars because no appraisal was provided. Getting a qualified appraiser for that collection cost about 800 dollars but saved him the entire denial risk.
When a Worksheet Is Not Enough
Some situations require more than a standard Personal Financial Statement Worksheet. Self-employed borrowers with irregular income usually need profit and loss statements, tax returns, and sometimes a cash flow analysis prepared by a CPA. A gig worker with income spread across four platforms will face the same requirement. The worksheet is a starting point, not the final document in the package. International assets introduce a different set of problems. Property in another country, foreign bank accounts, or overseas investments often require translated documentation and currency conversion at the Federal Reserve rate on a specific date. I had a client with a condominium in Mexico who brought a purchase receipt in pesos, and the lender asked for a current conversion plus a local appraisal in English. The process took six weeks because the Mexican appraisal company had limited familiarity with U.S. underwriting standards. If your financial situation involves ongoing litigation, disputed debts, or assets held in trust, the standard worksheet format will not capture the complexity. In those cases, working with a financial advisor or attorney to prepare a supplemental narrative alongside the worksheet is usually the only reliable path. The worksheet itself is designed for straightforward situations, and stretching it beyond its intended scope tends to produce more questions than answers.