Reading Loan Disclosures Before You Sign
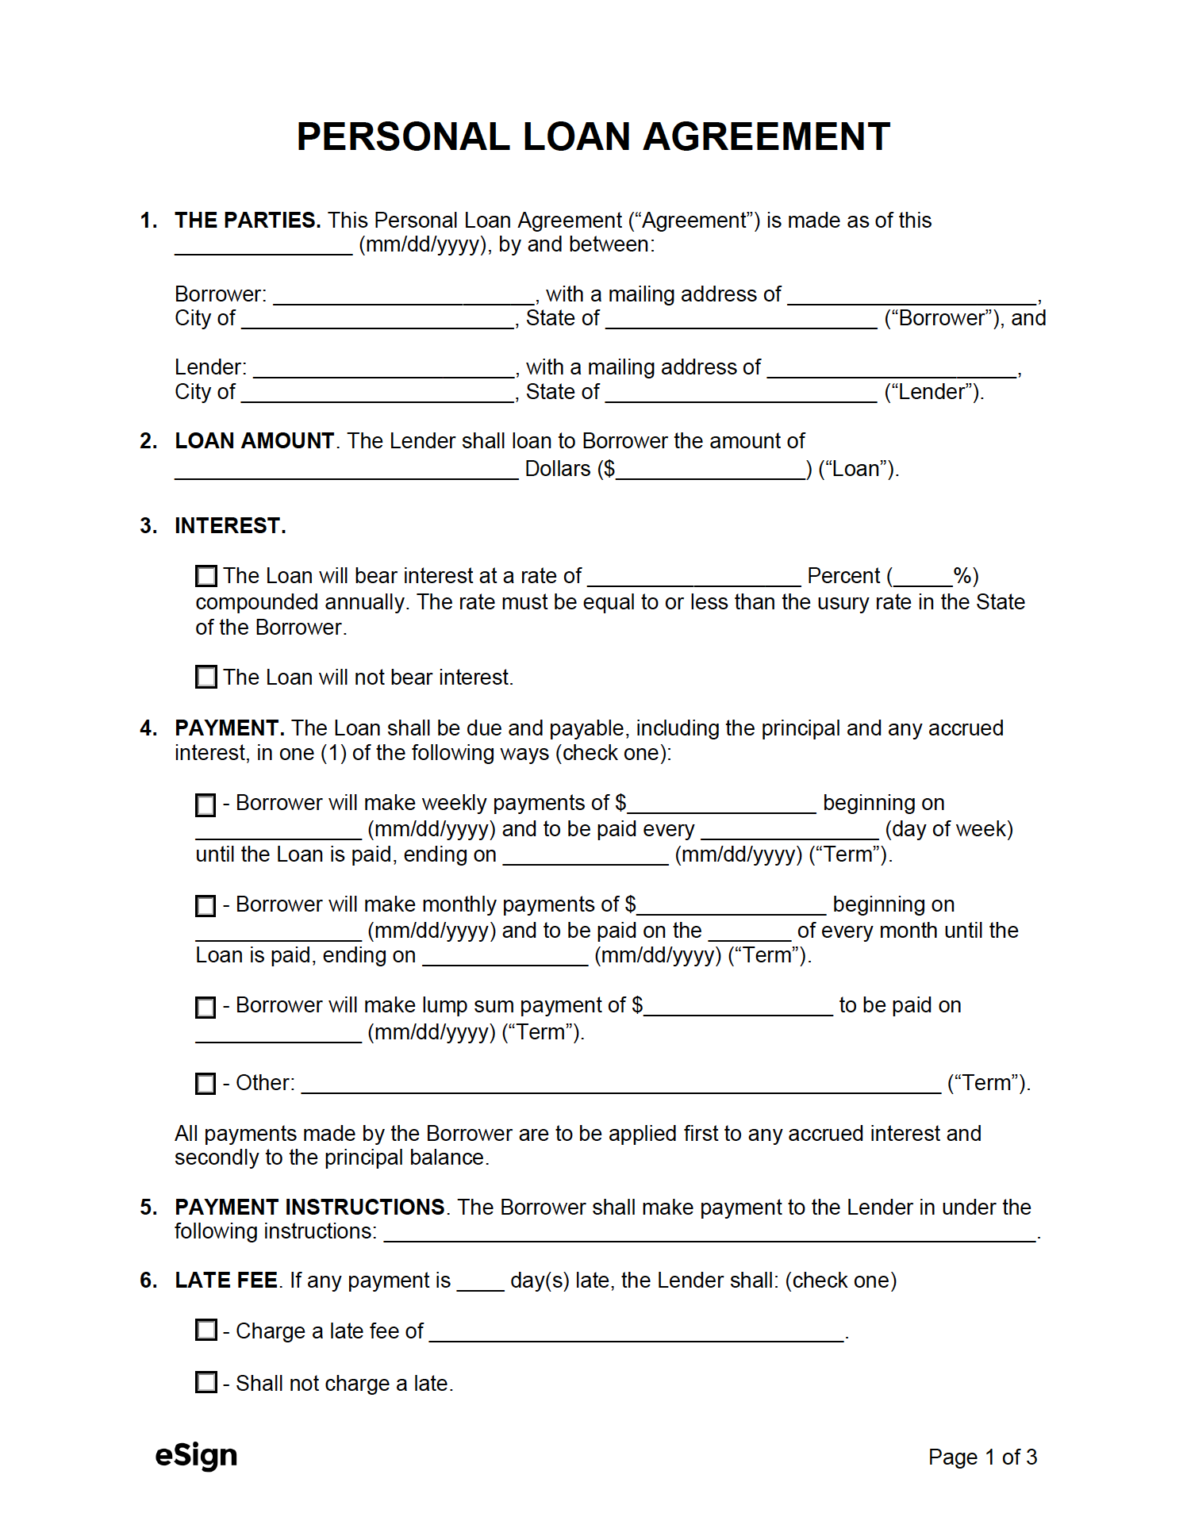
Most people skip the terms document. They look at the monthly payment, compare it to their budget, and sign. That is where the mistake happens. The monthly payment is just the tip of the structure. The actual cost of borrowing is hidden in the fine print, scattered across pages of language designed to be unreadable. I have watched people get burned by prepayment penalties they did not know existed. One borrower I worked with had a 36-month loan with a declining fee schedule — the first two years, 3% on any early payoff; after that, it dropped to 1%. She paid it off in month fourteen and ended up paying nearly $400 extra just because nobody explained how the structure worked. She asked me about it two days after the fact. By then, the paperwork was already filed.Personal Loan Terms Breakdown
APR vs. interest rate — these are not the same thing and lenders know you will confuse them. The interest rate is what you pay on the principal balance. The APR includes the interest rate plus any fees the lender charges, expressed as an annual percentage. If a loan has a 7% interest rate but a $200 origination fee, the APR will be higher. Always compare APRs, not rates. The difference matters more on shorter loans because fees get amortized over fewer months. Origination fees — this is the most common way lenders make money beyond interest. It is typically 1% to 8% of the loan amount and gets deducted upfront. A $10,000 loan at 6% origination means you receive $9,400 but owe $10,000 plus interest on $10,000. That changes your effective cost significantly. Some lenders embed the fee into the payment structure instead of deducting it, which is less transparent but functionally the same. Prepayment penalties — not all loans allow you to pay early without a fee. This is more common with subprime or near-prime lenders. Credit unions generally do not charge them. The penalty structure varies: flat dollar amount, percentage of remaining balance, or a set number of months of interest. You need to find this clause before you sign. It is usually buried under " borrower obligations" or "early termination." In my experience, it takes about 45 seconds to scan for "prepayment," "early payoff," or "yield maintenance" on page twelve of a thirty-page disclosure.
Payment frequency options — most lenders offer biweekly or monthly payments. Biweekly sounds like it saves you money because you make twenty-six half-payments per year instead of twelve full ones. You end up making one extra monthly payment annually. That does reduce total interest, but only if the lender applies payments to principal immediately. Some lenders process biweekly payments as just another scheduling preference and still apply them monthly. Call the servicing department and ask directly. Get it in writing if they claim it does anything different. Debt service ratio impact — once you take out a personal loan, it shows up on your credit report as an installment loan. That affects your debt-to-income ratio, which matters if you are applying for a mortgage within the next six months. Lenders look at your DTI at closing, and a new personal loan can push you over a threshold. I had a client who took a $15,000 loan for home improvements while pre-approving for a mortgage. The loan was still on his report two months later and the underwriter flagged it. He had to get a payoff letter and proof of zero balance before they would re-evaluate his application. It added eleven days to closing. Grace periods and late payment terms — most loans give you a fifteen to thirty-day grace period before a late fee hits and before the delinquency is reported to credit bureaus. But the exact window varies by lender. One lender I dealt with had a ten-day grace period and charged a $35 late fee plus a 5% increase on the interest rate for sixty days after the first missed payment. That rate bump is called a default rate trigger and it can cost you hundreds if you are already struggling. Another lender reported late payments after just five days. Five days. Check this before you commit, especially if your income is irregular.
The Actual Process of Shopping Around
Get prequalified first. Most lenders offer soft credit pulls for prequalification, which do not affect your score. You submit basic information — income, employment, desired amount — and they give you a rate range. This takes about three minutes per lender. Do this with at least four to five lenders before you apply for anything real. Hard credit pulls show up on your report and stay for two years. Multiple pulls within a short window, usually fourteen to forty-five days depending on the scoring model, get counted as a single inquiry for scoring purposes. That window matters. Spread your applications out too much and you look desperate. Bunch them too tightly and some scoring models may still treat them as separate events. Compare the total cost, not the monthly payment. A lower payment often means a longer term or a higher rate. I ran the numbers on a loan recently where one offer had a $295 monthly payment at 9.5% for sixty months and another had a $310 monthly payment at 7.2% for forty-eight months. The first looked cheaper month to month, but the total cost was $17,700 versus $14,880. The difference was over two thousand dollars. The borrower almost picked the wrong one. Read the Truth in Lending disclosure. Federal law requires lenders to provide this before you sign. It lays out the finance charge, the APR, the total of payments, and the amount financed in a standardized format. It is boring to read but it is the only document that lets you compare two loans on identical terms. If a lender refuses to provide it or delays it, walk away. That is a red flag for the entire business practice.
Get the Full Details
Watch for balloon payments. Some personal loans, particularly from non-traditional lenders, have a large final payment that makes the earlier months affordable. This is common in asset-based lending but shows up in personal loans too. A $20,000 loan with a $500 monthly payment for twenty-three months and a $12,000 final payment looks easy until month twenty-four arrives. These are rarely advertised prominently. The balloon payment is listed in the amortization schedule, which most people never look at.
When Personal Loans Are the Wrong Tool
They are expensive compared to secured options. If you have a credit score above 700 and need money for a car or home repair, a secured loan or home equity product will almost always be cheaper. Personal loan rates for good credit currently sit around 8% to 15% APR. A HELOC at the same credit tier might be 6% to 9%. The difference is real money over time. Personal loans make sense when you do not have collateral, when you need speed, or when the amount is small enough that the rate premium is manageable. They do not make sense as a long-term financing strategy for large amounts. Cash advance alternatives exist that are cheaper. A 0% APR balance transfer credit card can work for debt consolidation if you can pay it off within the promotional period. A 401k loan from your employer carries no interest — you pay interest to yourself. Neither option is perfect, but they beat a 18% personal loan if your situation allows them. Some lenders target borrowers with thin credit files and charge rates that exceed 25% APR. These are functionally predatory even if they are technically legal in your state. The monthly payment might look reasonable on a small balance, but the total cost destroys you. I advised someone last year who had a $3,000 loan at 27% APR with a thirty-six-month term. She was paying $122 per month. She paid $1,500 in interest over the life of the loan — half the original amount. She qualified for a credit union loan at 11% the next month once she stopped applying elsewhere and gave them time to recover her score. The rate difference would have saved her about $800. She did not know that was an option because no one told her.
The worst part about bad loan terms is that they compound. You miss a payment, a late fee hits, your rate goes up, your payment goes up, you miss another payment. It is a spiral and it is very easy to enter. The single most important thing you can do before signing is read the section on default and remediation. It tells you exactly what happens if you cannot pay. Knowing that in advance changes how you plan for the worst case.