Working With the Phillips Curve In Practice
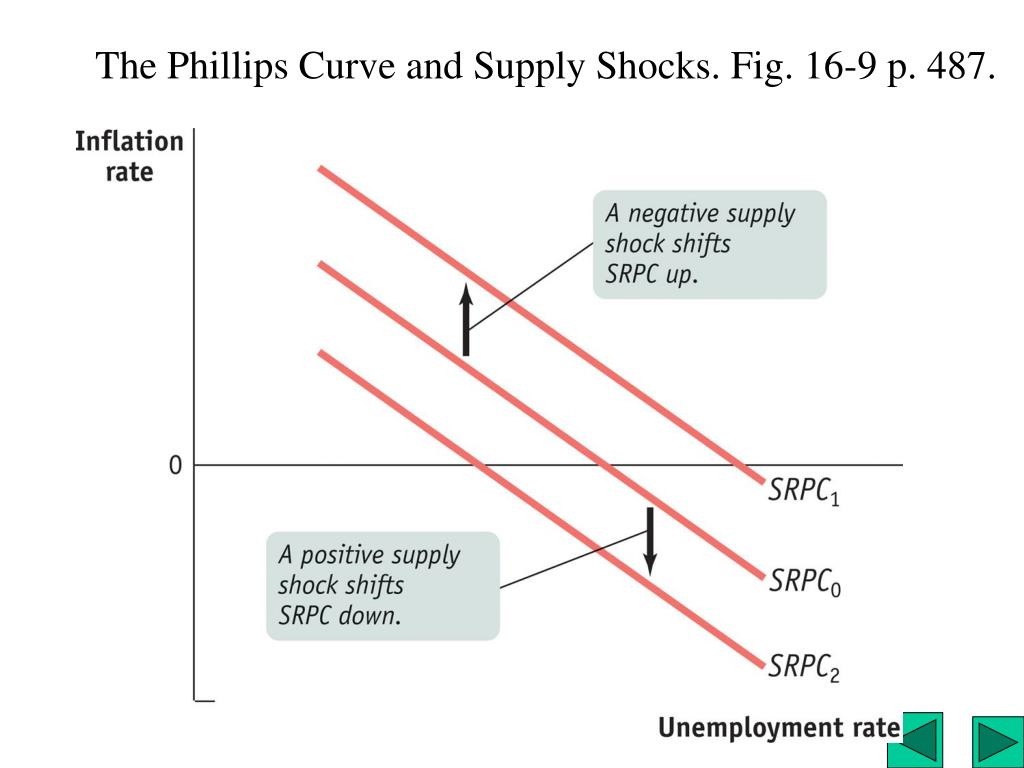
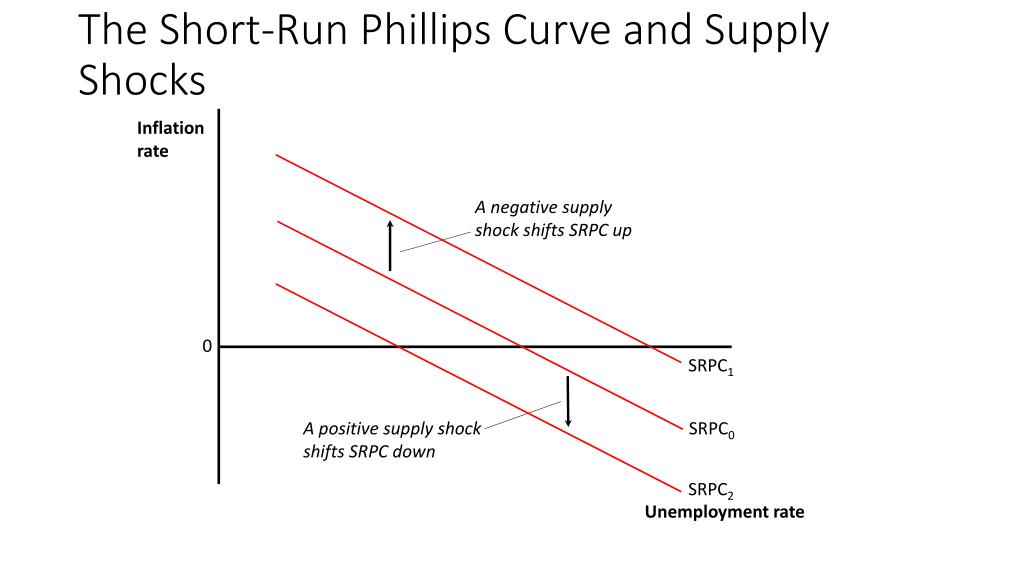
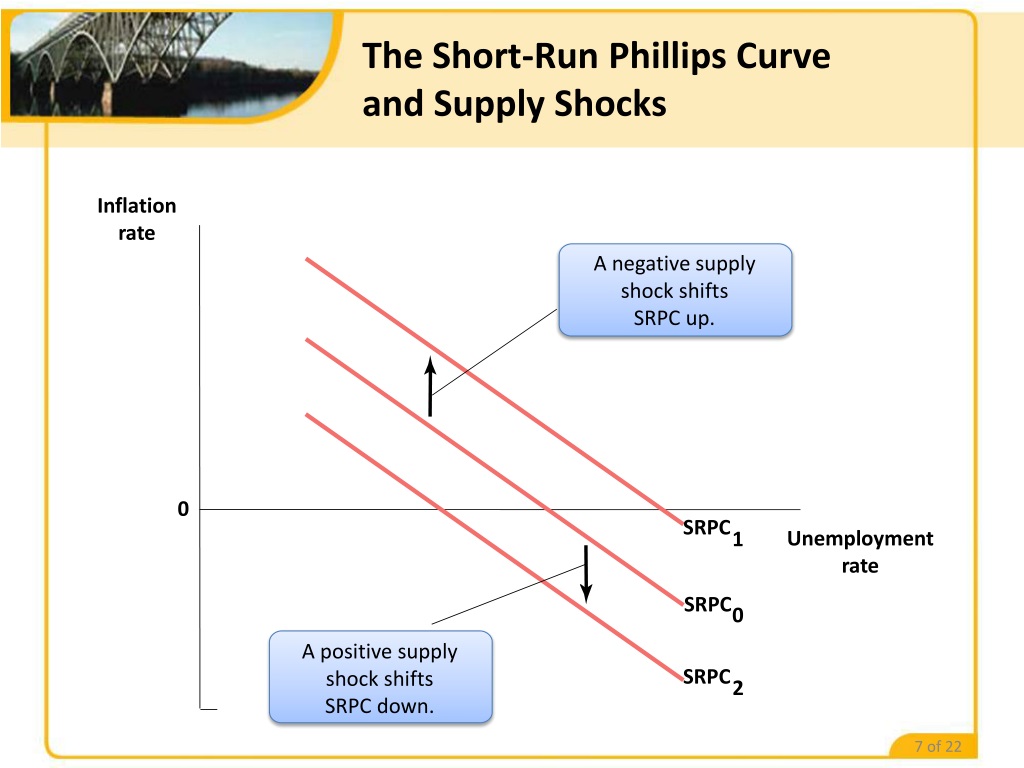
The Phillips Curve shows a relationship between inflation and unemployment. That's the basic version taught in every econ 101 class. The curve slopes downward when you're looking at demand-pull inflation, and it shifts when supply shocks hit the economy. Most people stop there. I spent years actually trying to use this framework for policy decisions and forecasts, and it turns out the theory is much messier than the textbook diagram suggests. Demand-pull inflation happens when aggregate demand outpaces what the economy can produce at full employment. You get more money chasing fewer goods. Unemployment drops because firms hire more workers to meet that demand. That's the downward movement along the curve. Supply shock inflation is different. It moves the whole curve. A sudden oil price spike in the 1970s is the classic example. Costs go up across the board, prices rise, and unemployment climbs at the same time. You get stagflation, which the original Phillips Curve couldn't explain at all.
Phillips Curve Demand Pull And Supply Shock
When I was building forecasts for a regional development bank, I had to model inflation expectations for a country going through a commodity boom. The standard Phillips Curve approach kept breaking down. Here's what I ran into: the curve appeared to flatten significantly during the mid-2000s. Inflation stayed low even as unemployment dropped below what economists considered the natural rate. Everyone at the bank thought the Phillips Curve had died. It hadn't. What was happening was that inflation expectations had become well-anchored through credible central bank communication, which essentially decoupled the short-term relationship between unemployment and price pressure. The workaround I used was to stop treating the Phillips Curve as a stable empirical relationship and start treating it as a conditional framework. I added an expectations-augmented term, measured expected inflation using breakeven bond spreads and survey data, and then layered in a supply shock variable using commodity price indices. This approach gave me forecasts that were only marginally better than a naive persistence model, but it was honest about the uncertainty. The standard unadjusted Phillips Curve would have told me inflation was going to explode that year. It didn't come close. Here's something most introductory materials skip over. The slope of the Phillips Curve isn't constant across business cycles. It tends to be steeper during recessions and flatter during expansions. When the economy has spare capacity, a small boost in demand can push unemployment down quickly without generating much inflation pressure. When you're near full employment, the same demand boost gets absorbed mostly through rising prices rather than additional hiring. This asymmetry matters a lot if you're trying to calibrate a model for policy advice. Using an average slope across all conditions will give you misleading results half the time.
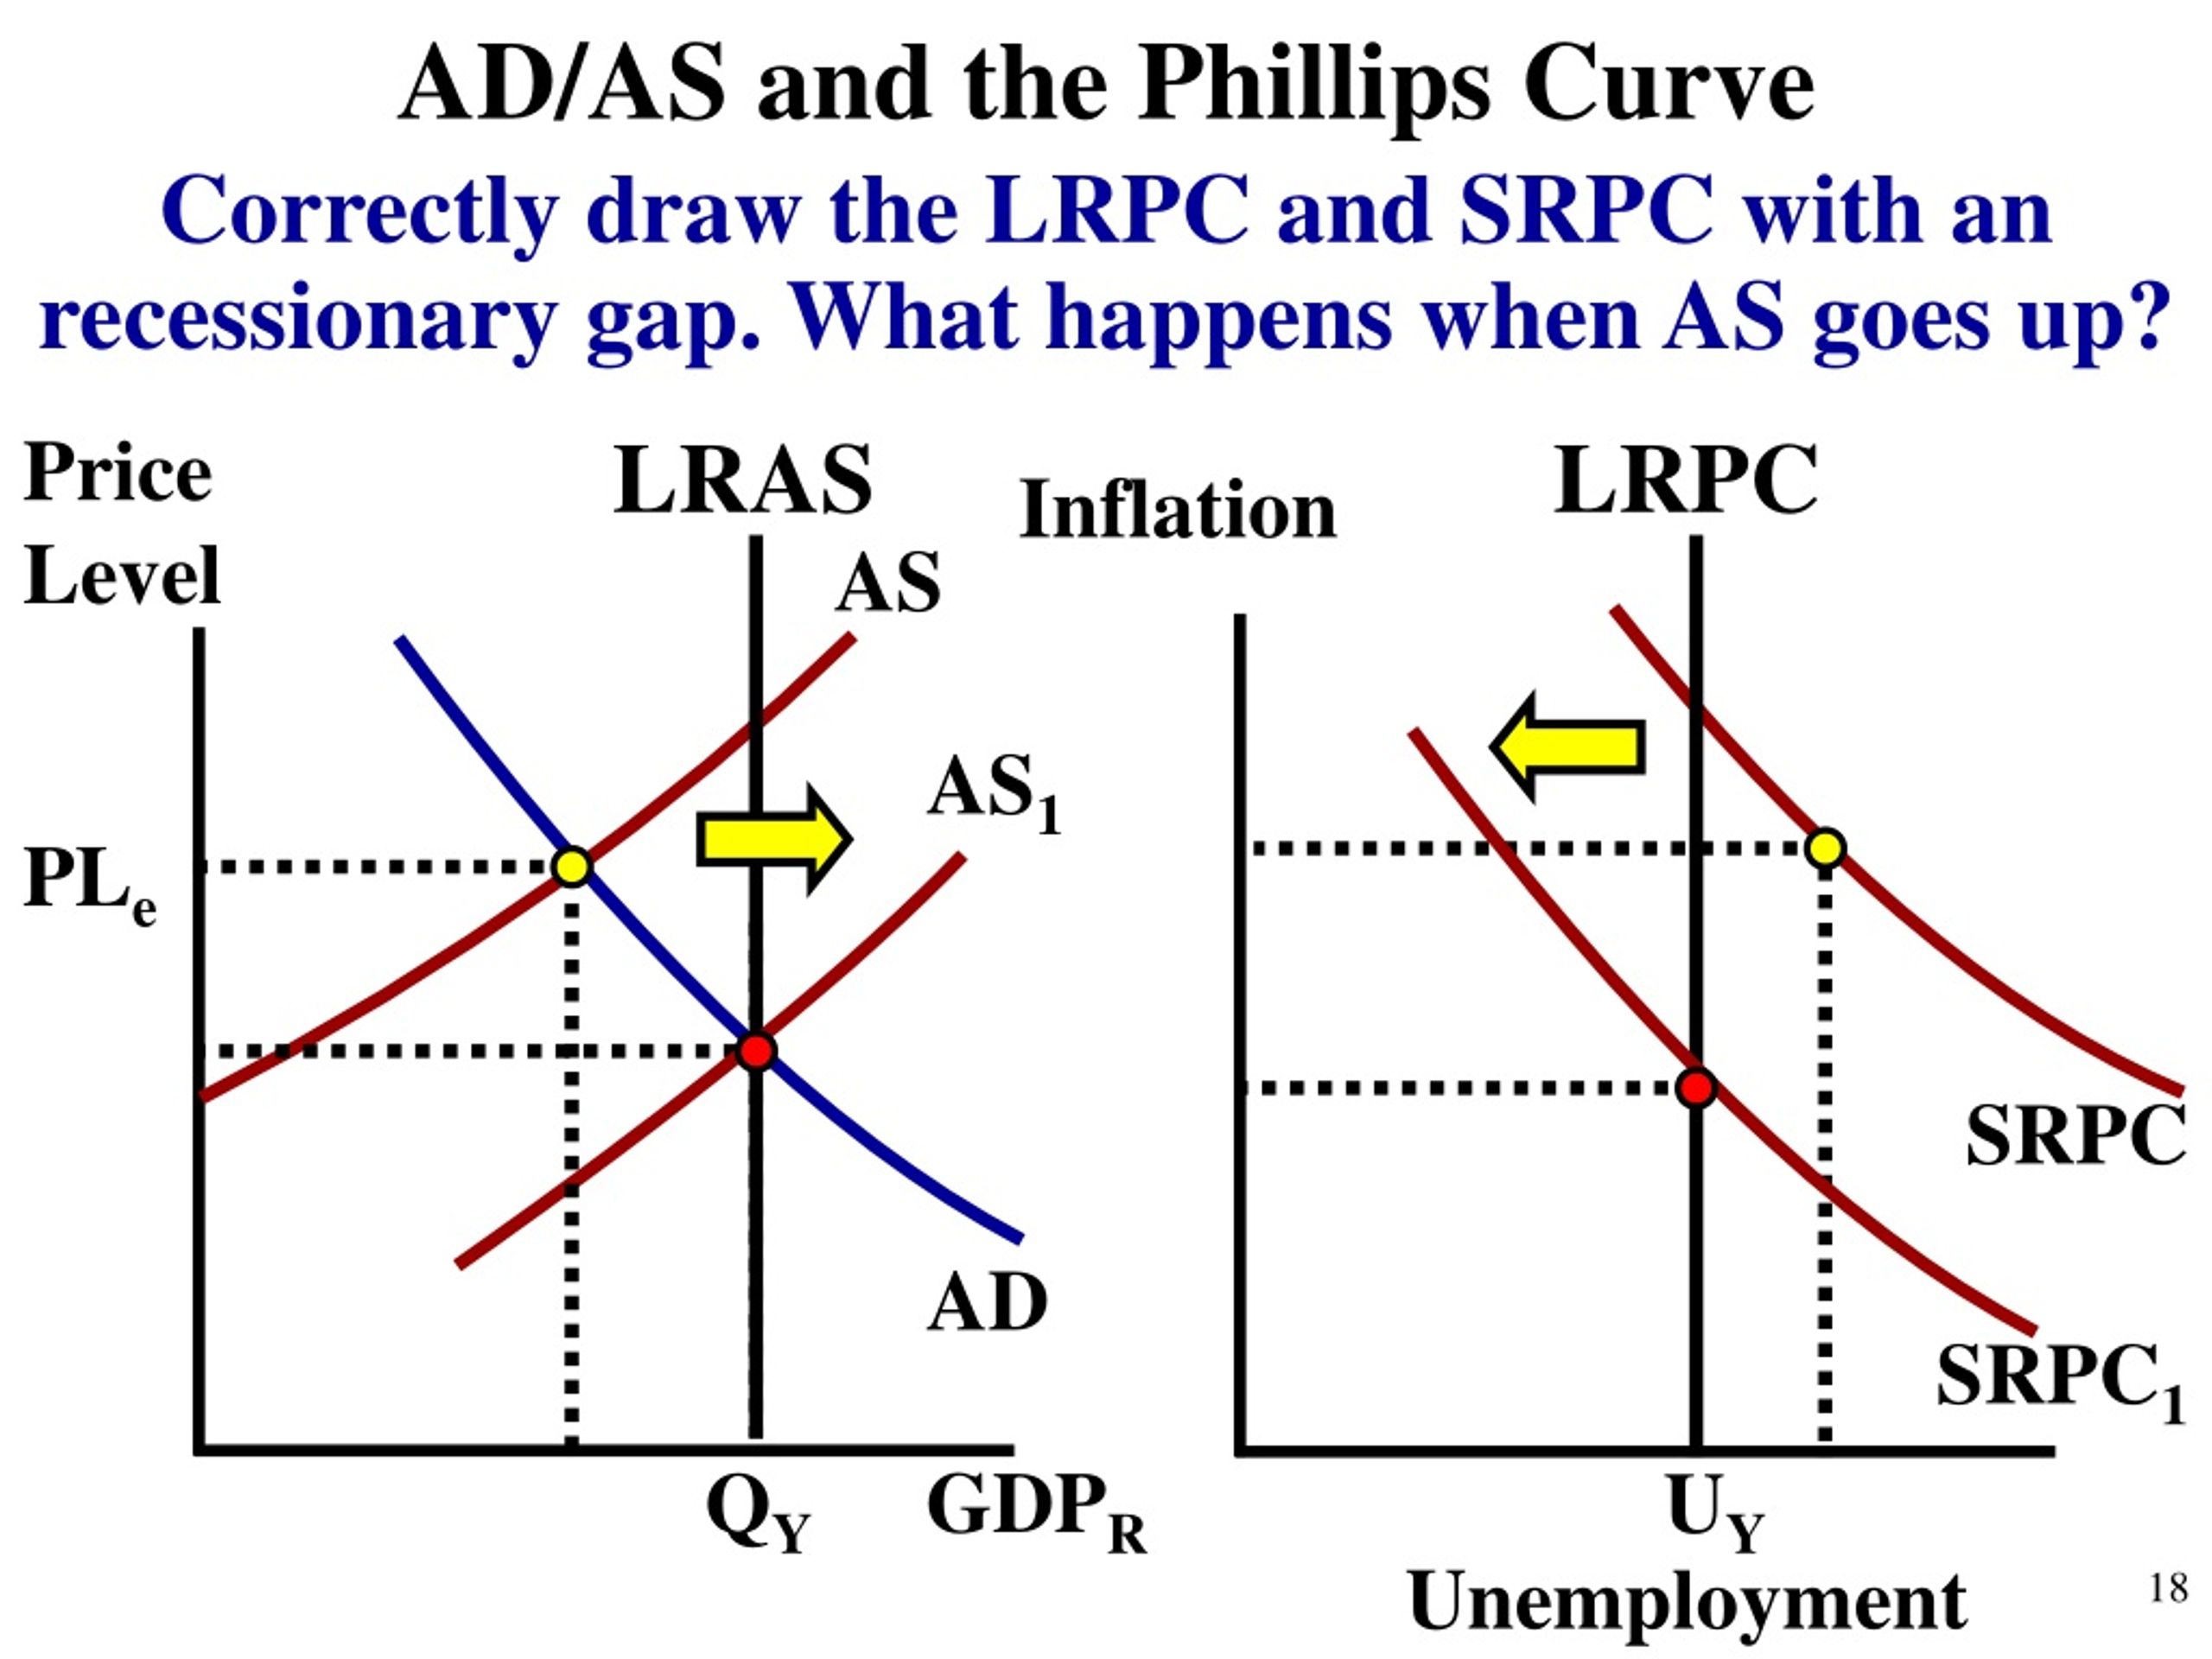
Another thing that trips people up is the distinction between the short-run and long-run Phillips Curve. The short-run curve slopes downward because wages and prices are sticky in the near term. Workers don't immediately adjust their expectations when monetary policy changes. The long-run curve is vertical at the natural rate of unemployment, meaning monetary policy can't permanently lower unemployment through demand management. It only creates inflation. The adjustment period between those two states is where most of the real-world confusion lives. Central banks spend most of their time operating in that transition zone, guessing how long stickiness will last before expectations fully adjust. I've seen analysts make a particular mistake when dealing with supply shocks. They treat the shift in the Phillips Curve as a one-time event and then revert to the original curve. But supply shocks often change the structure of the economy. If an energy crisis makes production more expensive permanently, the natural rate of unemployment may shift upward. Firms restructure, some industries contract, and the old relationship between inflation and labor market slack no longer applies. The curve doesn't just move back. It moves to a new position. Ignoring this structural dimension has led to underestimated inflation risks in several emerging markets I've worked with. The main limitation everyone ignores is that the Phillips Curve requires reliable data on both inflation and unemployment, and in many developing economies neither measure is particularly trustworthy. Survey-based inflation expectations are often collected infrequently and with questionable methodology. Unemployment figures in countries with large informal sectors miss a huge chunk of the labor market. When you're feeding garbage data into a Phillips Curve model, the output looks precise but it isn't. I learned this the hard way when a client asked me to produce a point estimate for next year's inflation using only officially published data for a Southeast Asian country. The model spat out 4.2 percent. Actual inflation came in at 7.8 percent the following year. The gap wasn't a model failure. It was a data failure.
Get the Full Details
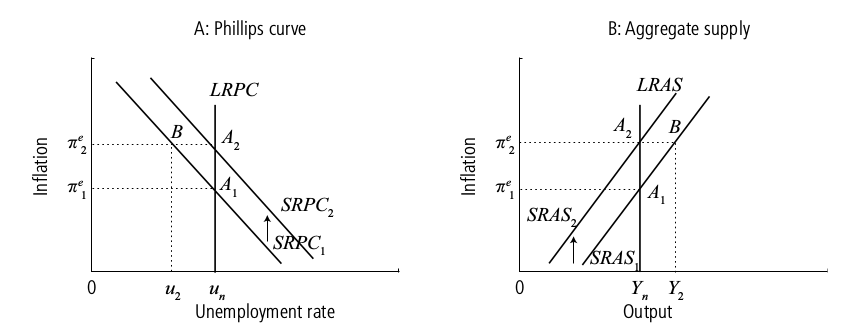
If you need to work with this framework in a context where data quality is weak, the better approach is to use nowcasting methods that incorporate high-frequency indicators like retail sales, import volumes, and exchange rate movements. These tend to be more current and less subject to revision than official unemployment series. Combine those with a flexible Phillips Curve specification that allows the slope to vary with economic conditions, and you'll get something closer to useful than what a standard static model produces. The Phillips Curve remains a useful starting point for thinking about inflation dynamics, but treating it as a reliable forecasting tool without adjusting for anchored expectations, asymmetric slopes, and structural breaks from supply shocks is a fast way to generate confident but wrong predictions. The demand-pull and supply-shock versions describe different mechanisms entirely. Understanding which one is operating in any given period is the harder part, and the model choice depends on that diagnosis.