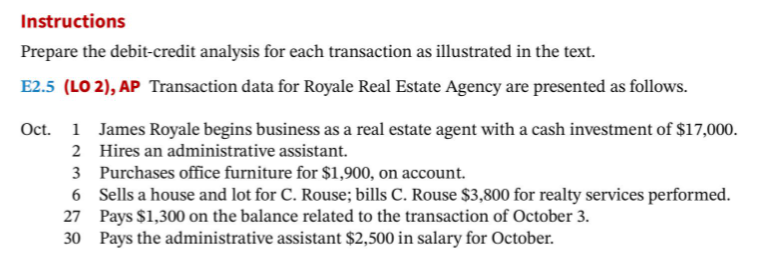
Why Most People Mess Up Their Debit and Credit Analysis
I spent years fixing other people's transaction analyses before I actually learned to do it right the first time. The problem is that debits and credits don't care whether you understand them or not. The accounting equation either balances or it doesn't, and when it doesn't, someone has to figure out where the numbers went wrong. That is usually you, at midnight, with a client breathing down your neck. So let's just walk through how Prepare The Debit Credit Analysis For Each Transaction, what the actual process looks like, and where the landmines are hidden. I'll cover the mechanics, throw in a couple of edge cases that aren't in any textbook, and point out the scenarios where this whole exercise starts falling apart anyway.
The Basic Framework
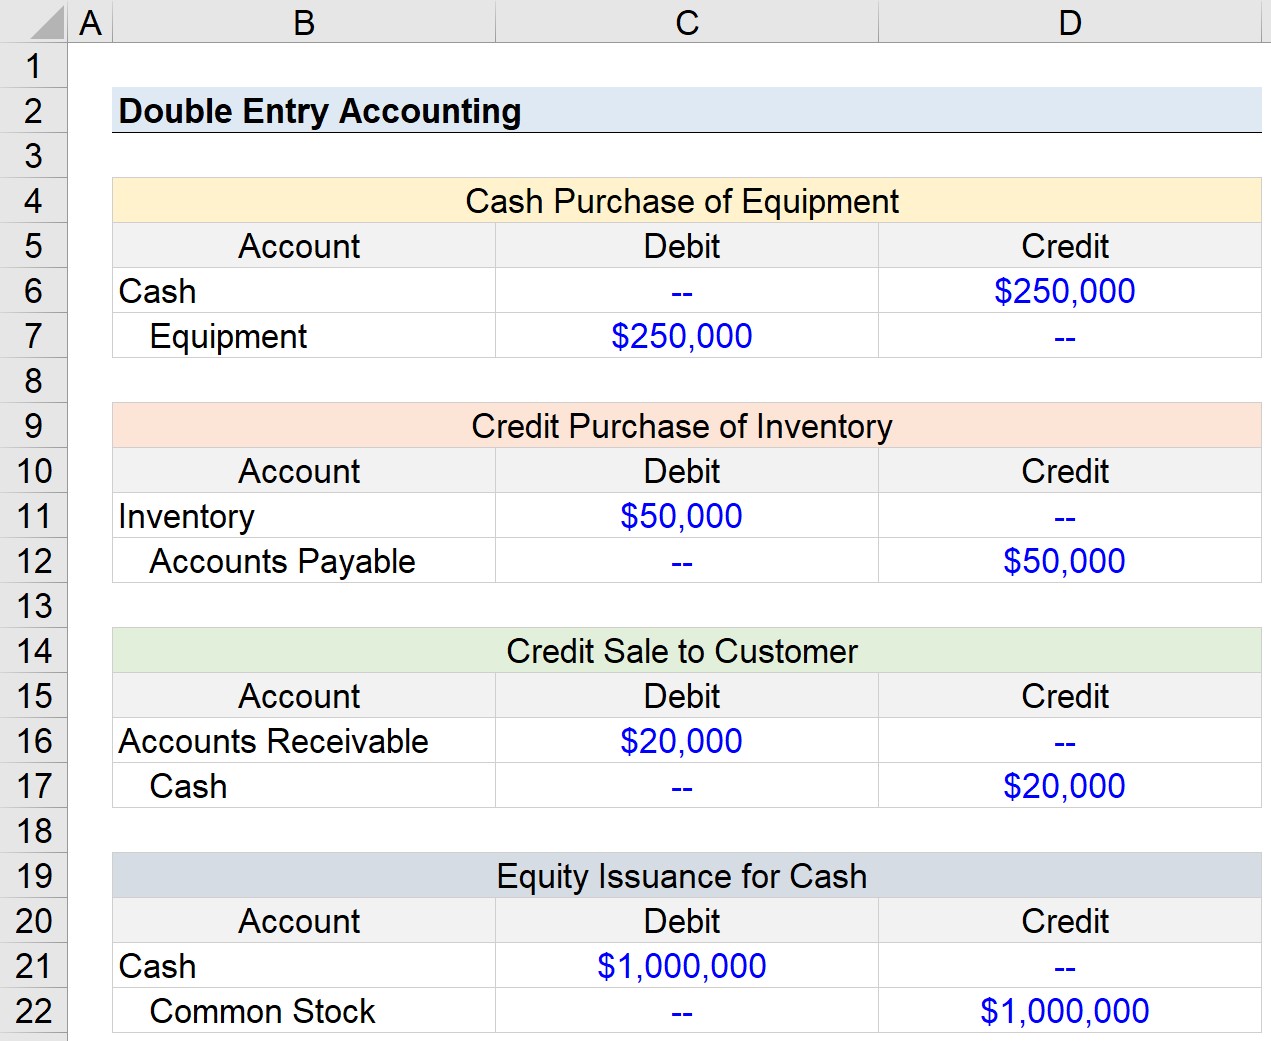
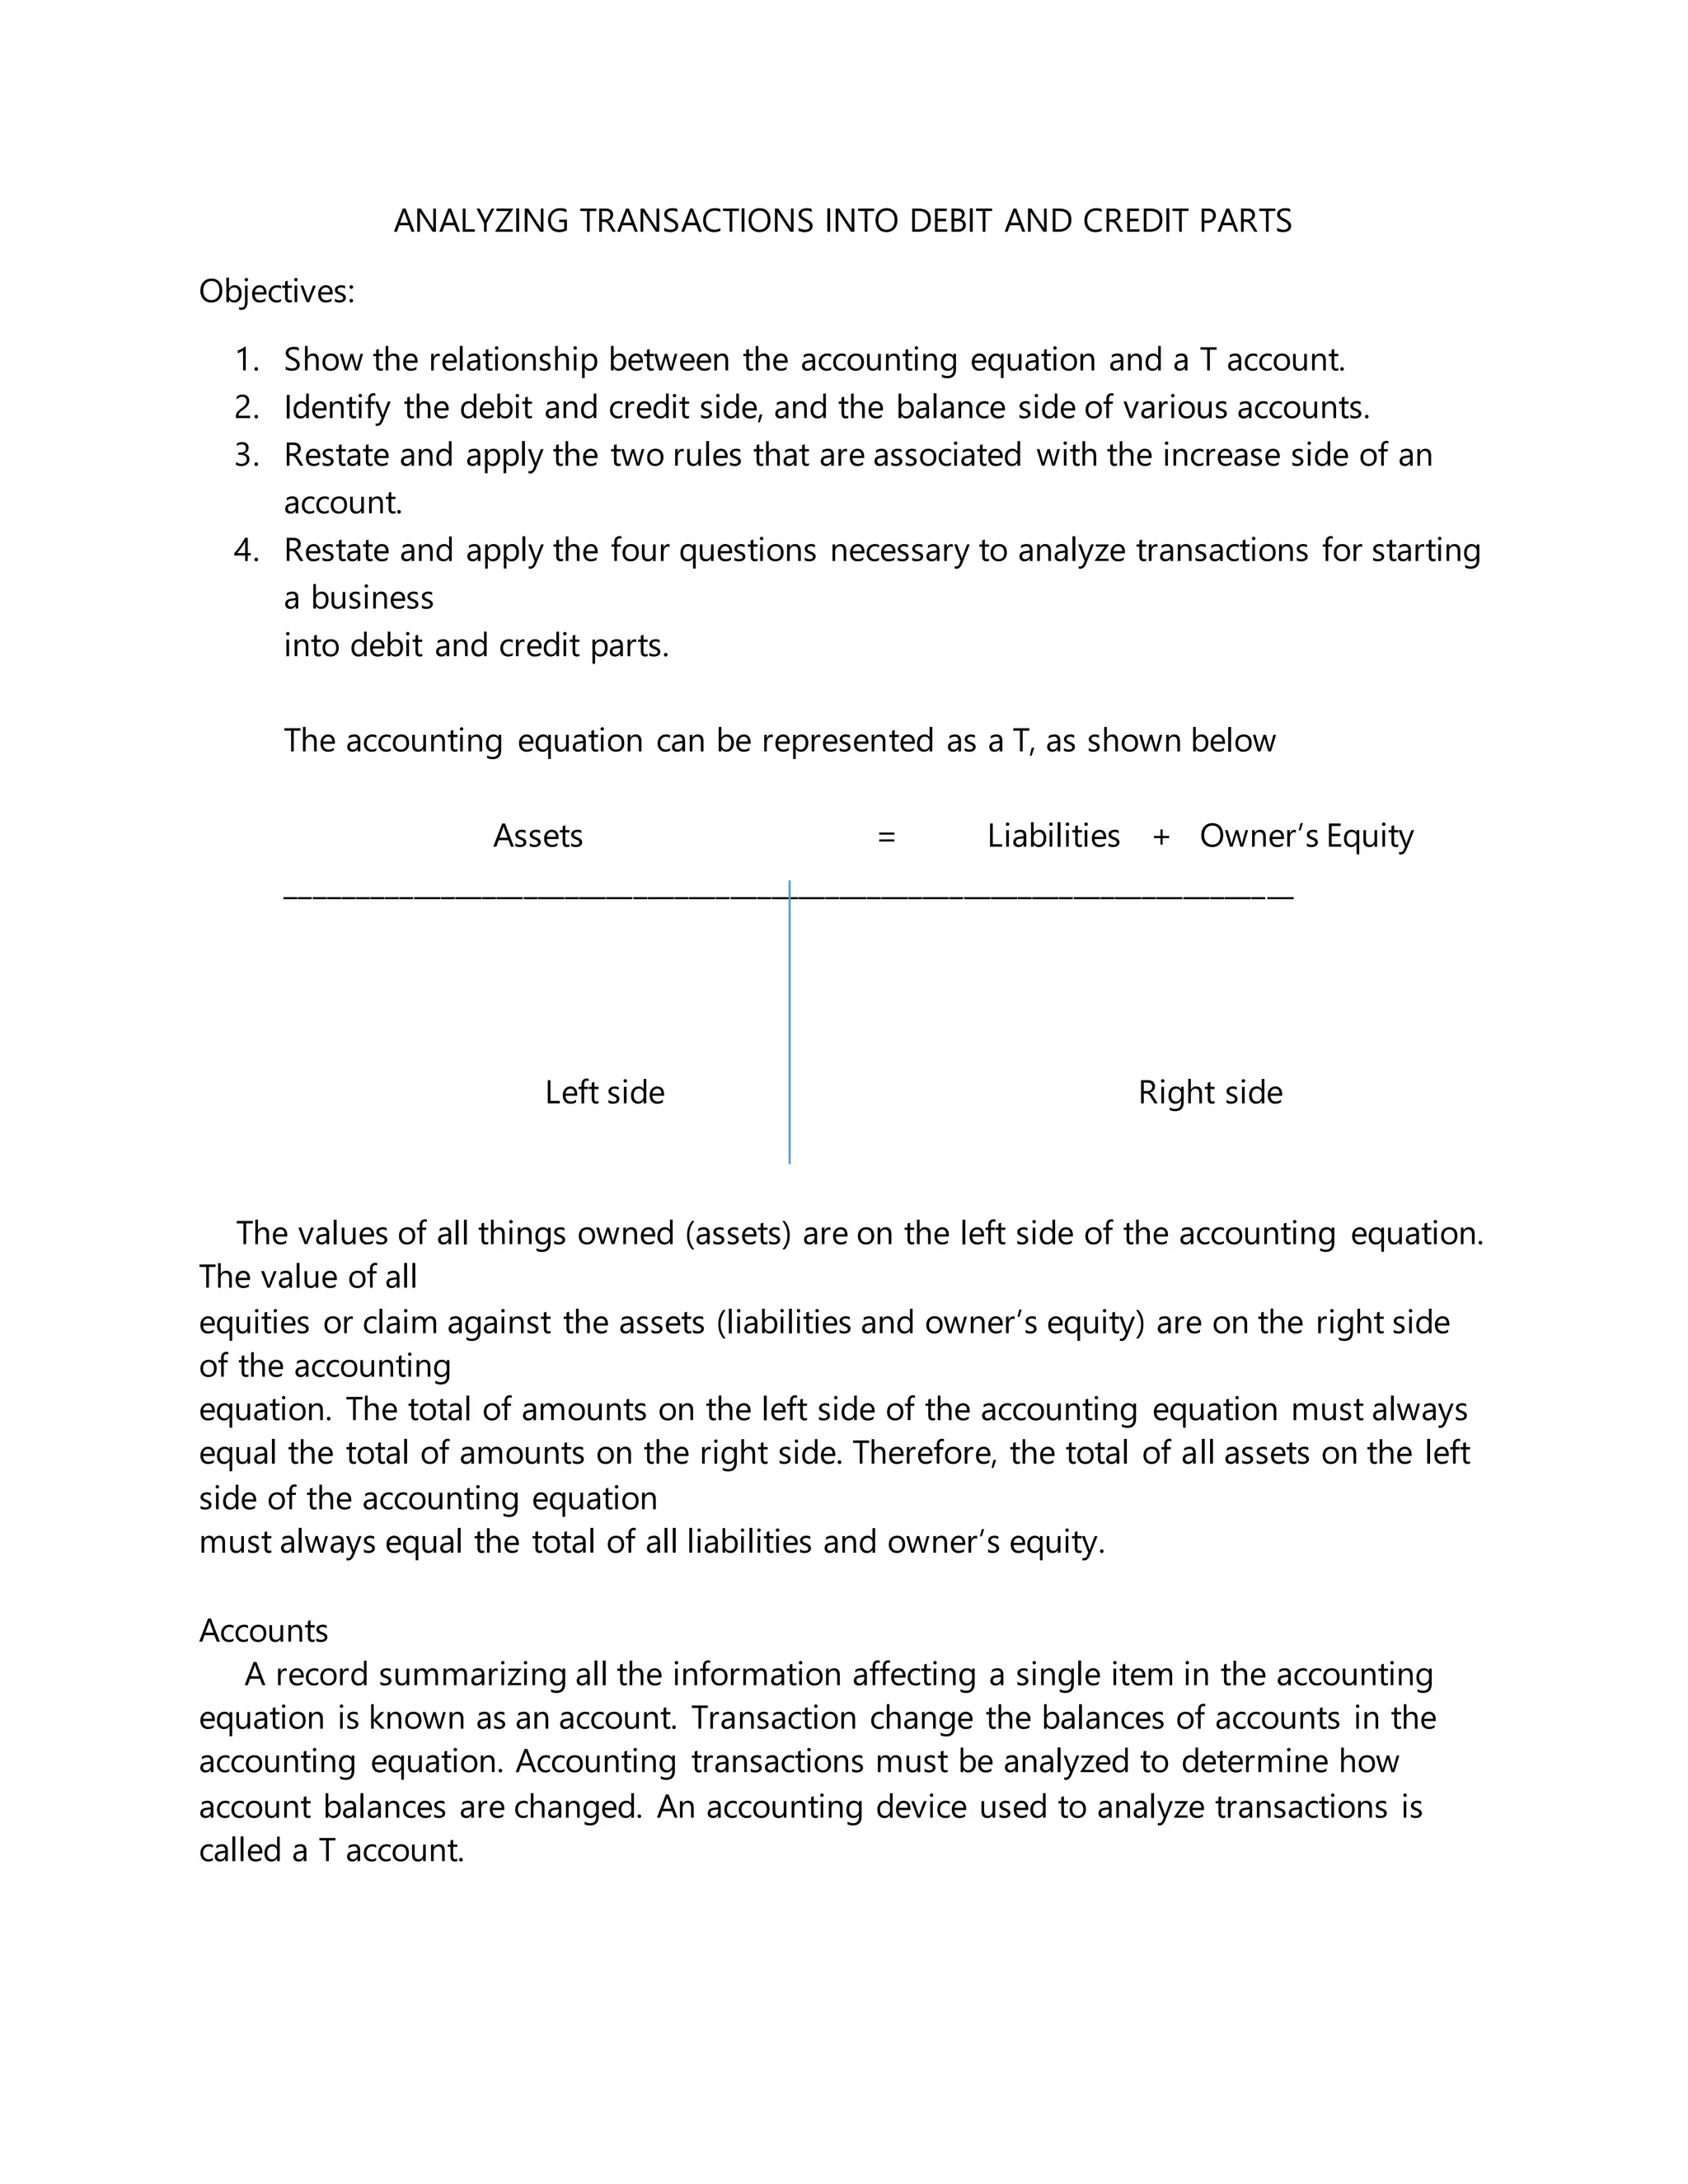
Every transaction affects at least two accounts, and every account is either a debit or a credit depending on its type. The five main categories are assets, liabilities, equity, revenue, and expenses. Assets and expenses increase on the debit side. Liabilities, equity, and revenue increase on the credit side. Revenue and expenses close out to equity at period end, which means they only exist as temporary accounts until that closing process happens. If you are trying to Prepare The Debit Credit Analysis For Each Transaction without keeping this framework fresh in your head, you will waste more time than you probably realize. Here is a practical breakdown of a common transaction: a business purchases equipment for $12,000 by taking out a bank loan. The analysis looks like this:
- Equipment (asset) increases — debit $12,000
- Bank Loan Payable (liability) increases — credit $12,000
Debits equal credits. The entry is balanced. This is what normal looks like. Normal doesn't always show up in real-world data, but it's the baseline you aim for. Write out the transaction in plain language first. Not in accounting terms, just describe what happened. "Company paid $3,500 for insurance covering the next twelve months." Once you have that, identify every account that changed. Two or more accounts will be involved. Then classify each one — asset, liability, equity, revenue, or expense. Then determine whether the account is increasing or decreasing. Then apply the debit/credit rule for that category. That's it. The entire method reduces to those four steps, repeated for every single transaction in the book. The part people skip and regret later is the plain-language step. If you jump straight from "Company paid $3,500 for insurance" to journal entries without naming the accounts first, you will misclassify half the time. Insurance Prepaid is an asset. Insurance Expense is an expense. They react completely differently to debits and credits. One goes on the balance sheet. The other sits on the income statement. Mixing them up ruins your trial balance instantly.
Get the Full Details

A Real Problem I Encountered
I once had a client who recorded a customer return as a credit to Accounts Receivable and a debit to Sales Returns and Allowances, which on its face looked fine. The problem was that the original sale had been recorded with a freight component that was billed separately on a different invoice. The return only covered the product cost, not the freight. The customer had already paid the freight, and the company wanted to refund it too. The debit/credit analysis for that transaction was straightforward, but the mapping to the original invoices was not. I ended up writing a small reconciliation script in Excel that pulled the invoice-level detail and matched each line item back to its source transaction. That cut what could have taken six hours of manual cross-referencing down to about twenty minutes. The workaround was ugly but effective. I created a separate workpaper that listed every affected account, the original transaction reference, the adjustment amount, and a memo explaining the discrepancy. That way anyone auditing the adjustment could follow the trail without needing my notes. This is exactly the kind of thing you run into when you Prepare The Debit Credit Analysis For Each Transaction across a high-volume chart of accounts.
Counter-Intuitive Things Beginners Miss
One thing nobody tells you early enough is that debits and credits are not inherently "good" or "bad." People try to memorize them by associating debits with positive numbers and credits with negative, which is completely wrong. A credit to cash is a decrease. A debit to cash is an increase. But a credit to revenue is also an increase. The direction depends entirely on the account type, not on whether the number is positive or negative. Another thing that trips people up is compound entries. Not every transaction has exactly one debit and one credit. Sometimes you need three debits and two credits, or any combination as long as the totals match. I've seen junior accountants refuse to post valid compound entries because they don't fit the "one debit, one credit" pattern they memorized. That is not a rule. The only rule is that total debits must equal total credits. Period.
Limitations and When This Method Fails
Debit-credit analysis works well for standard commercial transactions, but it starts getting fuzzy in a few specific scenarios. Foreign currency transactions require you to determine the exchange rate at the transaction date and then revalue at period end. The debit and credit structure is the same, but the dollar amounts change between dates, and that introduces foreign exchange gain or loss entries that are easy to miss if you are only looking at the original transaction. Similarly, accruals and deferrals are mechanically simple but easy to misdate. An accrued salary expense for the last week of December that gets recorded in January is technically correct in terms of debits and credits, but it is wrong on the timing side, which defeats the purpose of the analysis entirely. There is also the issue of materiality. When you are working with thousands of transactions and each one requires a full debit-credit breakdown, the process becomes a bottleneck. I have seen firms spend over two hours per batch of fifty transactions doing manual analysis when an automated workflow could do it in under fifteen minutes. If you are doing this manually at scale, you should seriously consider whether the time investment is worth it or whether a templated approach with standardized account mappings would serve you better. The analysis itself is still valid, but the delivery method matters just as much as the logic behind it.

Quick Reference for the Common Transactions
When you Prepare The Debit Credit Analysis For Each Transaction, these are the patterns you will hit repeatedly. A cash sale increases cash (debit) and increases revenue (credit). A credit sale increases accounts receivable (debit) and increases revenue (credit). A purchase of inventory increases inventory (debit) and decreases cash or increases accounts payable (credit). A payment on accounts payable decreases accounts payable (debit) and decreases cash (credit). A collection on accounts receivable increases cash (debit) and decreases accounts receivable (credit). Revenue is always credited when earned. Expenses are always debited when incurred. Assets increase with debits and decrease with credits. Liabilities and equity do the opposite. This repetition is what makes the system reliable once you internalize it.
Bottom Line
The method is not complicated. The difficulty comes from applying it consistently across messy, real-world data where transactions don't always come neatly labeled and where one error propagates through everything that follows. I have fixed analyses that were off by a single dollar because someone posted a debit instead of a credit to the wrong account two months prior. The fix was not hard, but tracing it back took longer than the actual correction. That is the reality of working with transaction-level debits and credits, and it is why every entry should be double-checked at the time it is recorded rather than assumed to be correct and revisited only during reconciliation.