A Practical Guide To Understanding The Core Frameworks
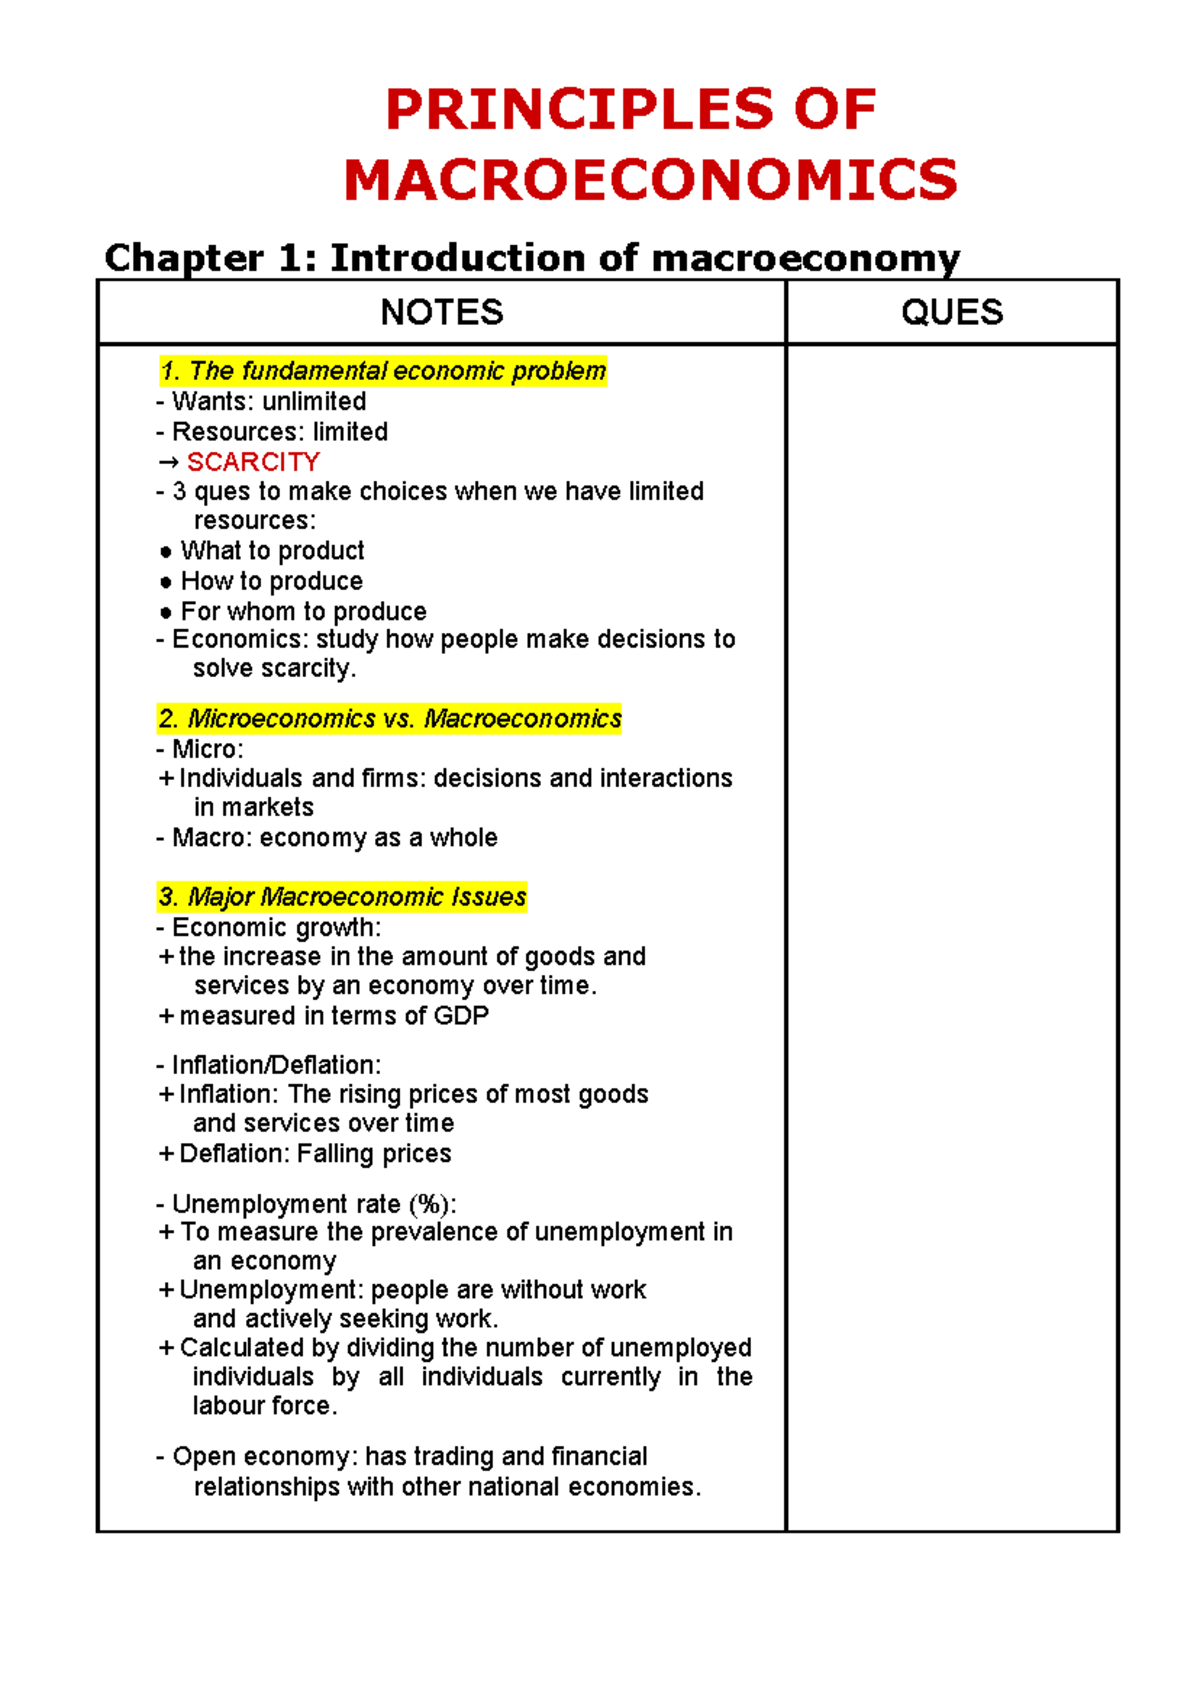
I remember looking at a developing country's annual GDP report and realizing that the textbook model for fiscal multipliers simply did not match the data in front of me. The numbers suggested the economy was absorbing stimulus like it was underwater. That mismatch is exactly where learning Principles Of Macro Economics becomes a survival skill rather than an academic exercise. You need to understand what the models actually assume, where they break, and what to do when reality refuses to cooperate. The most fundamental concept is the interaction between aggregate demand and aggregate supply. Aggregate demand represents total spending in an economy at different price levels. It includes consumption, investment, government spending, and net exports. Aggregate supply shows how much firms are willing to produce at each price level. In the short run, prices and wages are somewhat sticky, which is why the AS curve slopes upward. In the long run, everything adjusts and the AS curve becomes vertical at the economy's potential output. This distinction matters more than most beginners realize because policy implications change completely depending on which time frame you are analyzing. I learned this the hard way while working on a project for a regional development agency. They wanted to boost employment through increased infrastructure spending. The standard textbook answer would have been to calculate the multiplier and project job creation. What actually happened is more complicated. The economy was operating near full capacity already. Adding demand simply drove up prices instead of output. The multiplier was closer to zero than the textbook estimate of 1.5 to 2.0. I had to go back and recalculate everything assuming a short-run versus long-run AS curve intersection and explain why the policy would have been counterproductive.
Key Models That Actually Matter In Practice
There are several models you will encounter. Most of them are simplified representations, but a few are genuinely useful as working tools. The IS-LM model shows the equilibrium between the goods market and the money market. IS stands for investment-savings and represents equilibrium in the goods market. LM stands for liquidity preference-money supply and represents equilibrium in the money market. The intersection gives you the equilibrium interest rate and output level. It is a straightforward diagram that helps you visualize how fiscal and monetary policy shift the curves. The IS curve shifts right when government spending increases or taxes decrease. The LM curve shifts down when the central bank increases the money supply. The model predicts that fiscal policy is more effective when the LM curve is flatter and monetary policy is more effective when the IS curve is flatter. These predictions match intuition once you think about what the slopes actually represent in terms of interest sensitivity. The AD-AS model combines the IS-LM framework with the aggregate supply curve to show how price levels adjust over time. This is where you get the full picture of how policies affect both output and inflation. The aggregate demand curve slopes downward because of the wealth effect, the interest rate effect, and the exchange rate effect. Higher prices reduce the real value of money holdings, which pushes people to spend less. Higher prices also raise the demand for money, which raises interest rates and reduces investment. Higher domestic prices make exports more expensive and imports cheaper, reducing net exports.
I once had to explain all three of these channels to a group of local policymakers who kept confusing nominal and real variables. They wanted to know why their currency devaluation had not stimulated growth as predicted. The answer involved the Marshall-Lerner condition, which states that devaluation only improves the trade balance if the sum of price elasticities of exports and imports exceeds one. In their case, neither elasticities were above 0.5, so the condition was not satisfied. The devaluation simply made everything more expensive without boosting competitiveness. This is the kind of detail that separates people who understand the principles from people who just memorize the diagrams.
Get the Full Details

Working Through The Mathematics And Data
If you want to apply these principles practically, you need to be comfortable with some basic algebra and statistics. The consumption function is usually written as C = a + bYd, where C is consumption, a is autonomous consumption, b is the marginal propensity to consume, and Yd is disposable income. The multiplier is 1 divided by 1 minus the marginal propensity to consume, or more generally 1 over 1 minus the slope of the aggregate expenditure curve. If the MPC is 0.8, the multiplier is 5. This means every dollar of autonomous spending increases GDP by five dollars. The savings function is S = -a + (1-b)Yd. In equilibrium, leakages equal injections, so savings plus taxes equals investment plus government spending. This identity is useful because it connects the goods market to the broader economy. You can rearrange it to solve for equilibrium output given any set of fiscal parameters. For data, the main sources are national income accounts. Most countries publish quarterly or annual GDP, consumption, investment, government spending, and trade data. The World Bank and IMF maintain comprehensive databases that cover 190+ countries. You can download this data and run simple regressions to estimate key parameters like the MPC or the output gap. A basic regression of consumption on disposable income using time series data will give you an estimated MPC that you can compare against official statistics and theoretical expectations.
One practical tip that took me years to learn: always check the definition of the variables before using any dataset. GDP can be measured at market prices or factor cost. Consumption can include or exclude durable goods. Investment can include or exclude inventory changes. Mixing incompatible definitions will give you garbage results that look plausible on the surface. I once spent three days debugging a model only to discover the investment data I was using excluded residential construction while my consumption data included it. The discrepancy was small in absolute terms but large enough to throw off every projection.
Common Pitfalls And Advanced Nuances
Beginners make the same mistakes repeatedly. The first is confusing stock and flow variables. Money supply is a stock measured at a point in time. Investment is a flow measured over a period. Treating them as interchangeable produces nonsensical results. The second mistake is ignoring expectations. Modern macroeconomics emphasizes that expectations about future policy shape current behavior. If people expect higher inflation in the future, they will demand higher wages now, which shifts the short-run AS curve leftward and reduces the effectiveness of expansionary policy. This is the expectations-augmented Phillips curve, and it explains why the original Phillips curve relationship broke down in the 1970s. The liquidity trap is another area where theory meets messy reality. When interest rates approach zero, the LM curve becomes horizontal and monetary policy loses its traction. Increasing the money supply does not lower interest rates further because people are indifferent between holding money and bonds at that point. Fiscal policy becomes the primary tool, but even it faces headwinds from Ricardian equivalence, which suggests that rational agents will save any temporary tax cuts because they expect future tax increases to balance the budget. The empirical evidence on Ricardian equivalence is mixed, but it is worth keeping in mind when evaluating policy proposals. I encountered a particularly stubborn edge case while consulting for a central bank in Southeast Asia. They were dealing with simultaneous high inflation and stagnant growth, which is a classic stagflation scenario. The standard policy response would have been to raise interest rates to combat inflation, but doing so would have crushed the already weak demand side. I spent two weeks building a small DSGE model to simulate different policy paths. The model incorporated supply-side rigidities, imported inflation through the exchange rate channel, and forward-looking expectations. The key insight was that the inflation was primarily cost-push, driven by rising energy prices and a depreciating currency, not demand-pull. Raising rates would have made things worse by deepening the output gap and triggering a vicious cycle of further depreciation.

The workaround was a combination of targeted supply-side interventions and carefully calibrated monetary tightening. We identified specific bottlenecks in the energy distribution network that were amplifying price increases. Fixing those bottlenecks reduced the pass-through from exchange rate movements to domestic prices. At the same time, the central bank raised rates modestly to anchor expectations without crushing demand. The result was a gradual disinflation over 18 months with only a minor contraction in output. It was not a perfect solution, but it was the best we could achieve given the constraints.
Limitations Of The Standard Frameworks
No macroeconomic model is complete. The IS-LM framework assumes a closed economy with fixed prices in the short run and ignores the financial sector entirely. The AD-AS model does not explain where the short-run AS curve comes from at a micro level. New Keynesian models add nominal rigidities but often rely on arbitrary Calvo pricing assumptions. Real Business Cycle models strip out nominal variables entirely and attribute all fluctuations to technology shocks, which most economists find unsatisfactory as a complete explanation. The biggest limitation across all these models is the treatment of institutions. None of them adequately capture how banking regulations, labor market structures, or political economy factors shape macroeconomic outcomes. A model that ignores the fact that credit constraints can prevent firms from investing despite low interest rates will systematically overestimate the effectiveness of monetary policy. Similarly, a model that assumes perfect labor mobility will underestimate the persistence of unemployment during recessions. If you are looking for a more complete toolkit, I would recommend supplementing standard macro models with sectoral financial flow analysis and agent-based simulations where available. These approaches do not replace traditional methods but they fill in gaps that the standard frameworks leave empty. The field is moving in this direction, but most introductory courses still teach the old material. You will need to seek out advanced textbooks and research papers to fill the gap yourself.
Data sources worth bookmarking include the FRED database from the Federal Reserve Bank of St. Louis for US data, the OECD Statistical Database for developed economies, the World Bank's World Development Indicators for cross-country comparisons, and the IMF's International Financial Statistics for financial and balance of payments data. All of these are freely accessible and updated regularly. Learning to navigate these databases efficiently will save you countless hours compared to trying to reconstruct data from scattered sources. The bottom line is that Principles Of Macro Economics gives you a vocabulary and a set of tools for thinking about complex systems. It will not predict every outcome accurately. It will sometimes give you wrong answers when conditions violate its assumptions. But it is far superior to the alternative of having no structured way to think about the problem at all. The value is not in getting perfect predictions. It is in avoiding obvious mistakes and understanding which levers matter in any given situation. That is a skill that takes years to develop and a lifetime to refine.